Jim Cramer Says Reinvesting Dividends Is “Where Some Big Money Can Be Made.” Is He Right?
Jim Cramer called dividend reinvestment plans the place where some big money gets made, but the tax code and the risk of concentration tell a more complicated story about who should actually follow that advice.

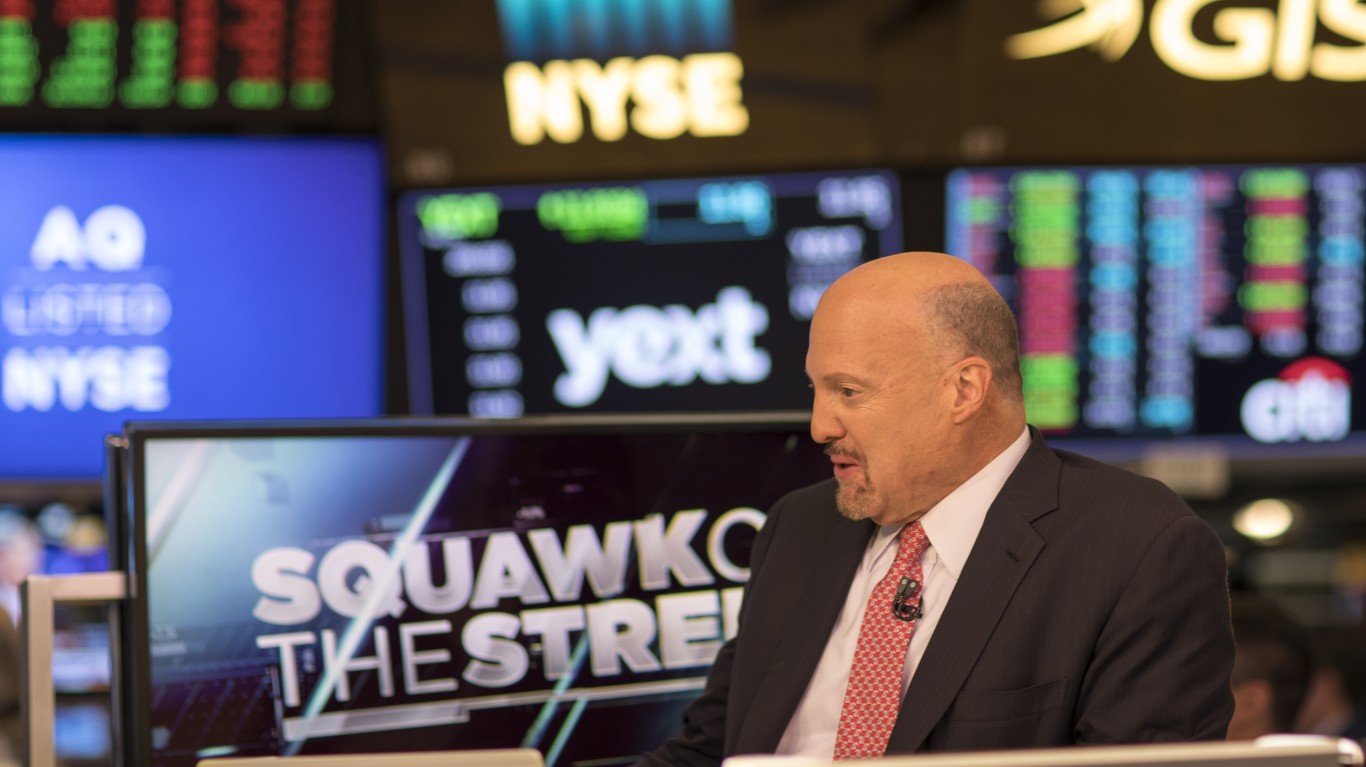
A caller asked Jim Cramer something almost every income investor eventually faces during the October 22, 2026 episode of Mad Money: should a brokerage automatically reinvest dividends through a DRIP, or should the cash land in the account so the investor can invest it by hand? Cramer answered: “I am a huge dividend reinvestment plan person. You’ve got to reinvest them. That’s where some big money can be made.”
He has made this case before. In August, Cramer told a caller that his charitable trust must send out its dividends, and he said, “It has really hurt my long-term performance.” For investors still building wealth, the math supports him. The exceptions and the tax bill deserve equal attention.
How a DRIP Puts Every Dividend to Work
A dividend reinvestment plan takes your dividends and uses them to buy more shares of the same stock. Most mutual funds also let shareholders reinvest distributions automatically, according to IRS Publication 550. Most brokerages buy fractional shares, so the whole payout goes back into the position on the payment date.
Each new share then earns its own dividend the next quarter. Take a hypothetical $10,000 position yielding 3%, paid quarterly, with a share price that never moves. An investor who takes the cash collects $9,000 over 30 years and still owns a $10,000 position. Reinvesting every payout grows the position to about $24,514, generating roughly $735 a year in dividends, compared with the $300 the cash recipient still receives. Price gains or dividend raises widen that gap.
On the same episode, Cramer described sending small checks to the Fidelity Magellan Fund for decades: “The power of compounding. I never touched it.”
When Taking the Cash Makes More Sense
Retirees living on portfolio income are the clearest case. If dividends pay for groceries and property taxes, reinvesting them only forces share sales later to raise the same money. Collecting the payout is the plan working as designed. Cramer still wants retirees to keep a mix of assets: “People should always be investing for growth and some for dividend and then some for bonds.”
Manual redeployment also suits investors who want control. A DRIP keeps buying whatever paid the dividend, which can slowly concentrate a portfolio in its biggest payers. Cramer learned the cost of concentration at Goldman Sachs (NYSE:GS | GS Price Prediction), remembering that “those who owned nothing but oil stocks, including yours truly” took heavy losses. Collecting dividends lets you send them to an underweight holding or a new idea.
Reinvested Dividends Still Trigger a Tax Bill
In a taxable account, the IRS taxes reinvested dividends in the year they are paid. If you use dividends to buy more stock at fair market value, “you must still report the dividends as income.” If the plan offers shares at a discount, you report the fair market value of the additional stock on the dividend payment date as dividend income. The tax code says the dividend portion of a distribution “shall be included in gross income” (26 U.S.C. § 301(c)(1)). That tax has to come from cash you never actually received.
There is an offset. Every reinvestment creates a new tax lot with its own cost basis, which lowers the taxable gain when you sell. Keep those records so you avoid paying tax twice on the same dividend. In IRAs and 401(k)s, reinvested dividends go untaxed until withdrawal.
Verdict: Who Should Follow Cramer’s Advice
Cramer is right for investors with a long time horizon who don’t need the income: younger savers, mid-career workers, and anyone reinvesting inside a tax-advantaged account. Automatic reinvestment keeps cash from sitting idle and gives compounding decades to work (the same mechanism behind the dividend ladder we laid out in a free guide here: Never Touch the Principal).
Retirees who depend on dividends for living expenses have the strongest case for taking the cash. So do investors whose DRIP keeps adding to an already large position, and taxable-account holders who lack spare cash to pay tax on dividends they never received. Many investors split the difference: reinvest automatically in retirement accounts, take cash in taxable accounts, and redeploy it on purpose.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.