Nebius Has Cratered Over The Last 3 Months: This Wall Street Ratings Firm Says 2.5X Returns Will Materialize Soon
A Gartner forecast just sparked a brutal selloff that wiped nearly half of Nebius Group's value from its peak, yet one Wall Street firm now sees shares more than doubling from here. The question is whether the neocloud model survives…

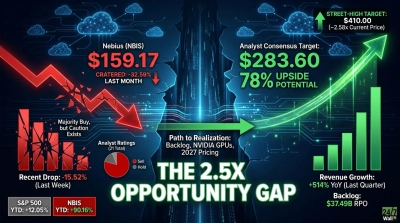
Nebius Group (NASDAQ:NBIS | NBIS Price Prediction) trades at $159.17, and Wall Street’s average price target is $283.60. That implies about 78% upside to where analysts think the shares should trade.
Nebius leases NVIDIA GPU capacity to AI labs and enterprises. Its Nebius AI Cloud segment brought in $574.9M last quarter, up 514% year over year. Hyperscale contracts with Meta and Microsoft helped build $37.49B in remaining performance obligations, which is why the Street keeps such close watch on the stock.
Northland Securities holds the Street-high target of $410.00, roughly 2.58x the current price. With implied upside above 40%, analyst targets frame the outlook for the stock.
Neocloud Extinction Fears Drive a Steep Monthly Sell-Off
A Gartner forecast set off the latest wave of selling. It predicted that “cost pressure and a lack of a differentiating business model will force over 80% of neocloud providers to cease independent operations” by 2030. Nebius has fallen 32.59% in the past month. It lost 15.52% in the past week alone. The stock now sits about 47% below its 52-week high of $299.86.
The damage hit the whole sector. Rate-hike fears hit the AI debt market at the same time, according to 24/7 Wall St. coverage. DA Davidson’s Gil Luria said Nebius and CoreWeave (NASDAQ:CRWV) “literally sell the same thing to the same companies,” so investors are questioning the neocloud model as a whole.
The last quarter itself held up. Revenue of $582.3M beat the $574.65M consensus. Even so, the operating loss reached $175.9M, first-half capex reached $8.13B, and three customers made up 24%, 21%, and 14% of revenue.
Northland’s $410 Target Rests on 2027 Pricing Power
Of the 21 analysts tracked, 2 rate it Strong Buy, 12 Buy, 5 Hold, 1 Sell, and 1 Strong Sell. Northland’s Nehal Chokshi keeps an Outperform rating, and BNP Paribas Exane’s Stefan Slowinski holds a $399.00 target. Northland’s thesis centers on the company’s data center buildout across Europe and North America, early access to next-generation NVIDIA GPUs, and multiple expansion as markets price Nebius as a pure-play AI cloud operator.
The near-term marker is full-year guidance, which management reaffirmed: revenue of $3 billion to $3.4 billion, annualized run-rate revenue of $7 billion to $9 billion, and roughly 40% adjusted EBITDA margin. Analysts expect third-quarter revenue of about $904.8 million.
CEO Arkady Volozh said Nebius “could sell today our entire 2027 capacity on these terms if we wanted to.” Short-duration deals are being set at $40 million to $50 million per megawatt, and the contracted power target rose to 5 gigawatts. Management says formal 2027 guidance comes later this year.
Price targets are estimates and carry no guarantee. All of this depends on Nebius bringing capacity online on schedule while capital markets stay open.
CoreWeave and Oracle Fell Too, With Even Wider Gaps
The whole peer group sold off together, and Nebius carries the lowest implied upside of the three.
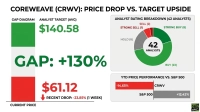
CoreWeave trades at $55.60 after falling 36.02% in a month. Its $138.34 target implies about 149% upside. Of 42 analysts, 8 rate it Strong Buy and 23 Buy, and Goldman Sachs recently upgraded it to Buy. Its 8.94 debt-to-equity ratio explains part of the discount.
Oracle (NYSE:ORCL) trades at $125.54, down 13.16% in a month. Its $237.36 target implies roughly 89% upside. Of 43 analysts, 7 rate it Strong Buy and 28 Buy.
CoreWeave holds the largest analyst-implied upside. Nebius looks like the group’s relative winner, priced with less distress than its peers.
Nebius Is Still Up 90% This Year Despite the Drawdown
At $159.17, Nebius trades with about 78% implied upside to the $283.60 consensus from 21 analysts. Shares are down 27.97% over three months but still up 90.16% year to date.
The S&P 500 has gained 12.05% year to date and slipped 1.21% over the past month. Nebius trades at about 46x forward earnings.
Backlog Supports the Upside, but Dilution Caps the Ceiling
The bull case strengthens if the 2027 pricing Volozh described holds and the third-quarter report confirms new capacity is turning into revenue. That path leads back toward the consensus target.
The bear case gains weight if Gartner’s consolidation call is right. Convertible debt with a fair value of $20.8B, $12.1B in upcoming lease obligations, and ongoing share sales could dilute holders even if revenue keeps growing.
I lean positive. The backlog looks durable, and management guides to roughly 40% adjusted EBITDA margin. The $410 target needs everything to go right, though, so the consensus figure is the more realistic benchmark. Nebius is one of several picks-and-shovels names riding the data-center buildout, and we rounded up seven more in a free report on AI infrastructure stocks that aren’t chipmakers.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.