Nebius Lost 35% Last Month As Contagion Spikes: One Wall Street Pro Says 165% Gains Are Coming
Nebius shed a third of its value in a single month without a single piece of bad earnings news, and now one Wall Street analyst thinks the selloff created a setup for triple-digit gains. Here is what the bull case…

Nebius Group (NASDAQ:NBIS | NBIS Price Prediction) currently trades at $154.14, and the average Wall Street price target is $281. That gap works out to 82.3% upside.
Nebius rents out GPU compute, inference and managed AI services that run on NVIDIA hardware. It sells them through Nebius AI Cloud, which brought in 98% of group revenue last quarter. Wall Street has been paying attention. Deals like a $27B five-year Meta agreement and a $37.5B backlog of remaining performance obligations explain why.
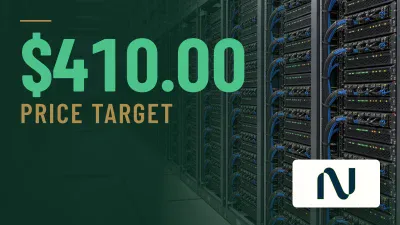
The Street’s most bullish analyst sees far more upside than the average. Northland Securities holds the Street-high $410.00 target, which implies about 166% upside. The stock fell more than 30% in a month while consensus implies 82.3% upside, so investors have to decide whether this is an overreaction to contagion or a fair discount for a business that needs enormous amounts of capital.
Neocloud Contagion Erased a Third of Nebius in a Month
Nebius shares fell 34.65% over the past month. Nebius released no earnings or contract news to explain the drop. The first blow came from Gartner, which predicted that more than 80% of neocloud providers will stop operating independently by 2030. Gartner cited cost pressure and “a lack of a differentiating business model.”
Fear then spread from CoreWeave (NASDAQ:CRWV). Investors worried about its debt load after hotter inflation data lifted bets on rate hikes. Microsoft then reported capital spending that fell short of estimates, which sent the group down again. In the latest session alone, Nebius dropped 10.38%, compared with a 1.77% dip for the S&P 500.
Nebius has funding risks of its own. It carries $8.5B of convertible debt at book value. It also sold 12.7 million shares through its at-the-market program at $224. The company expects $20 billion to $25 billion of capex in 2026. Three customers made up 24%, 21%, 14% of second-quarter revenue.
Northland’s $410 Target Depends on 2027 Capacity and Pricing
Most analysts are staying put. Of 21 analysts covering the stock, 2 rate it a Strong Buy, 12 a Buy, 5 a Hold, 1 a Sell and 1 a Strong Sell. Northland’s Nehal Chokshi raised his target from $248.00 to $410.00 and kept his Outperform rating.
Northland’s case has three parts. It expects Nebius to win an oversized share of the market for leasing AI infrastructure as a service. It expects low-cost power to widen margins. And it puts about $29 per share of value to Avride, TripleTen and Toloka.
The operating results back up the growth side of that case. Second-quarter revenue reached $582.3M, up 454% from a year earlier, with a 41% adjusted EBITDA margin. Annualized run-rate revenue hit $3 billion at the end of the quarter. Management confirmed its year-end run-rate target of $7 billion to $9 billion. Deals signed in Q2 brought in $20 million to $25 million per megawatt, and customer prepayments covered 50% to 60% of the related capex. Management said Nebius “could sell today our entire 2027 capacity on these terms if we wanted to.”
Executives said the biggest revenue impact from new contracts arrives in 2027, and formal 2027 guidance is due later this year. Price targets are estimates. This one also depends on Nebius reaching its year-end goal of 5 gigawatts of contracted power.
CoreWeave and Applied Digital Show Even Wider Gaps
The whole neocloud group sold off together, and analysts see bigger rebounds elsewhere.
CoreWeave fell 37.02% over the past month to $54.87. Its average target is $134.58, which implies 145.3% upside. Most of its 42 analysts are bullish. 31 rate it a Buy or Strong Buy, and Goldman Sachs recently upgraded it to Buy. A debt-to-equity ratio of 8.94 helps explain the steeper discount.
Applied Digital (NASDAQ:APLD) dropped 26.9% in a month to $17.82. Its average target of $60.94 implies 242% upside. Thirteen of its 15 analysts rate it a Buy or Strong Buy, and none rate it a Sell. Treat that target with caution, since it is above the stock’s 52-week high of $50.73.
Applied Digital has the largest implied upside among these stocks, and Nebius has the lowest. That ranking mostly reflects how much better Nebius has held up this year.
An 84% Year-to-Date Gain Survives the Slide
At $154.14, Nebius is well below the $281 consensus target from 21 analysts, an implied 82.3% upside. The stock lost 34.65% over the past month, while the S&P 500 slipped 0.91%.
Over the longer term, Nebius is up 84.15% year to date, compared with 10.82% for the S&P 500. Its 52-week range runs from $73.52 to $299.86, and it trades at a forward P/E of 31.
Nebius Rewards Patient Investors Who Can Stomach Dilution
Bulls get more confidence if the 2027 capacity expansion arrives on schedule and pricing holds near the $20 million to $25 million per megawatt it booked in Q2. If that happens, the $37.5B backlog turns into revenue and margin, and $281 comes within reach.
Downside risks grow if Gartner’s call on consolidation proves right and supply catches up with demand. In that case pricing slips, convertible securities and at-the-market share sales keep diluting holders, and the heavy reliance on Meta and Microsoft becomes a liability.
Nebius has contracted demand. It has $236 million of quarterly adjusted EBITDA and far less net debt than CoreWeave, so a contagion selloff of more than 30% looks overdone. Still, the $410 target needs everything to go right, so I’d set expectations closer to the consensus.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.