Buy Nebius’ Bounce Even Though It’s Still Down 30% Over a Month? One Analyst Predicts 165% Returns So It Is Tempting

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Nebius Group (NASDAQ:NBIS | NBIS Price Prediction) trades at $154.69, while Wall Street’s average price target stands at $278.05. That works out to an implied upside of 79.7%.
Nebius rents GPU capacity to AI labs, hyperscalers and enterprises. Its AI Cloud segment brought in $574.9 million of second-quarter revenue, up 514% year over year. Its backlog includes a Microsoft (NASDAQ:MSFT) deal worth at $17.4 billion to $19.4 billion and a second $27 billion Meta (NASDAQ:META) agreement. The hyperscalers signing these deals also need the power, cooling and networking suppliers we profiled in a free AI infrastructure report here.
Nebius reports third-quarter results this week, and the stock just jumped 15.44% in a single session.
A Neocloud Debt Scare and a Blue Wave Dragged Nebius Lower
Sector-wide debt concerns did most of the damage. Nebius fell 26.36% over the past month, slipping from $210.06. In mid-October, a tweet-fueled selloff sent CoreWeave (NASDAQ:CRWV) down 15% as its 2032 bond yield hit 15.77%. Nebius fell about 5% the following day. Gartner piled on with a forecast that more than 80% of neocloud providers will stop operating independently by 2030.
Then came the midterms. After Democrats won both chambers of Congress, Nebius dropped 6% in one session. UBS estimated about 30% of new data centers expected over the next two years could be affected.
Very little of this traces back to Nebius itself. DA Davidson’s Gil Luria said the company has “almost no financial leverage.” Second-quarter revenue of $582.3 million beat the $574.65 million estimate.
Why Northland Still Sees 165% Upside
Northland Capital Markets analyst Nehal Chokshi has the Street-high target of $410.00. He raised it from $248.00 and reaffirmed it ahead of the third-quarter report. From here, that target means 165% upside. Rothschild & Co Redburn is at $399.00, Truist at $355.00 and DA Davidson at $340.00.
Pricing power is the core of the bullish argument. Management says short-term capacity is selling for $40 million to $50 million per megawatt, compared with $20 million to $25 million on core deals. The CEO said Nebius “could sell today our entire 2027 capacity on these terms if we wanted to.” Its first capacity auction cleared 15% above the highest price it had ever charged.
Analysts also expect the backlog to turn into revenue. Nebius reports $40 billion in contracted backlog and a 5 gigawatt contracted power target. It plans to add more than 1 gigawatt of new capacity a year starting in 2027. Northland models 30% terminal free cash flow margins in line with CoreWeave. It also attributes about $29.00 per share to non-core units like Avride and Toloka.
The consensus 2027 EPS estimate has fallen to -6.1573 from -4.6586 60 days ago. Two analysts give the stock a Strong Buy rating, 13 a Buy, six a Hold and one a Sell. Like any price target, $410 is one firm’s model and comes with no guarantee.
CoreWeave and Applied Digital Fell Just as Hard With Wider Gaps
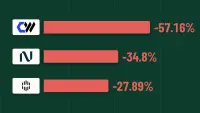
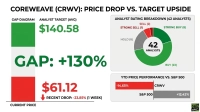
These stocks all fell together. CoreWeave lost 24.28% over the month before rising 24.71% after third-quarter revenue of $3.661 billion beat estimates. At $60.77 against a $131.53 target, it offers 116.4% implied upside. Of the analysts covering it, 8 have a Strong Buy, 24 a Buy, 7 a Hold and 3 a Sell or Strong Sell. Its debt load explains the deeper discount.
Applied Digital (NASDAQ:APLD) fell 22.97% over the month. At $17.91 versus a $59.94 target, it offers 234.7% implied upside. Fourteen of its 16 analysts have a Buy or Strong Buy rating on the stock, and none have a Sell.
Applied Digital has the largest analyst-implied upside in the group. Nebius has the smallest, which suggests Wall Street sees it as the least damaged name in the group.
Up 84.8% This Year Even After the Slide
At $154.69, Nebius offers 79.7% implied upside to the $278.05 consensus target set by 22 analysts. The stock is still up 84.8% year to date, compared with 11.41% for the S&P 500. Over the past month, Nebius lost 26.36% while the index slipped 2.36%.
The stock trades at about 29x forward earnings, well below its 52-week high of $299.86. Earlier this year, Nebius sold shares through its at-the-market program at an average of $223.60, well above today’s price.
What Could Make or Break Nebius After the Debt Scare
The upside story improves if third-quarter results show premium per-megawatt pricing holding up and its 800 megawatts to 1 gigawatt of connected power starting to produce revenue. The downside risk grows if capital spending of $20 billion to $25 billion forces more share sales at these lower prices, or if election-driven permitting delays push back 2027 capacity.
The fundamentals support the bullish argument. Nebius has a cleaner balance sheet than CoreWeave and is still selling out its capacity. It fell alongside heavily indebted peers even though its fundamentals held up better. The consensus target is a more realistic goal than $410. Keep an eye on the stock’s reaction to the earnings report.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.