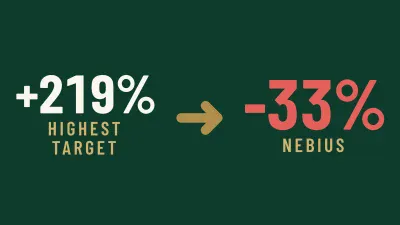
Nebius Plummeted 33% in 3 Months: High Target Price Predicting 220% Gains Holds Steady Ahead of Q3 Earnings as Firm Avoids Nvidia Entanglement

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Shares of Nebius Group (NASDAQ:NBIS | NBIS Price Prediction) currently trade at $128.64, while Wall Street’s average price target sits at $278.05. The difference suggests 116.1% upside.
Nebius sells GPU compute through Nebius AI Cloud, which generates about 99% of revenue, putting it among the non-chipmaker names cashing in on the AI data-center expansion (we covered seven such suppliers in a free AI infrastructure report). Wall Street has followed it closely because of a second $27B five-year agreement with Meta, a $2B strategic equity investment from NVIDIA (NASDAQ:NVDA), and several other multi-year enterprise deals.
The gap matters because the most bullish target of $410.00 from Northland Capital Markets implies 218.7% upside. No major firm cut its rating or target in the week before the earnings report, even as news broke that Nvidia CEO Jensen Huang resigned. Nebius is a customer and partner with no governance or regulatory entanglement in that story.
A Guidance Trim and a $27 Billion Capex Bill Sent Nebius Down Over 50%
Nebius fell 16.84% in its latest session after cutting 2026 revenue guidance to $3 billion to $3.2 billion from $3 billion to $3.4 billion and lifting 2026 capex to around $27 billion. That ended a 50.37% three-month collapse from $259.20.
Revenue of $980.8M beat the $905.74M consensus, and GAAP EPS of -$0.13 topped the -$1.238 estimate. Investors focused instead on roughly $325M of non-recurring revenue, colocation delays at New Jersey and Vineland, and a 2027 capex plan of $40-45B.
Sector weakness amplified the damage. Neocloud names slid together over the past month while the S&P 500 fell only 2.67%.
Analysts Are Anchored to Prepayments and a $12-13B Revenue Outlook for 2027
Of 22 covering analysts, 2 rate it Strong Buy, 13 Buy, 6 Hold and 1 Sell. The top desks have repeated: Rothschild & Co Redburn at $399.00, Truist at $355.00 and DA Davidson at $340.00.
Prepayments on Q3 contracts covered more than 100% of the associated capex, versus 50% to 60% in Q2. Contracts closed above $25 million per megawatt, and payback shortened to one year and seven months. As Nebius CEO Arkady Volozh put it: “So our customers are paying more, they pay earlier, and they’re committing for longer.”
For 2027, management expects revenue of $12-13B, pre-tax breakeven in Q4 2027, and 75-85% of capex covered by prepayments and asset-backed financing. Northland benchmarks against CoreWeave (NASDAQ:CRWV), citing ACV/MW pricing and CoreWeave parity.
Price targets reflect analyst opinions. Post-report revisions may still arrive, and reaching even the average target requires the stock to more than double.
Neocloud Peers Fell Together, and Nebius Offers the Smallest Average-Target Upside
Nebius fell hardest over three months, but peers took similar one-month hits.
CoreWeave trades at $56.60 after a 27.26% one-month drop. Its average target of $125.46 implies 121.7% upside. Among 42 analysts, 8 rate it Strong Buy, 24 Buy, 7 Hold, 2 Sell and 1 Strong Sell. CoreWeave just raised full-year revenue guidance, a contrast with Nebius’s trim.
IREN (NASDAQ:IREN) trades at $19.48, down 44.02% in a month. Its $56.69 average target implies 191.0% upside, with 3 Strong Buy, 13 Buy and 4 Hold ratings. Its $4 billion ARR target also slipped on timing.
IREN carries the largest analyst-implied upside, and Nebius the smallest on average targets. Nebius’s appeal rests more on its Street-high case than on consensus.
Nebius Is Still Up 53.68% This Year After Halving
At $128.64, Nebius trades against a $278.05 average target from 22 analysts, implying 116.1% upside. The 52-week range runs from $73.52 to $299.86.
Shares are down 37.81% over one month yet up 53.68% year to date. The S&P 500 has gained 11.05% year to date.
Nebius Bull Case Hinges on Funding and Delivery
The bull case improves if prepayments keep covering capex and its owned sites in Alabama, Missouri, Finland and Pennsylvania deliver on schedule, putting the $12-13B 2027 revenue outlook within reach. The case weakens if colocation delays spread or financing markets tighten before a $40-45B build.
Three customers made up 24%, 21%, 14% of Q2 revenue, 7.6 million shares remain available under the ATM program, and GAAP profits are still a year away.
Contracted demand and customer-funded capex suggest the 50% decline may be excessive, though on-time delivery of owned capacity is the key test for the $410 case.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.