SanDisk Falters for 3 Months But One Top-Tier Institutional Desk Is Sure It’s Going to Nearly Triple
SanDisk has shed a third of its value in a month even as its business posts record numbers and locks in nearly $94 billion in signed customer contracts. One top analyst sees a near-triple from here, but the bull case…

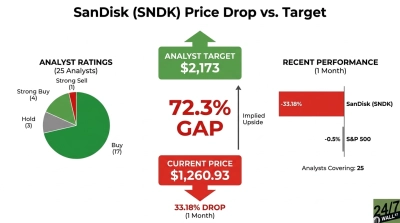
SanDisk (NASDAQ:SNDK | SNDK Price Prediction) currently trades at $1,260.93, while Wall Street’s average price target is $2,173. That gap works out to 72.3% implied upside.
SanDisk is the NAND flash pure-play that was spun out in February 2025. AI datacenter storage demand has made it one of the market’s biggest winners. Fiscal fourth-quarter revenue reached $8.96 billion, up 371.6% year over year, and non-GAAP EPS of $39.25 beat the $33.28 estimate.
The gap stands out because the stock has pulled back just as the business looks strongest. Melius Research analyst Ben Reitzes holds a Street-high target of $3,600, which implies 185.5% upside. That is close to triple the current price.
China Memory Fears and Profit-Taking Drag SanDisk Down 33% in a Month
The biggest blow came from reports that China’s ChangXin Memory Technologies had made progress on next-generation DRAM and server-grade DDR5 chips. That news triggered selling across memory stocks. SanDisk has lost 33.18% over the past month. It fell 8.51% in the latest session alone and now sits 46.4% below its 52-week high of $2,354.39.
SanDisk makes NAND, a separate product from DRAM, so ChangXin’s progress is a less direct threat. Other pressures piled on anyway: profit-taking after the 2026 rally, rising Treasury yields and concerns about debt-funded AI infrastructure spending. The company’s own numbers remain strong. SanDisk has beaten EPS estimates five straight quarters.
Analysts See $93.9 Billion in Contracts the Market Is Discounting
The bull case rests on SanDisk’s multi-year customer agreements, which the company calls NBMs. CFO Luis Visoso said signed NBMs carry total expected revenue of “a minimum of $93.9 billion, assuming floor pricing.” Those contracts are expected to cover more than 50% of bits in fiscal 2027 and approximately two-thirds in fiscal 2028, and they are backed by $16.5 billion in financial guarantees.
Melius builds its $3,600 target on three pillars: demand for High-Bandwidth Flash, tight NAND pricing and free cash flow strong enough to support up to $100 billion in buybacks over three years. Other desks sit close behind, with Bernstein at $3,000 and Cantor Fitzgerald at $2,900. The board has already added $14 billion in buyback authorization.
Recent updates have been positive. Mizuho maintained Outperform and raised its target to $2,050, and Rosenblatt initiated at Buy with a $2,400 target. The next test is the upcoming earnings report. Guidance calls for revenue of $10.30 billion to $10.80 billion and EPS of $44.00 to $46.00.
Price targets are opinions, though. The $3,600 call assumes pricing stays strong in a NAND market that management expects to grow 3x year over year in 2026.
Every Storage Name Sold Off, and SanDisk Fell Hardest
The whole storage group fell together. Over the past month, SanDisk dropped more than any of its peers.
Micron Technology (NASDAQ:MU) is down 20.09% over the past month. It trades at $856.49 versus a $1,560.57 target and offers 82.2% implied upside. Nine analysts rate it Strong Buy, 36 Buy, three Hold and one Strong Sell. That is more consensus upside than SanDisk.
Western Digital (NASDAQ:WDC), SanDisk’s former parent, has fallen 25.23% in a month. At $354.19 versus a $654 target, the implied upside is 84.6%, with four Strong Buy, 17 Buy and five Hold ratings.
Seagate Technology (NASDAQ:STX) is down 30.49% in a month. It trades at $642.14 versus a $1,116.58 target and offers 73.9% upside, which is similar to SanDisk.
On consensus targets, Western Digital has the most upside in the group, and SanDisk has the least. SanDisk’s case rests heavily on its outlier targets.
A 431% Year Still Survives the Slide
At $1,260.93, SanDisk would need to rise 72.3% to reach the $2,173 consensus. Here is how the 25 covering analysts rate the stock:
- Strong Buy: 4
- Buy: 17
- Hold: 3
- Strong Sell: 1
Even after the selloff, the stock is up 431.19% year to date, while the S&P 500 has gained 12.03%. Over the past month, SanDisk fell 33.18% while the index slipped 0.5%. The forward P/E is about 8.
Signed Revenue Tilts Me Bullish Before Earnings
My view on SanDisk becomes more constructive if the coming earnings report hits guidance and NBM coverage keeps growing. That would show signed pricing holding up in a falling market. My view becomes cautious if NAND pricing rolls over or AI capex budgets shrink. Floor-price contracts protect revenue, yet margins near 84.6% leave a long way to fall.
I lean bullish. A forward multiple near 8 with $93.9 billion in signed floor revenue reflects much of the bad news. Still, I’d treat the $3,600 target as a ceiling, and the consensus is the more realistic mark to measure against.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.