SanDisk Stock Is Back on Wall Street’s Radar. Here’s Where I See It Going
SanDisk just posted a record fiscal year yet sits nearly 50% below its 52-week high after a brutal month-long selloff. Whether that gap represents a rare opportunity or a warning sign depends entirely on one factor most analysts are overlooking.

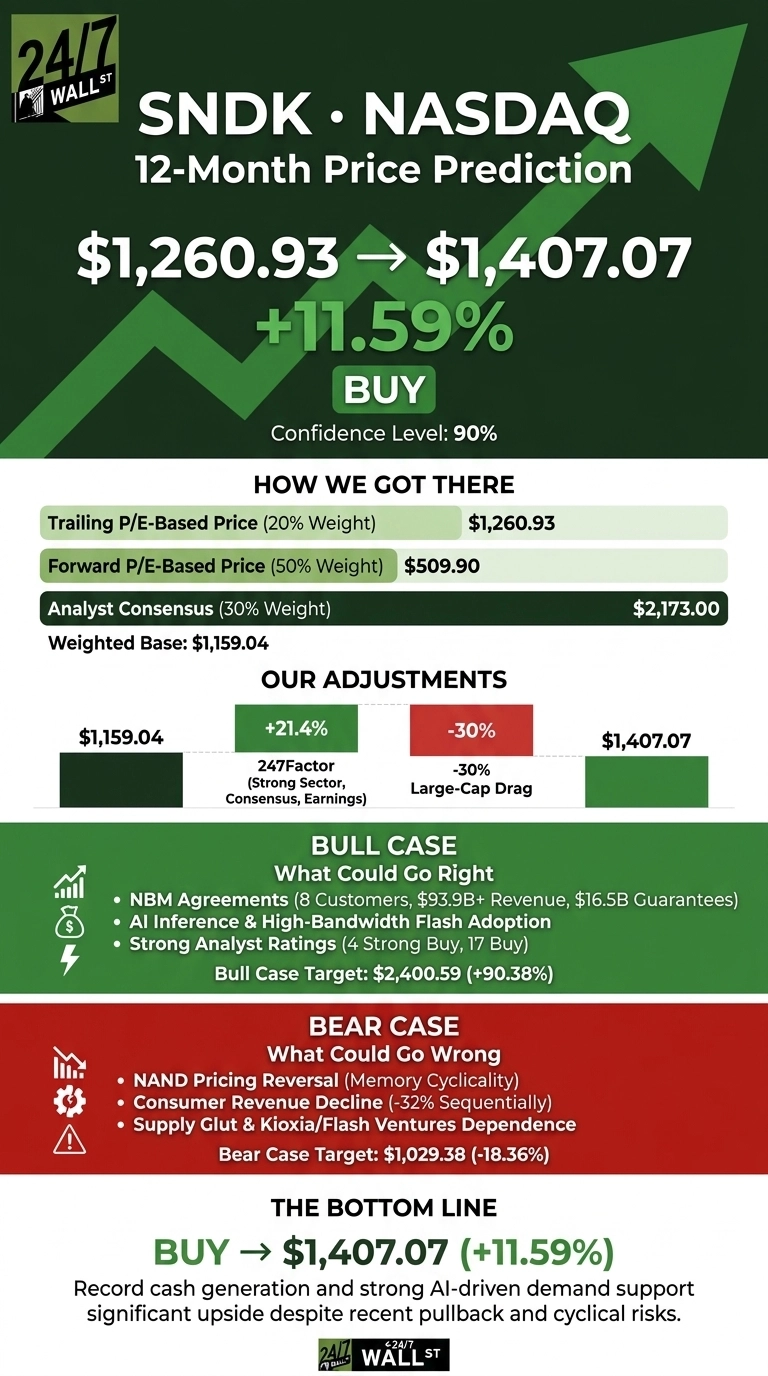
SanDisk (NASDAQ:SNDK | SNDK Price Prediction) trades at $1,260.93 after a sharp October sell-off. The 24/7 Wall St. price target stands at $1,407.07 over the next 12 months. That implies 11.59% upside, and we rate the stock a strong buy.
| Metric | Value |
|---|---|
| Current Price | $1,260.93 |
| Price Target from 24/7 Wall St. | $1,407.07 |
| Upside/Downside | 11.59% |
| Recommendation | BUY |
| Confidence Level | 90% |

SanDisk is generating record cash at very high margins, but the stock is priced as if the NAND cycle has already peaked. In our view, the pullback has gotten ahead of the fundamentals.
A 33% Monthly Slide Masks a Record Fiscal Year
SanDisk fell 9.47% over the past week and 33.09% over the past month. That leaves it about 46% below its 52-week high of $2,354.39. Shares are still up 431.92% year to date, and Barron’s listed SanDisk Friday among the stocks explaining today’s market.
Fiscal fourth-quarter revenue reached $8.965 billion, up 371.6% year over year. Non-GAAP EPS of $39.25 beat the $33.28 estimate, the fifth consecutive beat. For the first quarter of fiscal 2027, management forecast to revenue of $10.30 billion to $10.80 billion and EPS of $44 to $46. The board also authorized an additional $14 billion in buybacks.
Why Bulls See $2,400 Ahead
Visibility supports the upside thesis. SanDisk has signed New Business Model (NBM) agreements with 8 customers. At floor pricing, those deals carry a minimum of $93.9 billion in expected revenue, backed by $16.5 billion in financial guarantees. CEO David Goeckeler said customers are “giving us demand signals all the way out to the end of the decade.”
Analyst ratings stand at 4 Strong Buy, 17 Buy, 3 Hold and 1 Strong Sell. The consensus target implies about 72% upside. The bullish case reaches $2,400.59, a 90.38% gain, if pricing holds and high-bandwidth flash gains traction.

What Could Break the NAND Story
Memory is a cyclical business. About two-thirds of fourth-quarter sequential growth came from higher pricing, so new supply would hit earnings quickly. Consumer revenue fell 32% sequentially to $556 million.
SanDisk also depends heavily on Kioxia through the Flash Ventures joint venture. The bear case stands at $1,029.38, a decline of 18.36%.
As a counterpoint, the consumer drop partly reflects bits being shifted to Datacenter, which grew from about 12% of bits to 38%. Floor prices in the NBM contracts also limit how far pricing can fall.

How SanDisk Compares to Micron and Western Digital
Micron Technology (NASDAQ:MU) is the closest AI memory peer. Its fiscal fourth-quarter revenue rose 379.27% to $54.229 billion. Micron’s margin guidance is similar to SanDisk’s, yet its market value is far larger, which leaves SanDisk room to re-rate.
Western Digital (NASDAQ:WDC) is SanDisk’s former parent and now focuses on hard drives. It offers a useful contrast on the same AI storage demand.
Its fiscal first-quarter non-GAAP EPS of $4.64 beat the $4.0771 estimate, but its margins are well below SanDisk’s. Measured against both peers, our target looks reasonable and arguably conservative.
| Company | Next-Quarter Non-GAAP Gross Margin Guide | Market Cap |
|---|---|---|
| SanDisk | 83.0% to 85.0% | $183.41B |
| Micron | 86.25% | $980.92B |
| Western Digital | 60% to 61% | $129.69B |
Signed Visibility Could Power SanDisk’s Rebound
The 24/7 Wall St. price target is $1,407.07, with a buy rating and 90% confidence. Contracted visibility is the critical factor for me.
The upside thesis strengthens if NBM deals keep growing and first-quarter results land within guidance. The thesis weakens if NAND pricing falls over before signed volumes build up. At about 16x trailing earnings, the October drop leaves shares trading below our target.
SanDisk’s longer-term trading range appears below, assuming current growth trends and market conditions hold.
| Year | Bear | Price Target from 24/7 Wall St. | Bull |
|---|---|---|---|
| 2026 | $1,212.39 | $1,293.03 | $1,390.90 |
| 2027 | $1,076.94 | $1,412.83 | $2,131.85 |
| 2028 | $983.36 | $1,523.16 | $3,211.19 |
| 2029 | $966.80 | $1,661.59 | $4,081.09 |
| 2030 | $969.18 | $1,763.78 | $4,815.42 |
They rest on SanDisk continuing to execute on its NBM agreements and its BiCS technology roadmap. Adoption of high-bandwidth flash could push results above these figures, while a NAND supply glut would move them toward the bear column.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.