Rocket Lab Is Playing a Much Bigger Game Than Rocket Launches
Rocket Lab's stock has cratered nearly 30% in a month, yet its backlog just surged 137% year over year and analysts see over 100% upside from here. The question is whether a cracked rocket tank just derailed the whole story.

Our 24/7 Wall St. price target for Rocket Lab (NASDAQ:RKLB | RKLB Price Prediction) is $68.07 over the next 12 months. That is 35.06% above the current price of $50.40. Our model rates the stock a buy with moderate confidence.
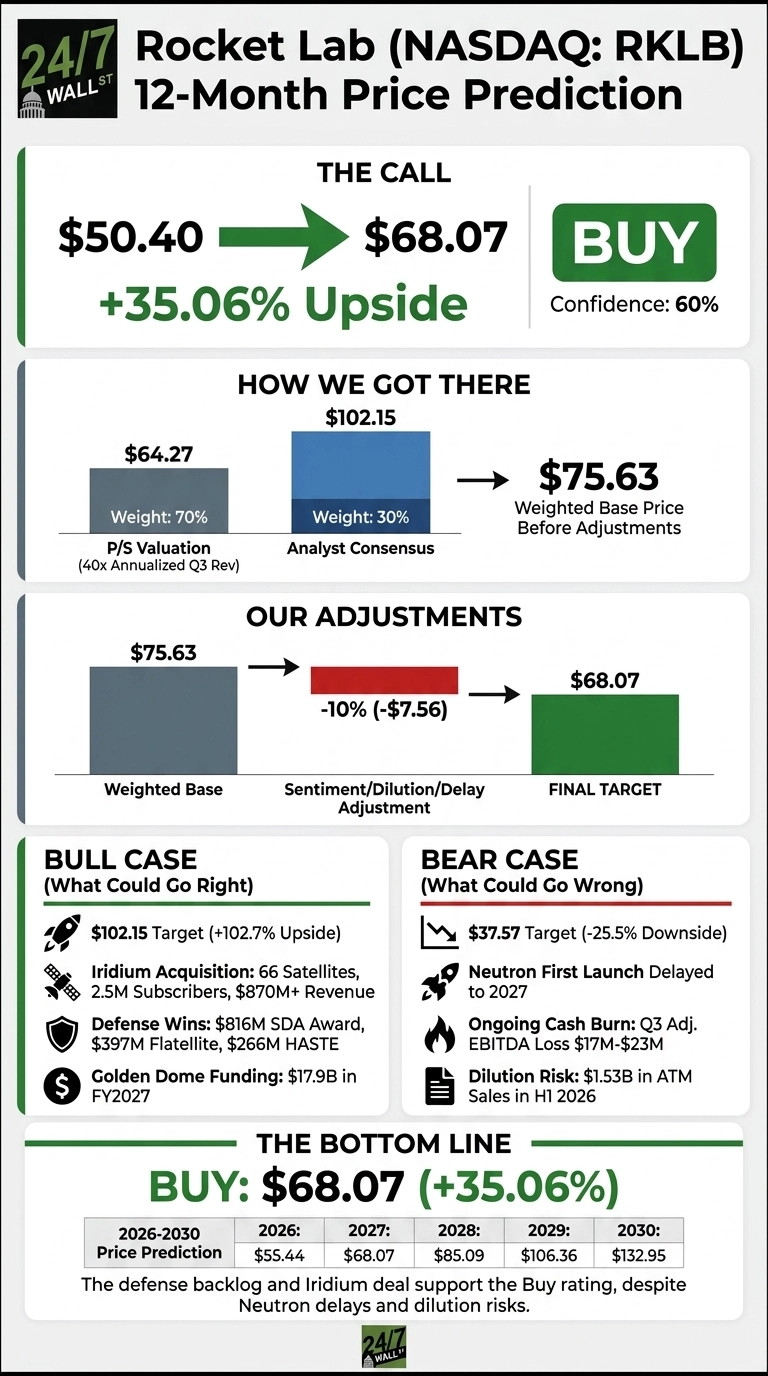
| Metric | Value |
|---|---|
| Current Price | $50.40 |
| 24/7 Wall St. Price Target | $68.07 |
| Upside/Downside | 35.06% |
| Recommendation | BUY |
| Confidence Level | 60% |

The market is pricing Rocket Lab as a launch company with a delayed rocket. Rather, it is a defense-heavy space prime building out its own communications network.
Backlog reached $2.36B (+137% YoY), and the Iridium Communications (NASDAQ:IRDM) deal adds recurring service revenue. Dilution and Neutron execution are the reasons my confidence stops at 60%.
Neutron Delay Sparks a Sharp Sell-Off in Rocket Lab Shares
Shares are down 8.78% over the past week, 29.98% over the past month and 27.75% year to date. That leaves them 66.6% below the $151 52-week high.
On October 14, Rocket Lab pushed Neutron’s first launch to 2027 after finding a defect in its carbon-composite tank. That same week, investors began to worry about FCC scrutiny of the Iridium deal, even though Iridium stockholders approved the acquisition on September 24.
In Q2, revenue of $234.07M rose 62% and beat estimates. GAAP EPS of -$0.08 missed the -$0.0767 consensus, partly because of $8.58M in acquisition costs.

Bulls See a Path Back to $102
Iridium brings 66 satellites, more than 2.5 million subscribers and more than $870 million in annual revenue. CEO Peter Beck calls the deal “a starting point for an applications play, not the endpoint.” The defense business keeps winning work.
Rocket Lab holds an $816M SDA Tracking Layer award, a $397M Flatellite contract and a $266 million Space Force HASTE deal. Meanwhile, Golden Dome is set to receive $17.9 billion in FY2027.
Analysts rate the stock 16 buys, 4 holds and no sells. My bull case is the $102.15 consensus target, which means 102.7% upside.

Dilution and Delays Could Drag Shares Toward $37
Neutron was first scheduled to fly in 2024. Q2 brought a net loss of $49.26M, and management guided Q3 adjusted EBITDA to a wider loss of $17M-$23M.
On the downside, shares return to the $37.57 52-week low, a 25.5% decline. As a counterpoint, much of the cash burn went into building Neutron inventory ahead of demand. Non-GAAP gross margin also expanded to 41.5% from 36.9%.

How Rocket Lab Compares to Lockheed Martin and AST SpaceMobile
| Company | Market Cap/Sales | Latest Revenue Growth |
|---|---|---|
| Rocket Lab | 39x TTM | 62.0% |
| Lockheed Martin | 1.7x 2026 guide | 11.3% |
| AST SpaceMobile | 64x 2026 guide | N/A |
Lockheed Martin (NYSE:LMT) vies with Rocket Lab for missile-defense and national security space work. It carries a $292 billion backlog, but its Space division grew only 4%. That slower growth helps explain why Rocket Lab commands a premium multiple.
AST SpaceMobile (NASDAQ:ASTS) is a space-connectivity growth story still before commercial service. Q2 revenue of $31.52M missed estimates, yet it trades at a higher multiple of expected sales. Taken together, the two peers make our 24/7 Wall St. price target look reasonable, even somewhat conservative.
Rocket Lab Price Prediction 2026-2030
I’m staying with a buy rating, a 24/7 Wall St. price target of $68.07 and 60% confidence. The deciding factor is defense backlog that converts into revenue. Management expects about 45.5% of the backlog to become revenue within 12 months.
The bull case improves if Neutron reaches stage testing in early 2027 and Iridium passes regulators. The bear case gains weight if Rocket Lab announces new equity raises before Neutron flies.
These longer-range 24/7 Wall St. price target figures assume Rocket Lab keeps growing at its current pace and market conditions hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $55.44 |
| 2027 | $68.07 |
| 2028 | $85.09 |
| 2029 | $106.36 |
| 2030 | $132.95 |
The forecast depends on Rocket Lab keeping up its current strategy. A successful Neutron ramp could lift these numbers well above our forecast. Further delays or regulatory trouble with Iridium could push them well below it.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.