The Space Stock With a Much Bigger Opportunity Than Launches
Rocket Lab's rockets grab the headlines, but a quieter division is already generating four times the revenue of launches and positioning the company for a deal that could reshape the entire space economy.


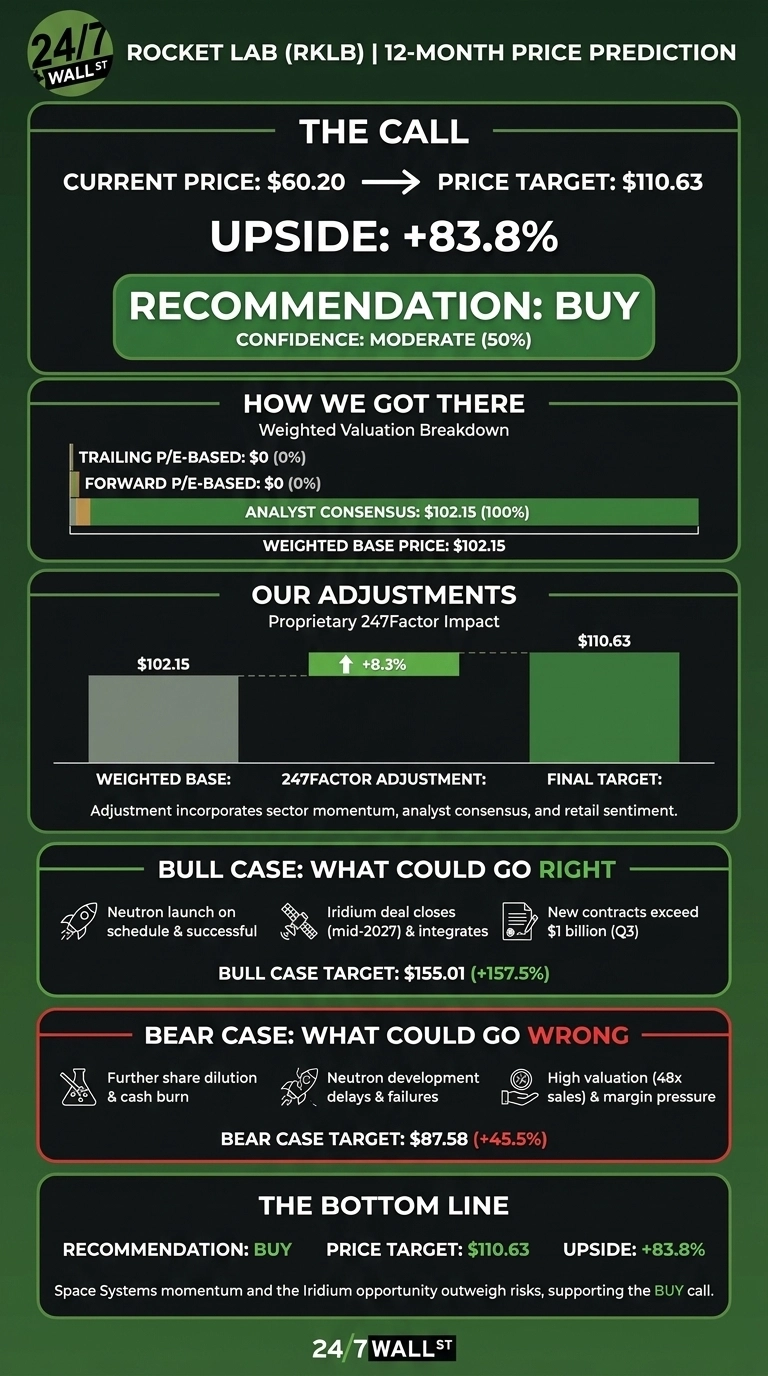
Rocket Lab (NASDAQ:RKLB | RKLB Price Prediction) makes most of its revenue from what rides on top of the rocket. The 24/7 Wall St. price target for Rocket Lab is $110.63 over the next 12 months.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $60.20 |
| The Price Target from 24/7 Wall St. | $110.63 |
| Upside/Downside | 83.8% |
| Recommendation | BUY |
| Confidence Level | 50% |
The stock makes a buy rating in our model. Confidence is moderate, which matches a stock with a 2.94 beta and a 52-week range of $37.57 to $151.
Most of the upside rests on Space Systems, which already brings in most of the revenue, and on the pending Iridium Communications (NASDAQ:IRDM) deal, which would add recurring communications income.
Record Revenue Meets a Whipsawing Share Price
Shares rose 12.17% over the past week. The shares remain down 16.61% over the past month and 13.7% year to date. That puts the stock about 60% below its 52-week high and about 60% off its low.
The business kept growing. Q2 revenue came in at $234.07 million, up 62% from a year earlier and ahead of the $230.94 million consensus. GAAP EPS of -$0.08 missed the -$0.0767 estimate, but that figure includes $8.58 million in acquisition costs.
Space Systems brought in $189.5 million, compared with $44.6 million from launch. Backlog hit a record $2.36 billion. Iridium stockholders approved the deal on September 24, 2026. Q3 results are expected around November 9, against revenue guidance of $250 million to $265 million.
A proprietary model generates the 24/7 Wall St. Price Target. It combines trailing P/E, forward P/E and the analyst consensus target, then adjusts the result with our 247Factor. Rocket Lab still reports GAAP losses, so the earnings-based inputs get zero weight.
That leaves the model fully grounded to the $102.15 consensus target, which rests on 4 Strong Buy, 12 Buy and 4 Hold ratings and no Sells.

Why Bulls See $155 on the Horizon
CEO Peter Beck describes the space economy as three businesses: launch, hardware and applications. “With Iridium, Rocket Lab will have all three of these verticals,” he said.
Iridium adds 66 satellites, more than 2.5 million subscribers and over $870 million in annual revenue. The deal is expected to close in mid-2027.
Defense contracts add depth. They include a $397 million Flatellite award from the Space Force, more than $160 million to build three geostationary satellites and over $1 billion in new Q3 contracts.
Management expects Neutron’s first successful flight to turn adjusted EBITDA positive in the following quarter. Our bull case reaches $155.01, a 157.5% gain.

Dilution and Neutron Delays Top the Risk List
Rocket Lab lost $198 million in FY25 and raised $1.53 billion through at-the-market stock sales in the first half of 2026. Neutron already slipped once after a tank test failure. Q3 non-GAAP gross margin guidance of 35% to 37% is below Q2’s 41.5%. At 48 times sales, the stock leaves little room for mistakes.
On the other side, much of that spending funds growth. Cash stands at $2.13 billion, and the adjusted EBITDA loss narrowed to $8.8 million from $27.6 million. Our bear case of $87.58 is still 45.5% above today’s price.
How Rocket Lab Compares to Planet Labs and AST SpaceMobile
Planet Labs (NYSE:PL) is the closest space-applications peer because it sells satellite data. Its quarterly revenue grew 58.1% from a year earlier, close to Rocket Lab’s rate, yet it trades at only 13.78 times sales. Rocket Lab’s premium reflects its vertical integration and backlog.
AST SpaceMobile (NASDAQ:ASTS) overlaps directly with the Iridium thesis through space-based cellular service. It trades at 141.63 times sales on $115.3 million in trailing revenue.
| Company | Price-to-Sales | EV-to-Revenue |
|---|---|---|
| Rocket Lab | 48.47 | 41.92 |
| Planet Labs | 13.78 | 12.97 |
| AST SpaceMobile | 141.63 | 108.69 |
Rocket Lab sits in the middle of this group, which makes the 24/7 Wall St. price target look reasonable.
Space Systems Momentum Tips the Scale
The 24/7 Wall St. price target of $110.63 comes with a buy rating at 50% confidence. What tips the scale for me is a Space Systems business that is already much bigger than launch.
I’d grow more confident if Neutron reaches the pad on schedule and Iridium closes smoothly. I’d turn cautious if Neutron slips again or share dilution picks up. For now, I think the model’s upside case holds up.
Here is where our model projects Rocket Lab could trade if its current growth and today’s market conditions hold.
| Year | The Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $65.63 |
| 2027 | $114.67 |
| 2028 | $167.88 |
| 2029 | $251.26 |
| 2030 | $287.19 |
These projections assume Rocket Lab keeps following its current strategy. Neutron’s launch pace and how well Iridium is integrated are the main key factors.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.