Prediction: Rocket Lab Could Be Building the Space Company of the Future
Rocket Lab is merging rockets, satellites, and defense contracts into one company while its stock trades near a 52-week low. Whether that gap is a warning sign or a rare entry point depends on one unproven rocket.

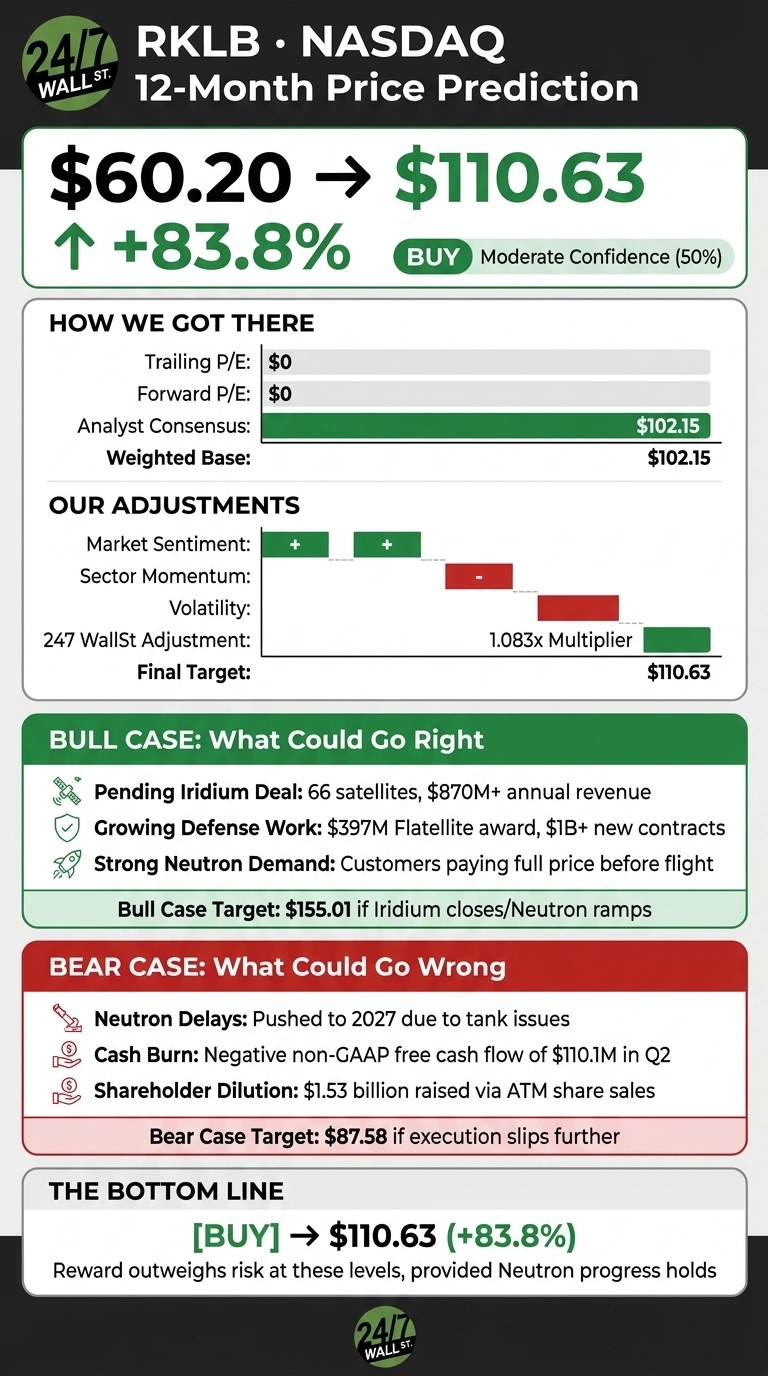
Shares of Rocket Lab (NASDAQ:RKLB | RKLB Price Prediction) trade at $60.20 this morning. The 24/7 Wall St. price target is $110.63 over the next 12 months, which means 83.8% upside. The model gives the stock a buy with moderate confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $60.20 |
| Price Target from 24/7 Wall St. | $110.63 |
| Upside/Downside | 83.8% |
| Recommendation | BUY |
| Confidence Level | 50% |

Rocket Lab is pulling launch, spacecraft, components and soon satellite communications into one company.
The stock is down 13.7% year to date even as revenue keeps growing, so the market is pricing in a discount for execution risk. Our model takes that gap as upside potential, as long as Rocket Lab keeps delivering.
Neutron Delay Knocked Shares Down Before a Sharp Rebound
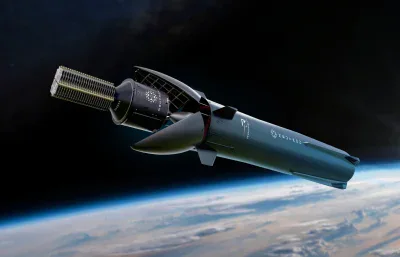
On October 14, Rocket Lab pushed Neutron’s first launch into 2027. The cause was voids in a carbon-composite tank dome. Shares are down 16.61% over the past month but up 12.17% over the past week. The 52-week range runs from $37.57 to $151.
In Q2, revenue came in at $234.07 million, beating the $230.94 million estimate and rising 62% from a year earlier. GAAP EPS of -$0.08 missed the -$0.0767 estimate, though that figure includes $8.58 million in acquisition costs. Backlog hit a record $2.36 billion, and Q3 revenue guidance is $250 million to $265 million.

Why Bulls See $155 on the Horizon
The pending Iridium (NASDAQ:IRDM) deal would bring in 66 satellites, more than 2.5 million subscribers and over $870 million in annual revenue. Closing is expected in mid-2027.
Defense work is also growing: a $397 million Flatellite award, plus more than $1 billion in new contracts already signed in Q3. Customers are also paying full price for Neutron slots before its first flight, at a $50 million to $55 million average selling price.
Of 20 covering analysts, 16 rate the stock a buy or strong buy. Our bull case reaches $155.01.

Execution Risks That Could Cap the Upside
Neutron has now slipped more than once. Rocket Lab also raised $1.53 billion through its at-the-market (ATM) share sales in the first half, diluting shareholders. Non-GAAP free cash flow was negative $110.1 million in Q2.
The adjusted EBITDA loss narrowed to $8.8 million from $27.6 million a year earlier. The ATM program has been ended, and cash stands at $2.13 billion. The CFO said the first successful Neutron flight should bring “adjusted EBITDA positivity in the following quarter.” The bear case sits at $87.58.
Rocket Lab Commands a Steep Premium to Planet Labs and Lockheed Martin
Planet Labs (NYSE:PL) is the closest small-cap peer, since it also serves government and defense customers with its own satellite fleet. Revenue grew 58.14% last quarter, about as fast as Rocket Lab’s, yet Planet trades at a much lower sales multiple.
Lockheed Martin (NYSE:LMT) shows what a mature space prime is worth. It trades at a forward P/E of 19 and carries a $292 billion backlog, but its revenue grows far more slowly.
| Company | Price-to-Sales | Latest Quarterly Revenue Growth |
|---|---|---|
| Rocket Lab | 48.72x | 62.0% |
| Planet Labs | 13.78x | 58.14% |
| Lockheed Martin | 1.839x | 11.3% |
On sales multiples alone, the 24/7 Wall St. price target looks aggressive. It looks more reasonable once you factor in Rocket Lab’s full range of businesses, from launch to spacecraft to services.

Neutron Progress Tips Our Verdict Toward Buy
Our 24/7 Wall St. price target of $110.63 supports a buy rating at 50% confidence. The deciding factor is a backlog that keeps growing while the share price falls.
The bull case strengthens if Neutron’s tank fix holds and stage testing goes smoothly. The case weakens if the first launch slips past 2027 or Iridium hits regulatory problems. At these levels, our model sees the potential reward outweighing the risk.
Rocket Lab Price Prediction 2026-2030
Each figure below is the 12-month-forward target our model projects from October of that year, assuming current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $110.63 |
| 2027 | $167.88 |
| 2028 | $251.26 |
| 2029 | $287.19 |
| 2030 | $342.24 |
These projections assume Rocket Lab sticks to its current plan. A successful Neutron ramp or a smooth Iridium integration could push results well above these figures, while further delays could pull them well below.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.