RKLB Stock’s Next Big Breakthrough Could Change Its Long-Term Growth Outlook
Rocket Lab's backlog just hit a record and revenue is surging, yet the stock sits near its yearly lows while one unflown rocket holds the power to revalue the entire company overnight.


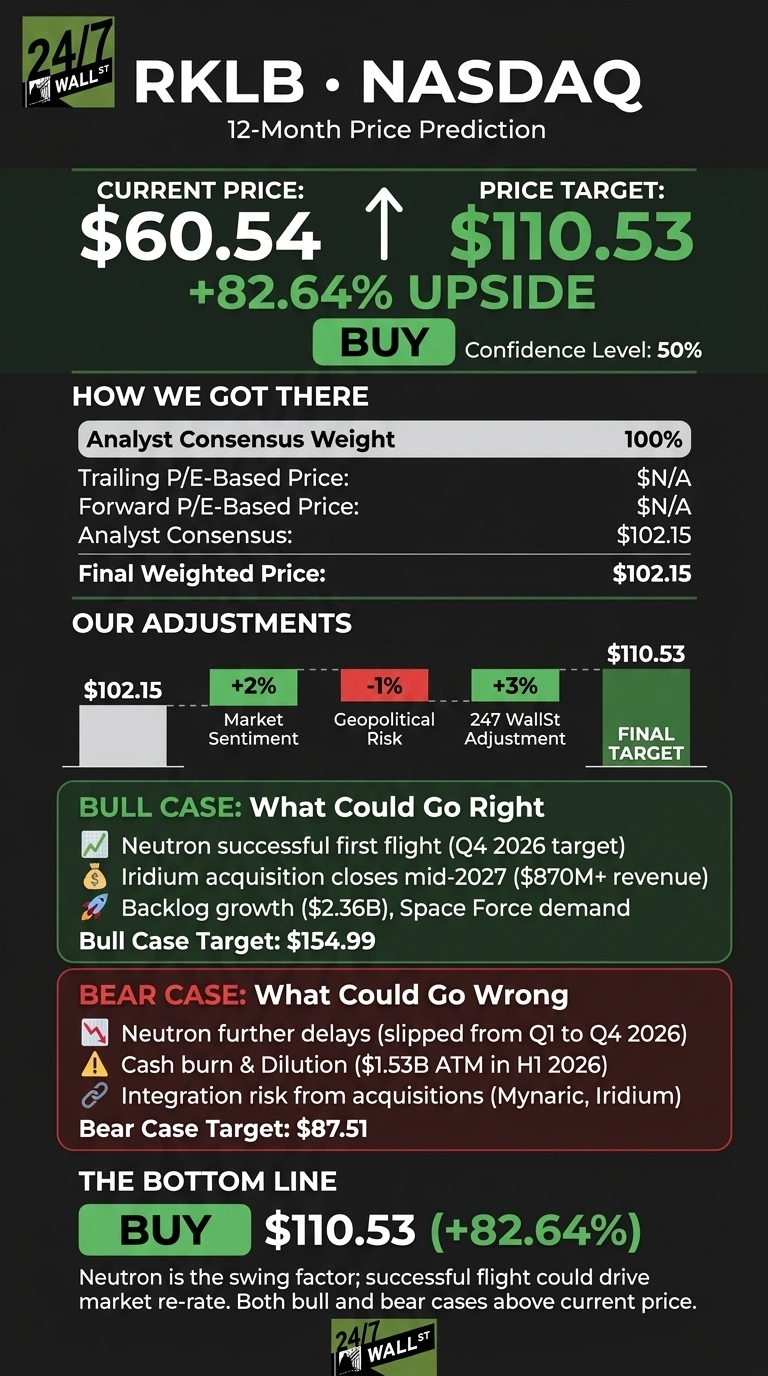
Neutron is the swing factor for Rocket Lab (NASDAQ:RKLB | RKLB Price Prediction). Shares trade at $60.54. The 24/7 Wall St. price target of $110.53 over the next 12 months means 82.64% upside. The stock receives a buy rating with moderate confidence from our model.
| Metric | Value |
|---|---|
| Current Price | $60.54 |
| Price Target from 24/7 Wall St. | $110.53 |
| Upside/Downside | 82.64% |
| Recommendation | BUY |
| Confidence Level | 50% |

A 50% confidence reading matches a stock with a 2.938 beta and a medium-lift rocket that has yet to fly.
The stock also trades well below the $102.15 analyst consensus, even though backlog stands at a record. In my view, a successful first Neutron flight would push the market to re-rate the whole business.
Record Revenue Collides With a Sliding Share Price
Shares rose 12.8% over the past week. The shares remain down 16.14% over the past month and 13.22% year to date, and they trade between a 52-week low of $37.57 and a high of $151.
The business tells a better story. Q2 revenue came in at $234.07 million, up 62% and ahead of the $230.94 million consensus. GAAP EPS of -$0.08 missed the -$0.0767 estimate, and $8.58 million in acquisition costs weighed on that number.
Backlog rose 137% to $2.36 billion, and the pending Iridium Communications (NASDAQ:IRDM) deal is expected to close in mid-2027.
Why Bulls See $155 if Neutron Flies
Neutron came to market at a $50 million to $55 million average selling price. Chief Executive Peter Beck said on the August call: “Pre-test flight or post-test flight, Neutron demand is not a concern.” Adjusted EBITDA is also expected to turn positive in the quarter after the first successful flight.
Defense spending adds support: Rocket Lab holds an $816 million SDA tracking contract and a $397 million Flatellite award, and the FY 2027 budget requests $59.7 billion for space. Iridium would add more than $870 million in annual revenue. Our bull case hits $154.99.

Execution Risks That Could Delay the Payoff
Neutron’s first launch already slipped from Q1 2026 to Q4 2026 after a stage 1 tank test failure. Beck has said the year-end window is narrowing. Dilution adds pressure: $1.53 billion in at-the-market proceeds in the first half of the year.
Q3 guidance calls for an adjusted EBITDA loss of $17 million to $23 million. Bulls would point out that Mynaric’s supply-chain recovery explains part of the margin dip, and that $2.13 billion in cash funds the Neutron ramp. The bear case of $87.51 still stands above today’s price.

How Rocket Lab Stacks Up Against AST SpaceMobile and Planet Labs
AST SpaceMobile (NASDAQ:ASTS) builds and deploys its own satellite constellation, so it is the closest comparison for Rocket Lab’s Iridium push. Its Q2 revenue was just $31.52 million on a $13.26 billion market cap. Rocket Lab’s premium is supported by a revenue base that is already producing results.
Planet Labs (NYSE:PL) shares Rocket Lab’s government and defense customers. It grew revenue 58.14% and posted $13.93 million in adjusted EBITDA, a profitability benchmark Rocket Lab has yet to hit. Taken together, the peers make our target look reasonable.
| Company | Market Cap | Latest Quarterly Revenue | Backlog |
|---|---|---|---|
| Rocket Lab | $36.14B | $234.07M | $2.36B |
| AST SpaceMobile | $13.26B | $31.52M | $1.30B |
| Planet Labs | $4.94B | $116.05M | $906M+ |
Neutron Tips the Scale Toward Upside
Our 24/7 Wall St. price target of $110.53 has a buy rating at 50% confidence. The deciding factor is Neutron hits the pad.
I would grow more constructive once stage testing finishes successfully. I would turn conservative if the first flight slips well into 2027 and forces another equity raise. On balance, both our bull and bear cases sit above today’s price.
Looking further ahead, here is where our model projects Rocket Lab would trade should growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $66.60 |
| 2027 | $110.53 |
| 2028 | $164.13 |
| 2029 | $229.93 |
| 2030 | $263.72 |
These projections assume Rocket Lab keeps delivering on its present plan. A fast Neutron ramp to flight 10 and the Iridium close could push results well above this path. Further delays could push them well below it.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.