Tesla’s Profit Fell 43% and the Stock Held Up. Here’s Why
Tesla just reported one of its worst profit drops in years, yet investors barely flinched. The real story is buried below the headline number, and it changes what the stock is actually pricing in.


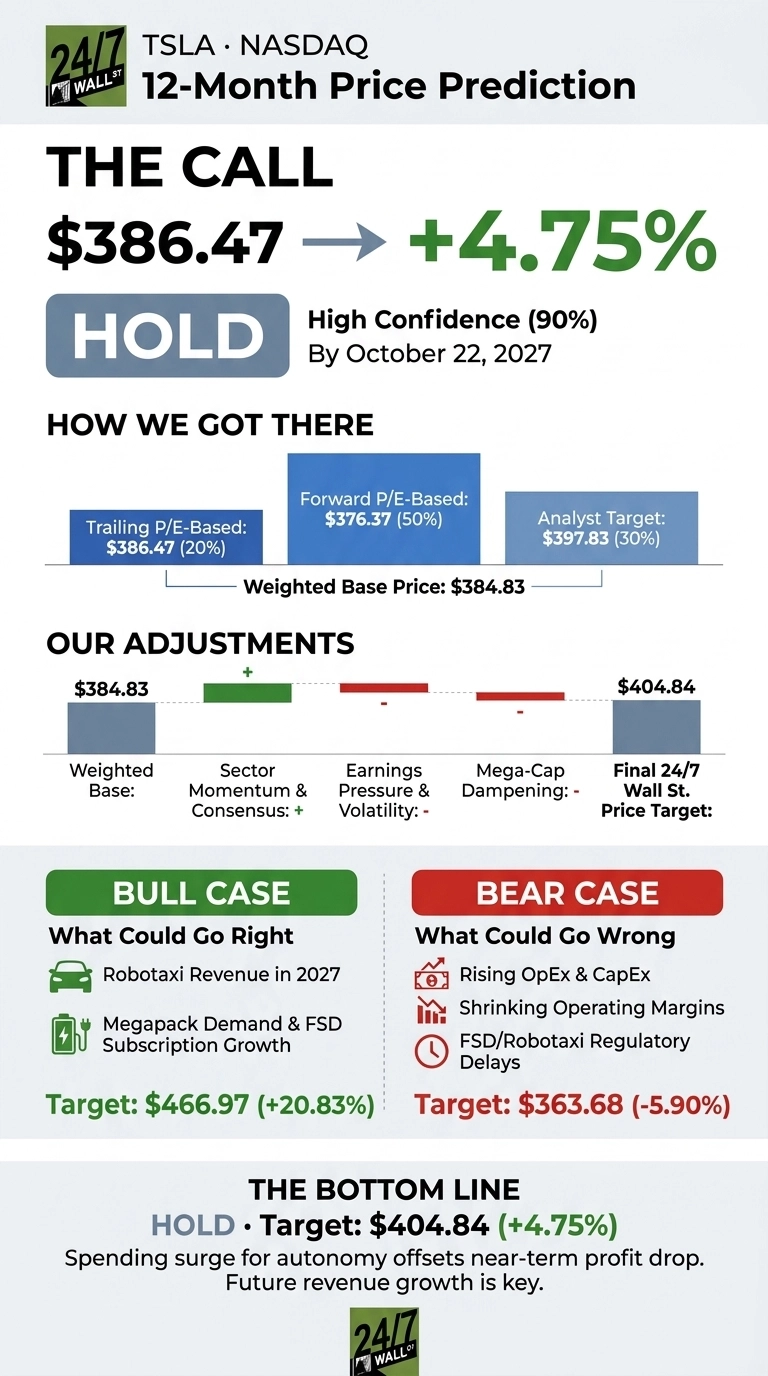
Tesla (NASDAQ:TSLA | TSLA Price Prediction) closed at $386.47 the day it reported a steep drop in profit. The 24/7 Wall St. price target for Tesla is $404.84 over the next 12 months. That means 4.75% upside and a hold rating. We have high confidence in the call.
| Metric | Value |
|---|---|
| Current Price | $386.47 |
| Price Target from 24/7 Wall St. | $404.84 |
| Upside/Downside | 4.75% |
| Recommendation | HOLD |
| Confidence Level | 90% |

Third-quarter net income fell 42.68% to $787 million, and shares slid only 0.91% on earnings day. The stock held up because the damage was below the gross profit line.
Gross profit rose 8.71%, while R&D climbed to $2.76 billion from $1.63 billion to fund autonomy, Optimus and AI computing power. Adjusted EPS of $0.48 beat the $0.4511 consensus.
A Calm Reaction After July’s 14.52% Selloff
Compare that with the second quarter, when an EPS miss sent shares down 14.52% in one session. Tesla traded at $382.90 midday. That leaves it up 4.29% over the past week and 2.03% over the past month, but down 14.86% year to date. It sits between a 52-week high of $498.83 and a low of $297.38.
Revenue of $28.046 billion came in essentially flat year over year. Deliveries reached 486,532, and Tesla ended the quarter with its highest backlog in four years.
Management also cut full-year capex guidance to about $20 billion. Meanwhile, Elon Musk suggested at a tie-up with SpaceX, which keeps merger speculation alive.

Robotaxi, Optimus and Megapack Fuel the Case for $466.97
Paid FSD subscriptions reached 1.74 million, up from 1.04 million. More than 75% of North American deliveries came with an FSD sign-up. The Cybercab fleet in Austin has grown tenfold since launch, and executives see Robotaxi becoming a significant profit contributor in 2027.
Megapacks are almost sold out for 2027. Energy gross margin also rose from 20.4% to 33.1%. Of the analysts covering Tesla, 19 rate the stock a buy or better. The bull case reaches $466.97, a 20.83% gain.

Spending Strain Could Push Shares Toward $363.68
Operating income dropped 55.79%. Capex rose 110.5%, which cut free cash flow to $1.531 billion. Management expects operating expenses to keep rising until the new products are launched. Part of the energy margin gain came from tariff refunds and warranty true-downs, which may not repeat.
On the other side, operating cash flow held at $6.263 billion and cash grew to $45.447 billion, so this looks like heavy investment funded from a strong balance sheet. The bear case is $363.68.
Tesla Trades at 159x Forward Earnings While GM Sits at 6x
General Motors (NYSE:GM) is the clearest example of how the market values a legacy automaker. Its forward P/E is 6x and its price-to-sales ratio is 0.36. That gap shows how much autonomy value is already priced into Tesla.
Rivian Automotive (NASDAQ:RIVN), a U.S. EV rival, posted a TTM profit margin of -55% and still trades at 3.059x sales. Tesla, by contrast, is profitable and holds net cash. Against these peers, our modest 24/7 Wall St. price target looks reasonable.
| Company | Forward P/E | Price-to-Sales |
|---|---|---|
| Tesla | 159x | 14.73x |
| General Motors | 6x | 0.36x |
| Rivian | N/A | 3.059x |
Tesla Price Prediction 2026-2030
I rate Tesla a hold with a 24/7 Wall St. price target of $404.84 and high confidence. What tips the scale is that rising gross profit and steady cash flow offset the spending surge.
I would turn more positive if Robotaxi revenue shows up in 2027 numbers. I would stay patient if operating margins keep shrinking without commercial launches to justify the cost.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $404.84 |
| 2027 | $425.19 |
| 2028 | $445.98 |
| 2029 | $467.79 |
| 2030 | $490.58 |
The projections rest on Tesla continuing to carry out its current strategy. A faster Robotaxi launch or a SpaceX combination could push results well above this path. Regulatory delays could drag results lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.