Tesla Stock Could Rebound as These 3 Growth Drivers Take Center Stage
Tesla bounced hard off its lows, but the car business is no longer the story investors care about. Three separate growth engines are starting to fire at once, and each one carries the potential to reshape the stock's valuation entirely.


Tesla (NASDAQ:TSLA | TSLA Price Prediction) shares are bouncing back after a solid third quarter, and the three businesses that could push the stock higher now matter more than the car business alone.
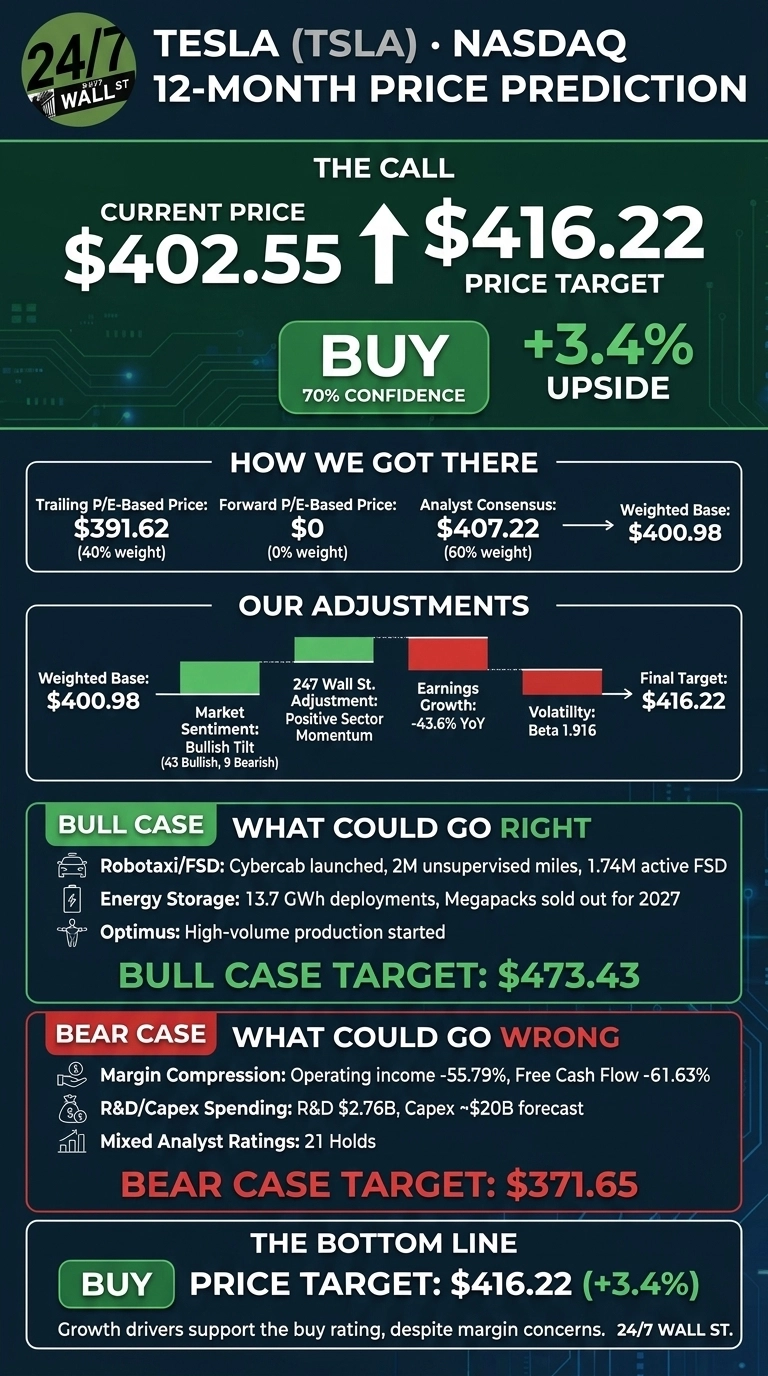
The 24/7 Wall St. price target for Tesla is $416.22, which points to 3.4% upside from the current price of $402.55. The stock has a buy rating, a view we hold with moderate-to-high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $402.55 |
| Price Target from 24/7 Wall St. | $416.22 |
| Upside/Downside | 3.4% |
| Recommendation | BUY |
| Confidence Level | 70% |

The recovery story rests on three drivers: Robotaxi and Full Self-Driving (FSD), Megapack energy storage, and the Optimus humanoid robot. All three moved forward in the quarter, and the stock is starting to price that in.
Q3 Beat and a Barclays Upgrade Fuel a Sharp Weekly Rally
Tesla is up 9.37% over the past week and 8.18% over the past month. It is still down 10.49% year to date. The shares sit 19.3% below their 52-week high of $498.83 and 35.4% above the low of $297.38.
In Q3, revenue came in at $28.05 billion, in line with estimates. Non-GAAP EPS of $0.48 beat the $0.4511 consensus. On Monday, Barclays upgraded Tesla to Buy from Hold, and that added fuel to the rally.

Three Growth Drivers Behind a $473 Bull Case
- Robotaxi and FSD: Cybercab joined the unsupervised Austin fleet on Sept. 3, 2026. Unsupervised miles grew 8x to nearly 2 million, and active FSD subscriptions reached 1.74 million, up from 1.04 million. CEO Elon Musk said Robotaxi revenue should become “noticeable probably in Q2” next year.
- Energy storage: Deployments reached 13.7 GWh, and energy gross margin rose to 33.1% from 20.4%. Musk said Tesla is “almost sold out of all Megapacks for 2027.”
- Optimus: Early production has started on a high-volume line in Fremont, and Tesla expects to deliver robots to outside companies around the end of next year.
If all three ramp on schedule, our bull scenario reaches $473.43.

Margin Compression Is the Risk Worth Watching
Operating income fell 55.79% to $718 million, and free cash flow dropped 61.63%. Some of the energy margin gain came from tariff refunds and warranty true-downs that may not repeat. Ratings remain mixed, with 21 Holds.
In our bear scenario, the stock falls to $371.65. In fairness, R&D rose to $2.76 billion because of deliberate spending on autonomy and Optimus. Gross profit also grew 8.71%, and cash reached $45.45 billion.
Tesla Trades at a Steep Premium to GM, NVIDIA, and Rivian
General Motors (NYSE:GM) competes with Tesla directly on U.S. vehicles. It trades at a forward P/E of 5x, compared with 133x for Tesla, so investors are clearly paying Tesla for autonomy rather than car sales.
NVIDIA (NASDAQ:NVDA) is the AI computing power benchmark. Its forward multiple of 13x comes with an operating margin of 66.2%.
Rivian (NASDAQ:RIVN) is still unprofitable, with EPS of -$2.58, which shows how valuable Tesla’s profitability is among pure-play EV makers.
| Company | Forward P/E | 1-Year Return |
|---|---|---|
| Tesla | 133x | -13.4% |
| GM | 5x | 10.9% |
| NVIDIA | 13x | 13.1% |
| Rivian | N/A | -14.8% |
Our target assumes Tesla’s multiple stays roughly where it is rather than expanding. Against this peer group, that makes the target look reasonable to slightly conservative.
Our Model Says Buy, and Robotaxi Decides How Far It Runs
The 24/7 Wall St. price target is $416.22, with a buy rating and 70% confidence. The speed at which Robotaxi turns into revenue is what matters most.
Shares could rise if Robotaxi revenue shows up by mid-2027 as management expects. Downside risk builds if margins keep shrinking while capex rose toward the roughly $20 billion forecast for this year. As things stand, the growth drivers support the model’s buy rating.
Here is where our model projects Tesla could trade further out, assuming current conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $410.25 |
| 2027 | $416.22 |
| 2028 | $432.23 |
| 2029 | $446.72 |
| 2030 | $488.35 |
These projections assume Tesla keeps executing on its current strategy. Robotaxi regulatory approvals or Optimus scaling could move the numbers significantly up or down.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.