Palantir’s Revenue Growth Could Set the Stage for Its Next Big Stock Move
Palantir just posted the fastest revenue growth in its history, sending shares back toward all-time highs, but a jaw-dropping valuation multiple means one stumble could unwind the entire rally.

Palantir Technologies (NASDAQ:PLTR | PLTR Price Prediction) has reported the fastest revenue growth in its history. What investors need to know now is how much of that speed is already priced into the shares.
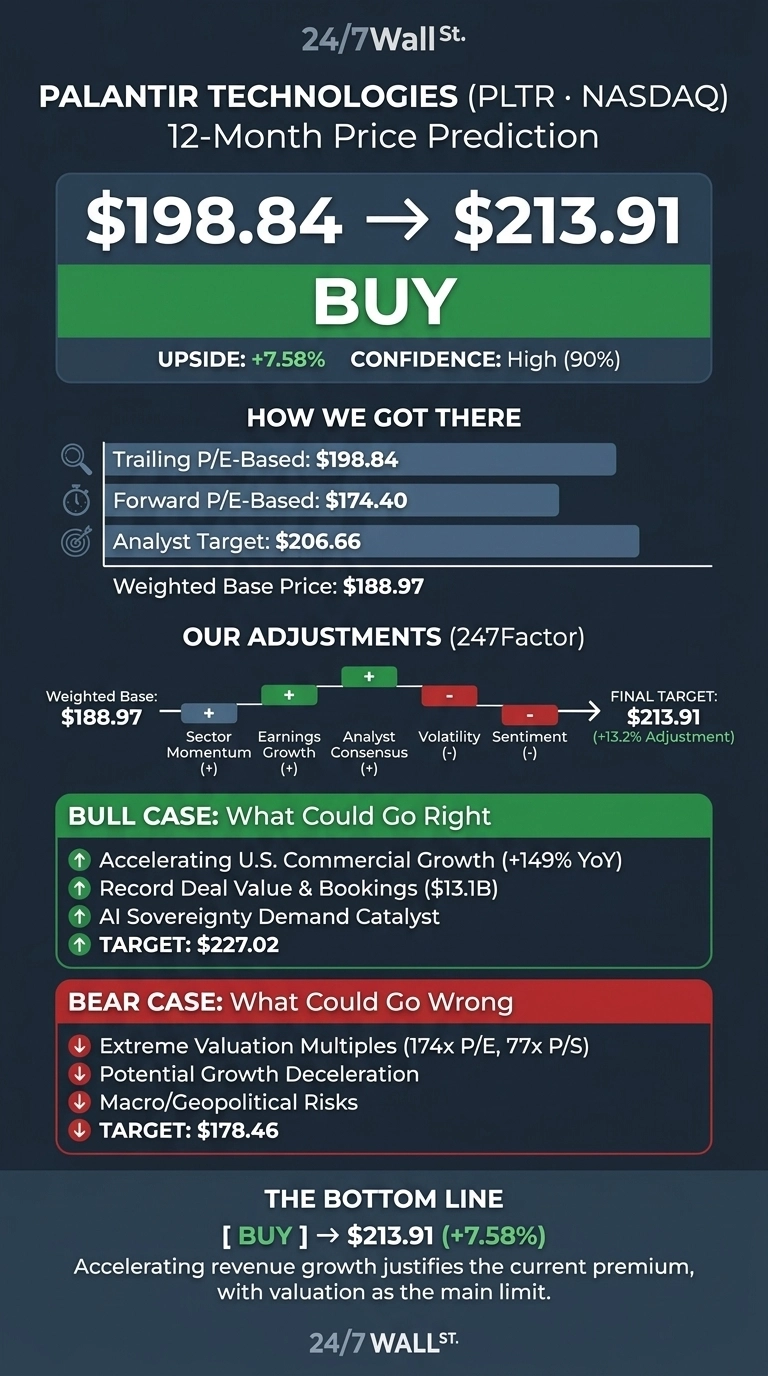
The 24/7 Wall St. price target for Palantir is $213.91 over the next 12 months. Against a reference price of $198.84, that works out to 7.58% upside.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $198.84 |
| Price Target from 24/7 Wall St. | $213.91 |
| Upside/Downside | 7.58% |
| Recommendation | BUY |
| Confidence Level | 90% |
The model rates Palantir a buy with high confidence. The upside is moderate, though, because the stock already trades close to its highs.
Early this morning shares changed hands at $197.56. Palantir is growing faster than almost any large software company. Valuation is now the main limit on how much further the stock can climb.
A Record Quarter Sent Palantir Back Toward Its Highs
Over the past week the shares rose 1.76%. They are up 4.16% over the past month and 11.14% year to date. That puts them near their 52-week high of $212.94 and well above the low of $106.37.
In the second-quarter report, revenue came in at $1.935B, up 92.8% year over year. EPS of $0.41 beat the $0.28 estimate. Management also raised full-year revenue guidance to $8.150 to $8.158B. Ahead of the third-quarter report, Rosenblatt reiterated its call to buy the stock.

Why Bulls See $227 and Beyond
The bull case starts in U.S. commercial, where revenue grew 149% to $764M. Net dollar retention reached 157%, and total remaining deal value hit $13.1 billion.
On the August call, CEO Alex Karp said “Demand for AI sovereignty has now been unleashed.” Of the analysts covering the stock, 20 rate it a Buy or Strong Buy. If that momentum carries on, our bull case reaches $227.02.

Valuation and Dilution Are the Risks Worth Watching
Palantir trades at 174x trailing earnings and 76.8x sales, so even a small slowdown could hit the stock hard. International commercial revenue grew only 26%. SpaceX gains added $0.03 to GAAP EPS, and stock-based compensation came to $265M in the quarter.
In fairness to the bulls, that compensation expense is small next to net income of $1.062B. The bear case sits at $178.46. Multiples this high are the exact setup our free bubble survivor’s handbook was written for, covering how to stay in the trade while planning the exit.

Palantir Trades at a Steep Premium to Its Software Peers
| Company | Price/Sales | Revenue Growth (YoY) |
|---|---|---|
| Palantir | 76.8x | 92.8% |
| Snowflake (NYSE:SNOW) | 21.7x | 35.1% |
| ServiceNow (NYSE:NOW) | 11.1x | 24% |
Snowflake competes for the same enterprise AI data budgets. It grew revenue 35.1% but still posts a GAAP operating loss of $263 million. Palantir’s GAAP profits help explain why it trades at a much higher multiple.
ServiceNow is the mature comparison for agentic AI workflows. It trades at 31x forward earnings, with AI annual contract value above $1 billion. Against that background, the target looks reasonable, because it leaves the current premium intact without high it further.
Growth Justifies a Constructive Stance
The 24/7 Wall St. price target of $213.91 carries a buy rating and 90% confidence. The key factor is that growth is still speeding up.
Third-quarter results that meet guidance of $2.160 to $2.164B would strengthen the bull case. A sharp slowdown in U.S. commercial growth would weaken it. For now, growth is strong enough to support the premium.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $207.50 |
| 2027 | $208.08 |
| 2028 | $224.45 |
| 2029 | $233.80 |
| 2030 | $254.66 |
These figures follow the model’s base-case path and assume Palantir keeps executing on AIP. A sustained push into sovereign AI could lift results well above this path. A lower valuation multiple could pull them below it.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.