UBS Thinks the Street Is Too Low on AWS. Amazon’s Quarter Is the Test
UBS is calling out Wall Street for sleeping on how profitable AWS can get, and Amazon's October 29 earnings report will either validate that contrarian view or expose a cloud giant running hot on borrowed momentum.

Amazon (NASDAQ:AMZN | AMZN Price Prediction) is expected to report third-quarter results on October 29 after the close. Going into the report, UBS says that Wall Street is too conservative on how profitable AWS can get in 2027 (UBS on Amazon AWS margins).
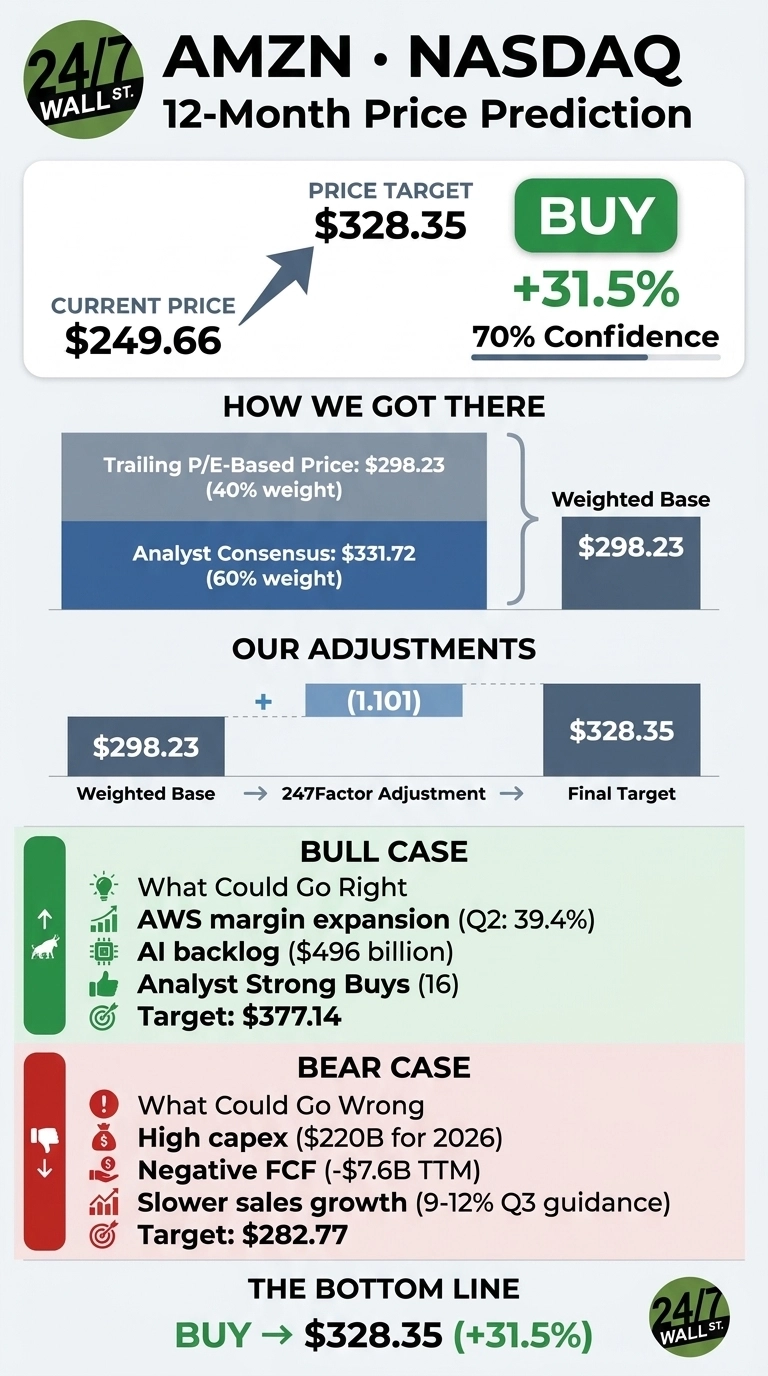
The 24/7 Wall St. price target for Amazon sits at $328.35, which means 31.5% upside from $249.66.
| Metric | Value |
|---|---|
| Current Price | $249.66 |
| Price Target from 24/7 Wall St. | $328.35 |
| Upside/Downside | 31.5% |
| Recommendation | BUY |
| Confidence Level | 70% |
The stock earns a buy rating from our model with fairly high confidence. Everything rides on AWS. The cloud unit has sped up for five quarters in a row, and this report will show whether it can keep that pace while Amazon spends heavily on capacity.

AWS Is Accelerating but the Stock Has Gone Nowhere
The stock is 8.16% higher year to date and essentially flat over the past month (0.16%). It sits 13.1% below its 52-week high of $287.20, a decline CNBC described as a stumbling stock.
In Q2, revenue came in at $200.61B, beating the $196.43B consensus. GAAP EPS was $5.75, but that figure includes a $53.4 billion gain on the Anthropic stake.
AWS revenue reached $42.23B, up 37%, its fastest growth in 18 quarters. The shares jumped 15.32% on earnings day and then gave back 6.13% over the next 30 days.

Why Bulls See $377 if AWS Delivers
UBS’s view centers on margins. AWS posted a 39.4% operating margin last quarter, and the firm expects 2027 margin forecasts to move higher (UBS note). The demand behind that call is visible: AWS has a $496 billion backlog, and its AI and chips businesses each run above $25 billion a year.
According to Andy Jassy, AWS has “the potential to be a $1 trillion revenue business.” Of the analysts covering the stock, 16 rate it Strong Buy and 43 rate it Buy. Our bull case is $377.14.

Capex Is the Risk Worth Watching
Management raised its 2026 cash capex plan to about $220 billion because memory costs went up (all of that spending has to be powered, cooled, and networked by someone, and we covered seven of those suppliers in a free AI infrastructure report).
Trailing free cash flow has turned negative at -$7.6B, and the stock trades at 347.63 times free cash flow. Q3 guidance calls for only 9%-12% sales growth. That number is lower mainly because Prime Day moved into Q2.
Management says growth would be nearly 400 basis points higher without the shift. On capex, management says servers pay back in a little less than three years and most AI capacity is signed on contracts of at least five years. Our bear case is $282.77.
Amazon Trades Richer Than Microsoft and Alphabet
Azure competes directly with AWS, which is why Microsoft (NASDAQ:MSFT) belongs here. Azure grew 43% last quarter, and the stock has a lower trailing multiple.
Alphabet (NASDAQ:GOOGL) grew Google Cloud 82%. Its trailing P/E looks low, but a $99 billion equity gain inflates its earnings.
| Company | Trailing P/E | Cloud Growth (Latest Qtr) |
|---|---|---|
| Amazon | 34x | 37% |
| Microsoft | 29x | 43% |
| Alphabet | 14x | 82% |
Measured against 2026 consensus EPS of $12.9043, Amazon trades near 19x, although that estimate also includes Anthropic gains. Against these peers, our target looks reasonable, though it does require AWS to close some of the growth gap.
AWS Margins Tip the Scale Toward BUY
The 24/7 Wall St. price target of $328.35 and the buy rating at 70% confidence remain my call.
I’d turn more constructive if AWS growth holds above 36.7% and margins stay near Q2 levels. I’d turn more cautious if capex keeps rising while AWS slows. On balance, AWS margins are the case for owning Amazon here.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $246.78 |
| 2027 | $334.45 |
| 2028 | $395.10 |
| 2029 | $467 |
| 2030 | $502.25 |
Amazon needs to keep executing on its current strategy for these projections to hold. The returns AWS earns on its capex, whether better or worse than expected, could push the stock well above or below this path.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.