Micron Is Up 225% This Year and Still Trades at 5 Times Earnings. Is It Too Late?
Micron has already locked in the majority of next year's shipments through signed customer agreements, yet the stock sits 27% below its all-time high with a forward earnings multiple that trails both its memory rival and its biggest customer by…

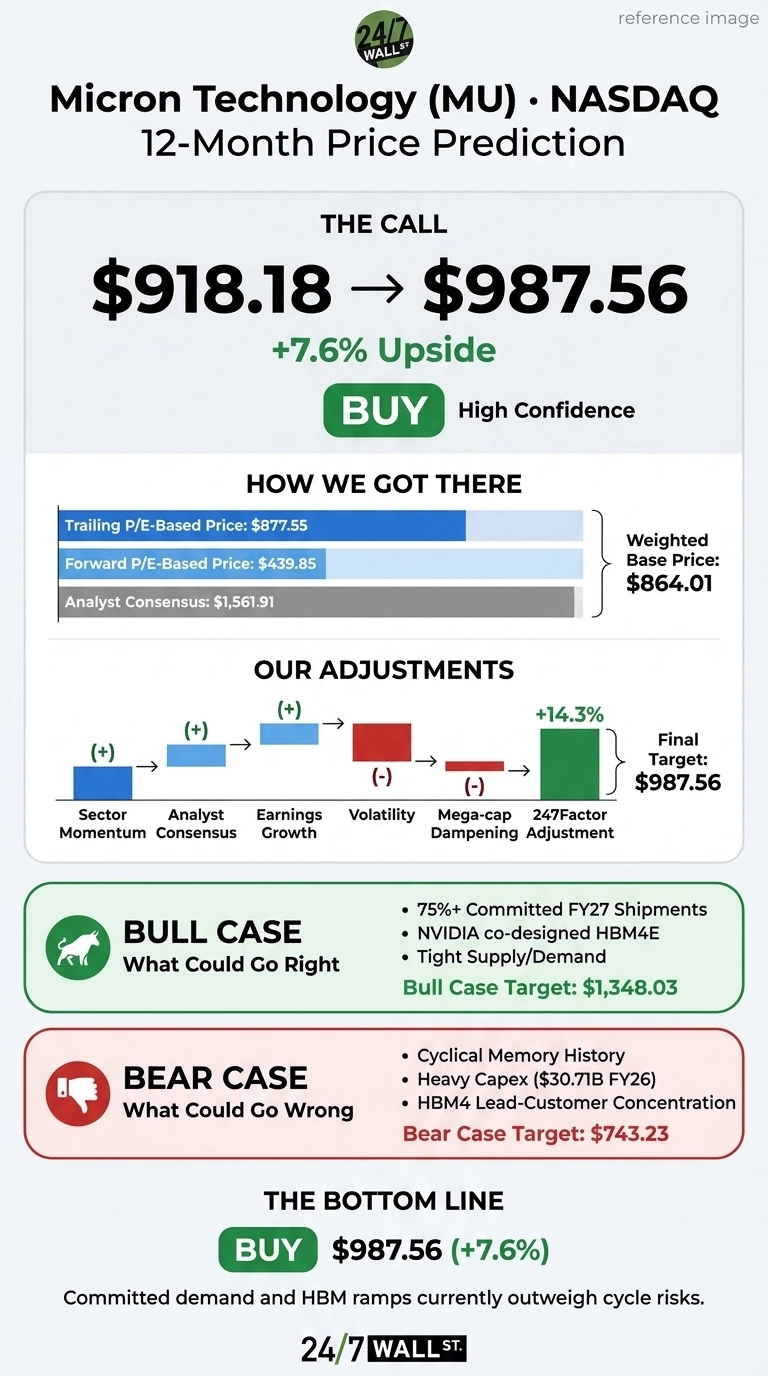
Micron Technology (NASDAQ:MU | MU Price Prediction) is up 221.96% year to date, and the market still values it at about 5x forward earnings. Our 24/7 Wall St. price target for Micron is $987.56 over the next 12 months.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $918.18 |
| Price Target from 24/7 Wall St. | $987.56 |
| Upside/Downside | 7.6% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our model issued its buy rating against an $877.55 reference price. Since then the stock has bounced, which narrows the remaining upside. Confidence is high.
The modest upside reflects a real tension: earnings are compounding at a historic rate, while a beta of 2.23 and memory’s cyclical history argue for discipline on the multiple.
Record Earnings Collide With a Sharp October Pullback
Micron gained 1.47% over the past week but is down 15.15% over the past month. That leaves it 26.8% below its 52-week high of $1,254.61 and far above its low of $192.37.
Fiscal Q4 revenue came in at $54.23B against a $50.97B estimate, up 379.27% YoY. Non-GAAP EPS of $33.42 beat the $31.35 estimate, and gross margin expanded to 87% from 45.7%. For fiscal Q1 2027, management guides to $61.5B ± $1.5B in revenue and $38.15 ± $1.00 in EPS.

This week Micron found its footing after pushing back on the Chinese memory threat. Management says its technology is “at least two nodes ahead of the China competition.”
Why Bulls See $1,348 and Beyond
Our bull case reaches $1,348.03. Wall Street goes further, with a consensus target of $1,561.91 backed by 9 Strong Buy and 36 Buy ratings. Firm-level targets were not available.
Micron has already committed more than 75% of fiscal 2027 shipments and signed 26 Strategic Customer Agreements running through 2030.
A co-designed HBM4E product built with NVIDIA (NASDAQ:NVDA) adds another premium-margin growth driver. On supply, management said it doesn’t “have line of sight to when supply and demand balance.”

Cyclical Risks That Could Send Shares Toward $743
The bear case is $743.23. Capex reached $30.71B in FY26, and HBM4 volume leans heavily on one lead accelerator customer. Memory has always been cyclical, and one analyst rates the stock a Strong Sell.
In Micron’s defense, it still produced $62.31B in free cash flow after that spending. Management also plans to build clean rooms first and add equipment only as demand calls for it, and it expects conditions to stay “supportive through ’28.”
Micron Trades at a Discount to SanDisk and NVIDIA
SanDisk (NASDAQ:SNDK) is the most direct memory comparison. It increased Q4 revenue 371.59% on the same AI storage boom, yet it trades at a higher earnings multiple than Micron.
NVIDIA is Micron’s anchor customer, carrying $279 billion in supply obligations tied largely to memory procurement. Even so, it trades at more than triple Micron’s earnings multiple.
| Company | Trailing P/E | Price/FCF |
|---|---|---|
| Micron | 12 | 17 |
| SanDisk | 16 | 16 |
| NVIDIA | 43 | 54 |
On earnings, the peer group makes the 24/7 Wall St. price target look conservative. On free cash flow, Micron sits close to SanDisk, so the market is pricing in roughly the same amount of cycle risk for both.
Our Model Still Leans Bullish at 5x Forward Earnings
The 24/7 Wall St. price target of $987.56 carries a buy rating with high confidence. Committed demand tips the scale, as signed shipments make peak-cycle fears harder to justify.
The upside strengthens if HBM4E ramps on schedule and pricing holds through 2027. The case weakens if Chinese competition or a slowdown in hyperscaler spending starts to erode margins. At this multiple, our model finds the reward outweighing the risk.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $987.56 |
| 2027 | $1,015.62 |
| 2028 | $1,066.49 |
| 2029 | $1,199.96 |
| 2030 | $1,220.65 |
These projections assume Micron keeps executing on HBM and its customer agreements. A faster-than-expected supply build across the industry could cut them short, and a longer shortage could drove them well higher.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.