Prediction: Micron’s Next Earnings Cycle Could Reset Expectations for the Stock
Micron just crushed earnings for the eighth straight quarter, yet the stock sits 15% below where it was a month ago. With a make-or-break December report on the horizon and 75% of fiscal 2027 shipments already committed, the setup heading…

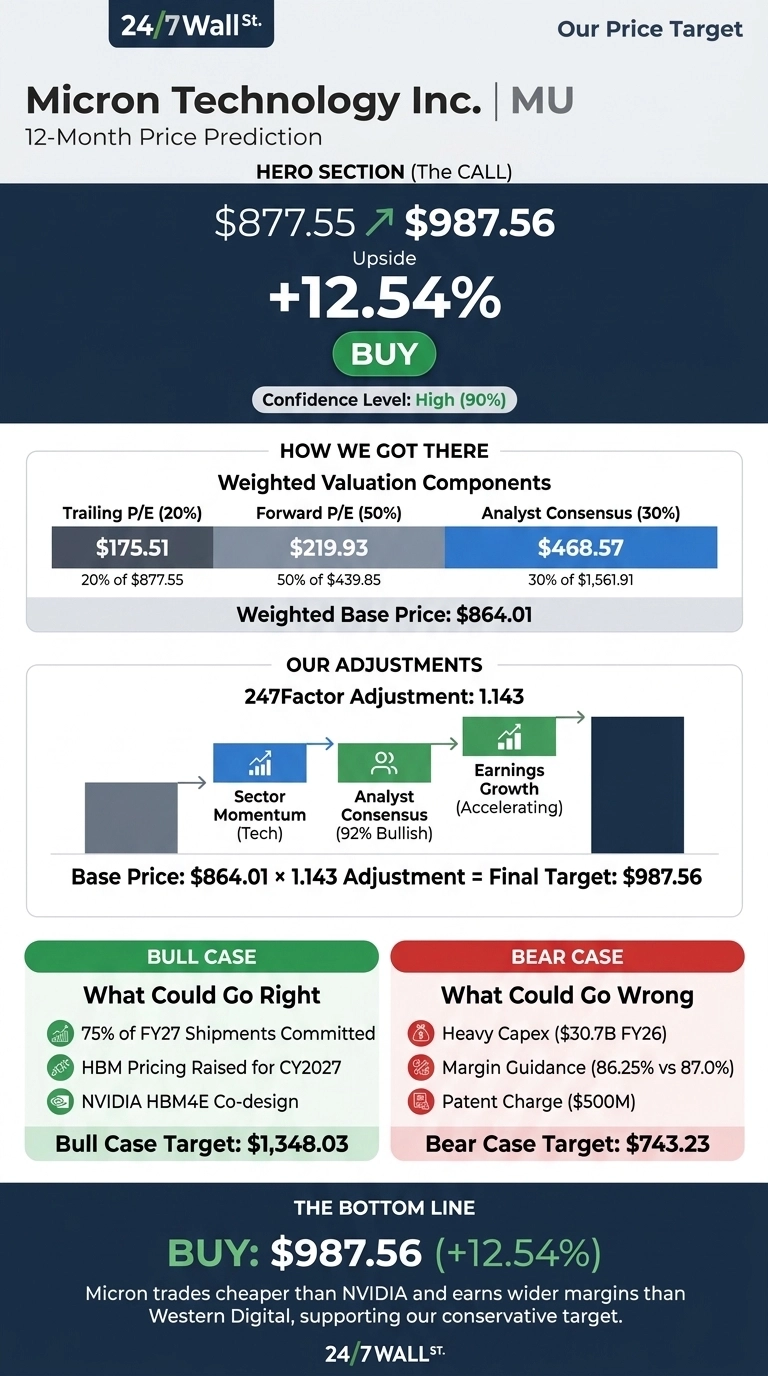
Our 24/7 Wall St. price target for Micron Technology (NASDAQ:MU | MU Price Prediction) is $987.56. That means 12.54% upside from Friday’s close of $877.55. Our model rates Micron a buy with high confidence. Shares were trading at $910.92 late Monday morning.
| Metric | Value |
|---|---|
| Current Price | $877.55 |
| Price Target from 24/7 Wall St. | $987.56 |
| Upside/Downside | 12.54% |
| Recommendation | BUY |
| Confidence Level | 90% |

Everything hinges on fiscal first-quarter 2027 results. The report date is tentatively December 15, and Micron hasn’t confirmed it yet.
Management guided to revenue of $61.5B ± $1.5B and non-GAAP EPS of $38.15 ± $1.00. If Micron meets that bar while trading well below its highs, expectations could reset higher quickly.
Record Earnings Gave Way to a Sharp Monthly Pullback
Micron rose 3.65% over the past week, and Barron’s noted it led Friday’s chip rebound. The stock is still down 15% over the past month but up 219.41% year to date. Its 52-week range runs from $192.37 to $1,254.61.
Fiscal fourth-quarter revenue came in at $54.23B, ahead of the $50.97B estimate and up 379.3% from a year earlier. Non-GAAP EPS of $33.42 exceeded the $31.35 estimate, Micron’s 8th consecutive beat. The stock’s responses to good news have been rocky, though.
After a 23.79% beat in fiscal Q3, shares jumped 15.74% on the day and then fell 32.39% over the next 30 days.

Why Bulls See $1,348 Within Reach
Micron says more than 75% of its fiscal 2027 shipments are already committed. It also has 26 Strategic Customer Agreements running through 2030. Micron raised HBM pricing for calendar 2027, and it is co-designing HBM4E with NVIDIA (NASDAQ:NVDA).
Management added, “We really don’t have line of sight to when supply and demand balance.” Wall Street’s consensus target sits at $1,561.91, supported by 9 Strong Buy ratings alongside 36 Buy calls. Our bull case hits $1,348.03.

What Could Drag Micron Toward $743
Micron spent $30.71B on capex in fiscal 2026, and memory downturns have historically been severe. Guidance also calls for gross margin of about 86.25%, slightly below the 87.0% Micron just reported.
Both have reasons: management expects margins to expand over the rest of fiscal 2027, and most new construction spending targets clean rooms coming online in late 2028. Fourth-quarter results also included a one-time $500M patent license charge. Our bear case comes in at $743.23.

Micron Trades Far Cheaper Than NVIDIA and Earns Wider Margins Than Western Digital
NVIDIA is the key buyer of HBM, so its spending directly drives Micron’s demand. NVIDIA trades at 42x earnings, compared with Micron’s 12x trailing and 7x forward multiples.
Western Digital (NASDAQ:WDC) sells storage into the same hyperscaler expansion. Its revenue grew 55.46% last quarter on a 58.1% non-GAAP gross margin, well short of Micron’s growth and profits.
| Company | P/E | Non-GAAP Gross Margin | Revenue Growth (YoY) |
|---|---|---|---|
| Micron | 12 | 87.0% | 379.3% |
| NVIDIA | 42 | 75.0% | 105.85% |
| Western Digital | N/A | 58.1% | 55.46% |
Compared with these peers, our 24/7 Wall St. price target looks conservative.
Our Model Says Buy Ahead of December
The 24/7 Wall St. price target of $987.56 has a buy rating with 90% confidence. What tips the scale is how much of Micron’s output is already committed for fiscal 2027.
The case strengthens if Micron meets its fiscal Q1 guidance and holds margins near the guided level. It weakens if pricing increases stall or AI capex slows. On balance, committed output supports the model’s view.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $987.56 |
| 2027 | $1,015.62 |
| 2028 | $1,066.49 |
| 2029 | $1,199.96 |
| 2030 | $1,220.65 |
The projections depend on Micron continuing to execute on HBM and its customer agreements. A faster memory supply recovery or an AI spending pause could move results sharply in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.