The AI Memory Boom Could Make This Stock a Much Bigger Story by 2030
Micron has already locked in shipments years ahead, co-designed its next chip with NVIDIA, and posted revenue growth that leaves its peers in the dust, yet the stock trades at a fraction of the multiple those peers command. Something has…

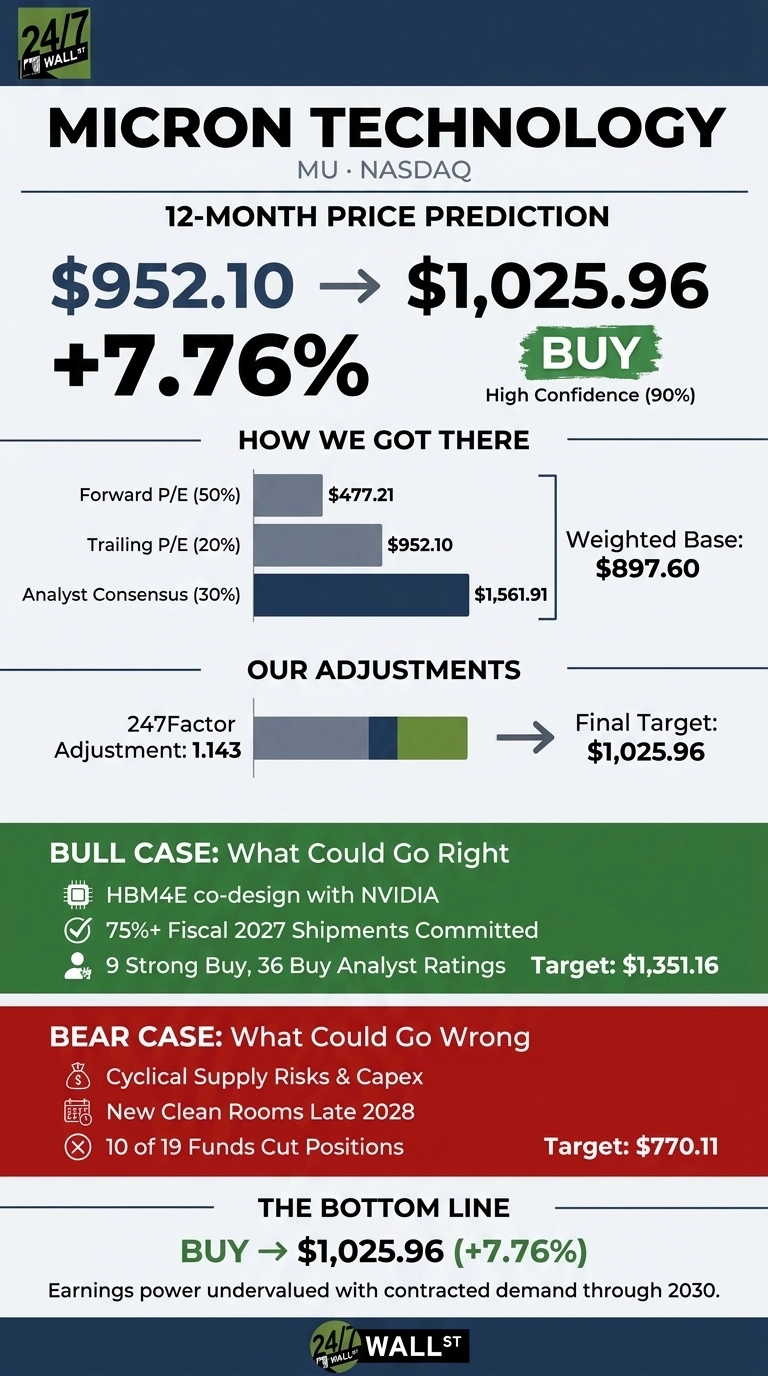
Our 24/7 Wall St. price target for Micron Technology (NASDAQ:MU | MU Price Prediction) is $1,025.96 over the next 12 months. That is 7.76% above the model’s reference price of $952.10. The model rates the stock a buy with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $952.10 |
| Price Target from 24/7 Wall St. | $1,025.96 |
| Upside/Downside | 7.76% |
| Recommendation | BUY |
| Confidence Level | 90% |
Micron has more than 75% of its fiscal 2027 shipments already committed, and it has signed 26 Supply Commitment Agreements that run through 2030.
That visibility explains why our model still sees value after a huge rally. The modest upside comes from mega-cap muting and a sharp one-month decline.

Samsung Results Reset Expectations After a 229% Run
Shares fell 4.51% to $938.87 on Thursday after Samsung’s earnings showed how high the bar sits for memory stocks. Micron is down 10.91% over the past month but up 2.76% over the past week and 229.21% year to date. It sits 24.1% below its 52-week high of $1,254.61 and about 395% above its low of $192.37.
Fiscal Q4 2026 revenue was $54.23 billion, ahead of the $50.97 billion estimate and up 379.3% year over year. Non-GAAP EPS of $33.42 beat the $31.35 estimate. For fiscal Q1 2027, management guided to revenue of $61.5 billion ± $1.5 billion and non-GAAP EPS of $38.15 ± $1.00.

Why Bulls See $1,351 Within a Year
HBM4 is in high-volume shipments, and HBM4E on 1-gamma DRAM is targeting volume production in calendar 2027. Micron is co-designing HBM4E with NVIDIA (NASDAQ:NVDA).
President Manish Bhatia said that AI demand is “making clear that DRAM is the principal constraint versus logic or power to the data center.”
The consensus analyst target sits at $1,561.91, with 9 Strong Buy and 36 Buy ratings. Our 12-month bull case is $1,351.16, a 41.91% gain.

Cyclical Supply Risks Worth Watching
Memory has always been a cyclical business. Capex reached $30.7 billion in fiscal 2026, and new clean rooms are set to come online in late 2028. Management admitted, “We really don’t have line of sight to when supply and demand balance.”
Among the 19 tracked funds, 10 cut positions in the June quarter. The downside scenario is $770.11. On the other side of the ledger, $62.31 billion of fiscal 2026 free cash flow funds the expansion, and most contract pricing includes floor and ceiling bands.

How Micron Compares to NVIDIA and Seagate
NVIDIA is the largest driver of HBM demand. Its supply obligations hit $279 billion, mostly for memory for Vera Rubin. NVIDIA trades at 43x earnings, compared with Micron at about 5x forward earnings, even though Micron’s margins are higher (we reverse-engineered what the early signs of the biggest tech winners looked like in a free playbook here).
Seagate (NASDAQ:STX) shares the same AI data-storage tailwind and guides to $9.20 in fiscal Q2 2027 EPS.
| Company | Latest Quarter Revenue Growth | Non-GAAP Gross Margin |
|---|---|---|
| Micron | 379.3% | 87.0% |
| NVIDIA | 105.85% | 75.0% |
| Seagate | 61.01% | 57.8% |
Compared with these peers, our 24/7 Wall St. price target looks conservative.
Earnings Power Outruns the Multiple
Our 24/7 Wall St. price target is $1,025.96, with a buy rating and 90% confidence. Contracted demand through 2030 is what tips the scale.
The case gets stronger if HBM4E launches on schedule in 2027. It weakens if new supply arrives before demand cools. I see Micron’s earnings power as undervalued.
| Year | Price Target (Base) from 24/7 Wall St. | Bull Case |
|---|---|---|
| 2026 (12-month) | $1,025.96 | $1,351.16 |
| 2027 | $1,003.41 | $1,327.02 |
| 2028 | $1,077.31 | $1,500.85 |
| 2029 | $1,188.06 | $1,850.99 |
| 2030 | $1,198.89 | $1,918.31 |
These projections assume Micron keeps executing on HBM and its supply agreements. The 2026 row comes from the 12-month model, while the 2027 to 2030 rows use the slower five-year path. An glut cycle after 2028 is the biggest risk to these numbers.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.