One Magnificent Seven Stock Could Deliver Outsized Returns. Here’s the Math
Alphabet shares have quietly slipped far enough below their highs that a specific valuation gap has opened up, and the cloud growth numbers behind it tell a story most investors are not pricing in.

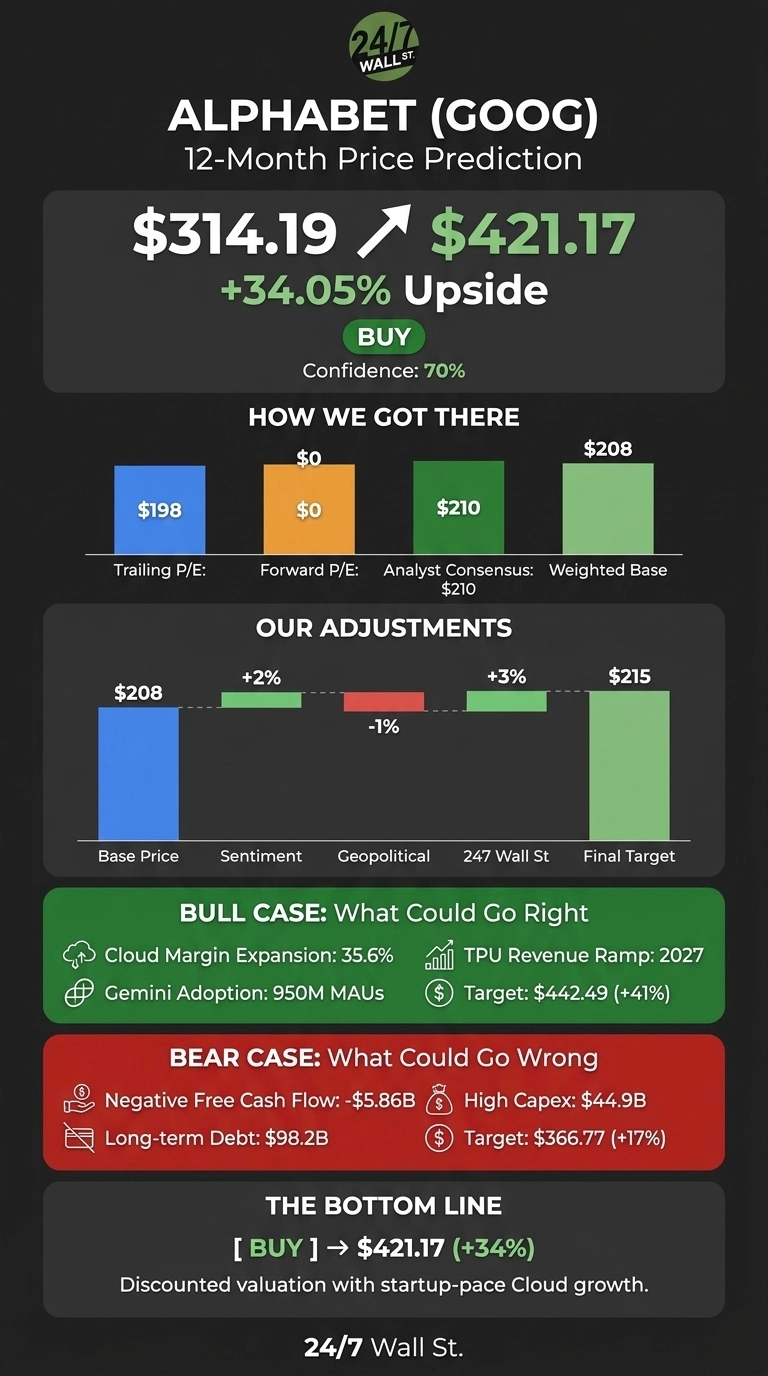
Shares have pulled back from their highs ahead of the company’s next earnings report, and that drop is what makes the numbers work. Our 24/7 Wall St. price target for Alphabet (NASDAQ:GOOG | GOOG Price Prediction) is $421.17 over the next 12 months.
That implies 34.05% upside from the model’s $314.19 baseline.
| Metric | Value |
|---|---|
| Current Price | $314.19 |
| 24/7 Wall St. Price Target | $421.17 |
| Upside/Downside | 34.05% |
| Recommendation | BUY |
| Confidence Level | 70% |

A 70% confidence score signals solid conviction with some room for error. The thesis rests on one point: Google Cloud is growing at a startup pace inside a company valued at 13 times trailing earnings.

A 6.58% Weekly Slide Sets Up a Pivotal Earnings Report
Shares fell 6.58% over the past week and 6.83% over the past month. They’re up just 1.47% year to date, but still 22.31% higher over the past year. The stock sits below its 52-week high of $403.96 and above its low of $266.47.
Investors are weighing reports involving Amazon (NASDAQ:AMZN) and Broadcom (NASDAQ:AVGO) that Google, Amazon and Broadcom offered financing to Anthropic.
Alphabet’s second-quarter revenue came in at $119.80 billion, beating the $116.91 billion estimate and rising 24.2%. EPS of $9.11 topped the $3.04 estimate, though a $99.03 billion unrealized equity gain inflated that figure. Cloud led the quarter, as revenue there rose 82% to $24.8 billion, and backlog reached $514 billion.
Why Bulls See $442 Within Reach
Cloud operating margin expanded from 20.7% to 35.6% in a year. Gemini now has 950 million monthly active users, and management expects the vast majority of TPU system sales revenue to land in 2027.
Wall Street shares that view: Alphabet has 13 Strong Buy ratings, 44 Buy ratings, 5 Holds and zero Sells, with a consensus target of $422.36. Our bull case reaches $442.49.

Negative Free Cash Flow Is the Risk Worth Watching
Capex doubled to $44.92 billion, which drove free cash flow to -$5.86 billion. Long-term debt rose from $46.5 billion to $98.2 billion, buybacks were suspended, and a $40 billion at-the-market program raises the risk of dilution.
On the other side, operating cash flow totaled $185.7 billion over the trailing 12 months, and interest coverage stands at 175.5x. Even our bear case of $366.77 implies a 16.73% gain.
Alphabet Trades at a Steep Discount to Its Big Tech Peers
| Company | P/E | Key Growth Engine |
|---|---|---|
| Alphabet | 13 | Cloud +82% |
| Microsoft (NASDAQ:MSFT) | 30 | Azure +43% |
| Amazon | 35 | AWS +37% |
| Meta Platforms (NASDAQ:META) | 23 | Ads +26% |
Microsoft is Alphabet’s most direct AI cloud rival. Its $678 billion in commercial RPO is larger than Google’s backlog, yet Google Cloud is growing faster.
Amazon still leads in scale with $42.232 billion in quarterly AWS revenue, but it trades at a far richer multiple. Meta shares Alphabet’s dependence on ads and its heavy capex.
Its operating margin fell to 20%, partly because of a $9.89 billion legal charge. Our target implies a P/E of about 16, still below every peer. Next to this group, the target looks conservative.
Our Model Says Buy, and the Cloud Math Tips the Scale
The 24/7 Wall St. price target of $421.17 carries a buy rating with 70% confidence. What tips the scale is a $514 billion backlog coupled with a discounted multiple.
The bull case strengthens if Cloud margins hold up while third-party capacity ramps. The bear case gains weight if free cash flow stays negative into 2027 without a matching jump in revenue. The model’s math tends positive.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $344.57 |
| 2027 | $412.50 |
| 2028 | $509.72 |
| 2029 | $581.12 |
| 2030 | $662.10 |
These projections assume Alphabet keeps executing on its full-stack AI strategy. A Gemini 4 launch could add upside, while regulatory fines or pressure on returns from capex could drove the stock below these levels.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.