Wall Street May Be Underestimating This Magnificent Seven Stock
Alphabet's cloud business is accelerating faster than any hyperscaler rival while the stock sits 21% below its 52-week high, and that disconnect between fundamentals and price is exactly where the bull case gets interesting.


Alphabet (NASDAQ:GOOG | GOOG Price Prediction) traded at $318.15 at midday. The 24/7 Wall St. price target of $421.17 points to 32.4% upside over the next 12 months. The stock earns a buy rating with moderately high confidence.
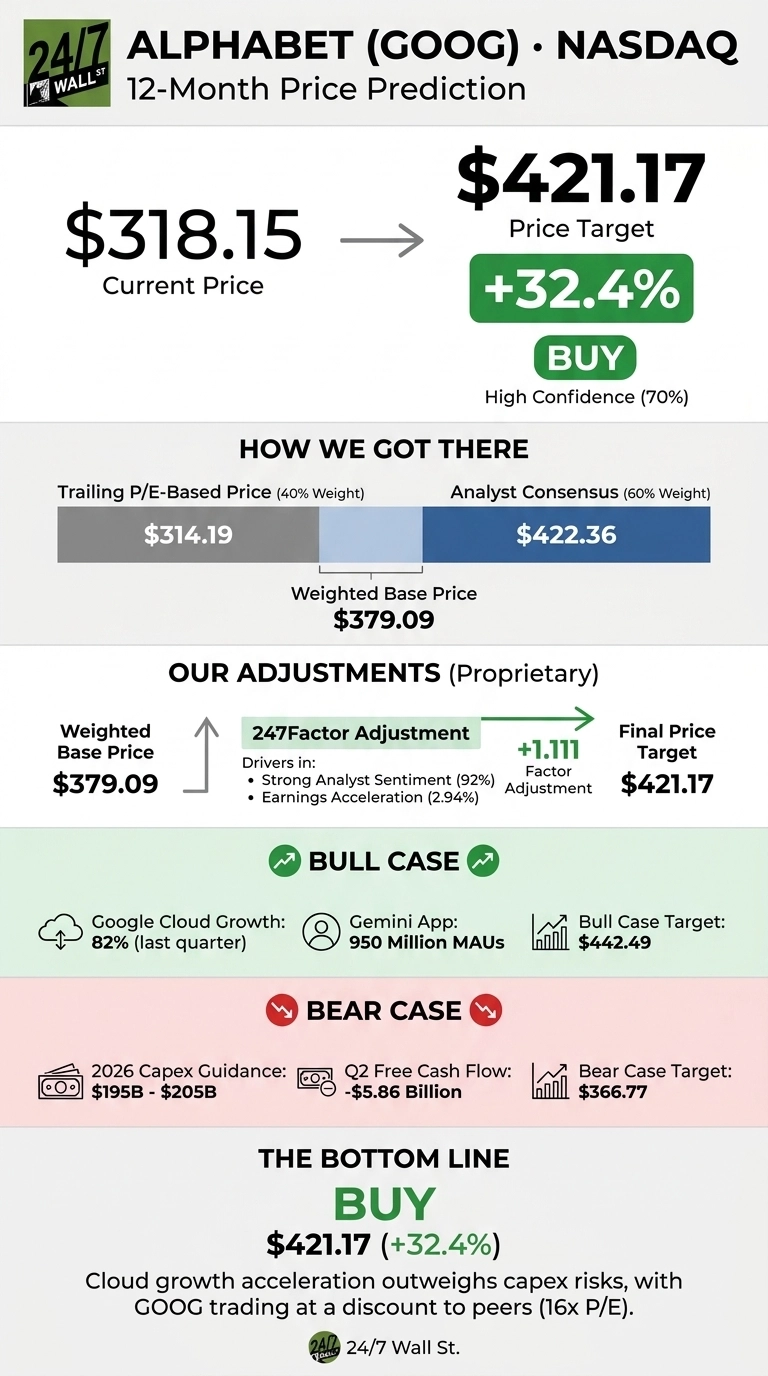
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $318.15 |
| Price Target from 24/7 Wall St. | $421.17 |
| Upside/Downside | 32.4% |
| Recommendation | BUY |
| Confidence Level | 70% |

Alphabet trades at a trailing P/E of just 16 while Google Cloud grew 82% last quarter. The consensus target of $422.36 lands almost exactly on our number, and the Street holds zero sell ratings.
The stock price has gone nowhere this year even as the fundamentals improved, and that gap frames the valuation case.

An October Slide Sets Up a High-Stakes Earnings Report
Shares fell 6.47% over the past week and 6.72% over the past month, leaving them up only 1.58% year to date. The stock trades 21.2% below its 52-week high of $403.96 and 19.4% above its low of $266.47.
Third-quarter results are next, and the Wall Street Journal reports that Google, Amazon (NASDAQ:AMZN), and Broadcom (NASDAQ:AVGO) have offered Anthropic a large financing package (WSJ).
In Q2, revenue of $119.80 billion beat the $116.91 billion estimate. EPS of $9.11 beat the $3.04 estimate, though a $99.03 billion unrealized equity gain did much of the work. Cloud backlog reached $514 billion.

Why Bulls See $442 and Beyond
Cloud now drives the story. Operating margin there hit 35.6%, up from 20.7% a year earlier. Management expects to recognize just over 50% of the backlog within 24 months. The Gemini app reached 950 million monthly users, and Search grew 17% as AI features rolled out.
CEO Sundar Pichai called it the “very early innings” of a secular shift. Berkshire Hathaway (NYSE:BRK.B) added to its stake in Q2 (13F). The bull case lands at $442.49.

A Ballooning Capex Bill Is the Risk Worth Watching
Alphabet raised 2026 capex guidance to $195 billion to $205 billion and expects spending to “increase significantly in 2027”. Q2 free cash flow came in at -$5.86 billion. Long-term debt rose from $46.5 billion to $98.2 billion, and buybacks were suspended.
All of that spending has to be powered, cooled, and networked by someone, and we rounded up seven suppliers riding that expansion in a free AI infrastructure report.
In fairness, trailing 12-month free cash flow was $53.3 billion and interest coverage is at 175.5x. Management also describes demand as supply constrained. Even the bear case of $366.77 still sits above today’s price.
Alphabet Trades at a Steep Discount to Microsoft and Amazon
The most direct hyperscaler comparison is Microsoft (NASDAQ:MSFT). Azure grew 43%, yet Microsoft trades at a P/E of 30.
Amazon shares the same capex risk. Its free cash flow went negative on a trailing basis, and the stock has a P/E of 35 while AWS grew 37%.
All three P/E figures are inflated by investment gains, so Alphabet’s forward P/E of 23 is the fairer benchmark. Even on that basis, Alphabet looks cheaper than both peers while growing its cloud business faster, which makes our target look conservative.
| Company | P/E | Cloud Growth |
|---|---|---|
| Alphabet | 16x | 82% |
| Microsoft | 30x | 43% |
| Amazon | 35x | 37% |
Our Model Rates Alphabet a Buy
The 24/7 Wall St. price target of $421.17 has a buy rating and 70% confidence. What tips the scale is cloud growth that keeps speeding up while the stock still trades at a discount to its peers.
I’d find Alphabet compelling if Q3 shows cloud margins holding as third-party capacity comes online. I’d be more cautious if capex grows faster than backlog conversion. On balance, the October pullback leaves the stock below both our target and the consensus target.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $337.63 |
| 2027 | $421.17 |
| 2028 | $509.72 |
| 2029 | $581.12 |
| 2030 | $662.10 |
These projections assume Alphabet keeps executing on its current strategy. Big swings in either direction could come from the returns on its AI spending or from regulatory action.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.