Meta and Alphabet Face Serious Market Pressure Over Capex in Q4
Meta and Alphabet both burned through more cash than they generated last quarter, and both are now raising outside money to keep spending. Which company has the stronger hand heading into Q4, and what will their AI bets actually cost…

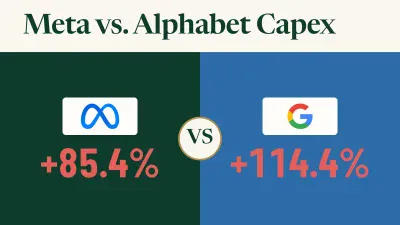
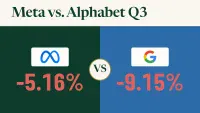
Meta Platforms (NASDAQ:META | META Price Prediction) and Alphabet (NASDAQ:GOOGL) both missed Q3 GAAP EPS estimates because of one-time charges. Their ad businesses still grew. Investors focused on capex instead, because spending drove both into negative free cash flow. Both are also raising outside money, and that leaves them more exposed than other hyperscalers heading into Q4.
Ad Pricing Lifts Meta While Cloud Lifts Alphabet
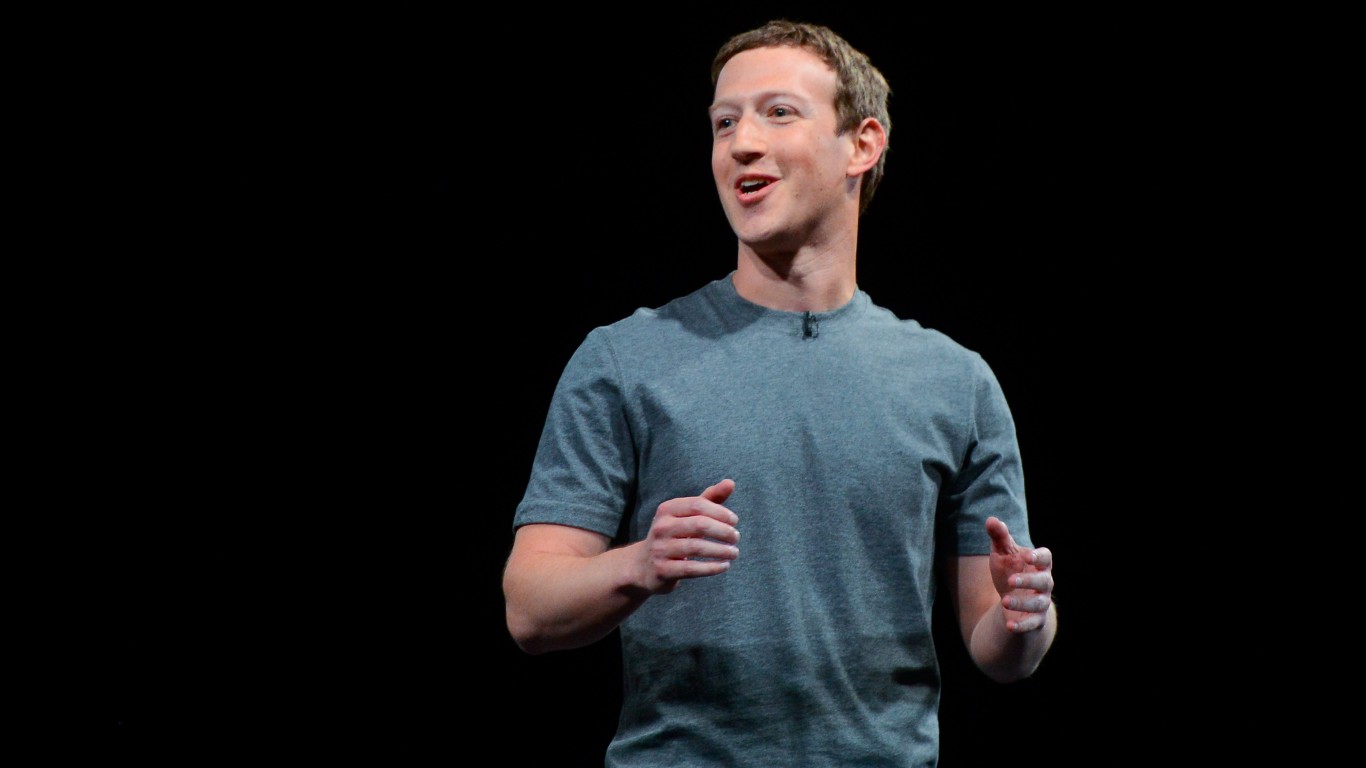
Meta’s revenue rose 26.1% to $64.60 billion. Average price per ad climbed 14%, which suggests AI recommendations are making each ad slot worth more. Without a $9.89 billion legal charge, EPS would have been $7.40. Mark Zuckerberg insisted “the core business is strong.”
Alphabet’s standout was Google Cloud. Revenue there rose 103% and operating income reached $11.12 billion, up from $3.59 billion, so AI demand is already showing up as profit. Sundar Pichai pointed to “strong demand for our TPU systems across a wide range of customers.”
| Business Driver | Meta | Alphabet |
|---|---|---|
| Main Growth Engine | AI-tuned ads | TPUs and Google Cloud |
| Q3 Capex | $34.91B | $51.36B |
| Q3 Free Cash Flow | -$2.12B | -$9.06B |
Outside Funding Puts Both Under a Brighter Spotlight
Alphabet’s capex rose 114.4% and Meta’s rose 85.4%. At both companies, spending exceeded operating cash. Alphabet issued $28.7 billion in notes and also sold shares through an at-the-market program. Meta plans a nonvoting share class that can be used for capital raising, and CNBC reported a large stock offering to fund AI expansion (CNBC). Raising money this way brings dilution and higher interest costs, and both will come up on Q4 calls. The flip side is that every dollar of this capex lands with the power, cooling, and networking suppliers behind the data centers, which we profiled in a free report on seven AI infrastructure names here.
Both companies also depend on advertising, and AI could reshape that business. Bloomberg questioned the economics of Google’s AI Mode, and NBC News reported that Alphabet had its worst day ever. The stock fell 12.61% in a week. Meta has no cloud business to rent out spare capacity, so its return depends on Muse. Susan Li called Muse “pretty compute-expensive.”
Q4 Calls Will Expose 2027 Spending Plans
Meta gave no 2027 numbers and will wait “until we get to the Q4 call.” I will be watching whether Muse delivers the promised 10x cost-efficiency gain before the capex bill grows again. With Alphabet, keep an eye on whether Cloud margins keep up with spending and whether AI search makes as much as classic Search.
Why I Lean Toward Alphabet, With Reservations
I prefer Alphabet’s setup. Its capex already supports a profitable Cloud business where outside customers pay for TPUs. Meta expects its new AI businesses to start adding revenue in 2027, which means a longer wait. I stay skeptical of both while free cash flow is negative, and Alphabet’s cash shortfall is larger. If Muse shopping, where average purchases exceeded $200, starts producing commerce fees, I would rethink my view of Meta.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.