Amazon Vs. Intel: The Good Burn and The Very Bad Burn
Amazon and Intel both reported blowout AI numbers on the same day, yet one stock cratered while the other held firm. The difference comes down to what each company is actually buying with all that cash.

Amazon (NASDAQ:AMZN | AMZN Price Prediction) and Intel (NASDAQ:INTC) both reported third-quarter results on October 29, 2026, and both are pouring cash into the AI buildout. Amazon spends from operational strength to seize an unprecedented AI utility cycle. Intel burns cash from structural vulnerability to fund a high-stakes turnaround.
AWS Sprints While Intel Foundry Bleeds
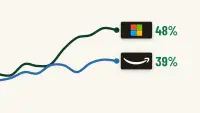
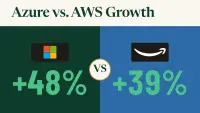
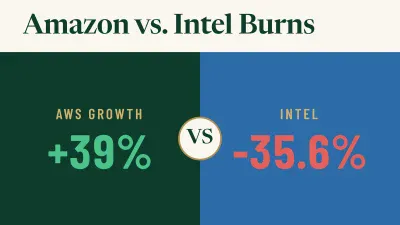
AWS revenue reached $45.98B, up 39%. That is the fastest growth in nearly five years, and it came from a business already this large. Backlog hit $578 billion, so the demand is already signed. Andy Jassy said: “Almost as fast as we install capacity, customers are gobbling it up.” All of that capacity has to be powered, cooled and connected by somebody, and we rounded up seven of those suppliers in a free AI infrastructure report. Retail did its part too. Grocery grew about 3x faster than the rest of the store, which draws Prime members into more frequent visits.
Intel’s best division soared as well. Data Center and AI revenue rose 78% to $7.32B, its strongest growth in 15 years, as hyperscalers scrambled for Xeon CPUs. Intel Foundry still lost $1.85B, though. External foundry revenue came to just $411 million, and most of it came from a non-recurring program. Outside customers still have not shown up in size. Lip-Bu Tan admitted, “I’m disappointed that we were not able to meet strong customer demand in this quarter.”
| Business Driver | Amazon | Intel |
|---|---|---|
| Growth Engine | AWS, Bedrock, Trainium | Xeon server CPUs |
| Weak Spot | Free cash flow | Foundry losses, PCs |
| Main Constraint | Building capacity fast enough | Wafers, substrates, Israel fab shutdown |
One Funds Demand, One Funds Survival
Amazon’s capex jumped 120% to $77.26B, which left a trailing free cash outflow of $42.4B. That looks alarming until you see the operating margin of 13.9%, the highest Amazon has ever posted. Jassy plans about $220B of capex in 2026 and said, “We can fund this plan.” I believe him.
Intel had to raise $23B in new equity just to stay in the race. Management then warned there is “probably not a dynamic where we’re going to have positive free cash flow next year” because it is ramping Intel 18A, Intel 3 and 14A all at once. That is three process nodes competing for one budget. I have doubts that every one of them pays off.
Foundry Customer Wins Will Make or Break Intel
Intel expects to announce a couple of customers over the next two quarters for 18AP. That is worth watching closely, because without outside customers the foundry remains a cash sink. You should also keep an eye on PCs: Intel expects 2027 PC units to fall roughly 10%.
The next test for Amazon is advertising, which management expects to return to high-teens growth in Q4, alongside AWS growth above 40% in both 2027 and 2028.
Why I Lean Toward Amazon’s Burn
Intel fell from $93.09 at filing to $59.97. Amazon is down 9.71% over six months, a modest pullback by comparison.
For me, Amazon’s spending looks like the good burn. It is supported by signed demand and record margins. Intel fits turnaround investors who can tolerate a cash-negative 2027. I would change my view once named foundry customers sign on.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.