Prediction: Marvell Stock Could Have Much More Upside Than Investors Think
Marvell shares just cratered while management raised its revenue outlook, creating a rare tension between Wall Street's confidence and the market's sudden cold feet. Here is what the numbers say about which side gets it right.


Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) just pulled back sharply. Shares trade at $224.01 after an 8.13% drop today. Our 24/7 Wall St. price target is $271.84, which means 21.35% upside over the next 12 months. The model rates the stock a buy with high confidence.
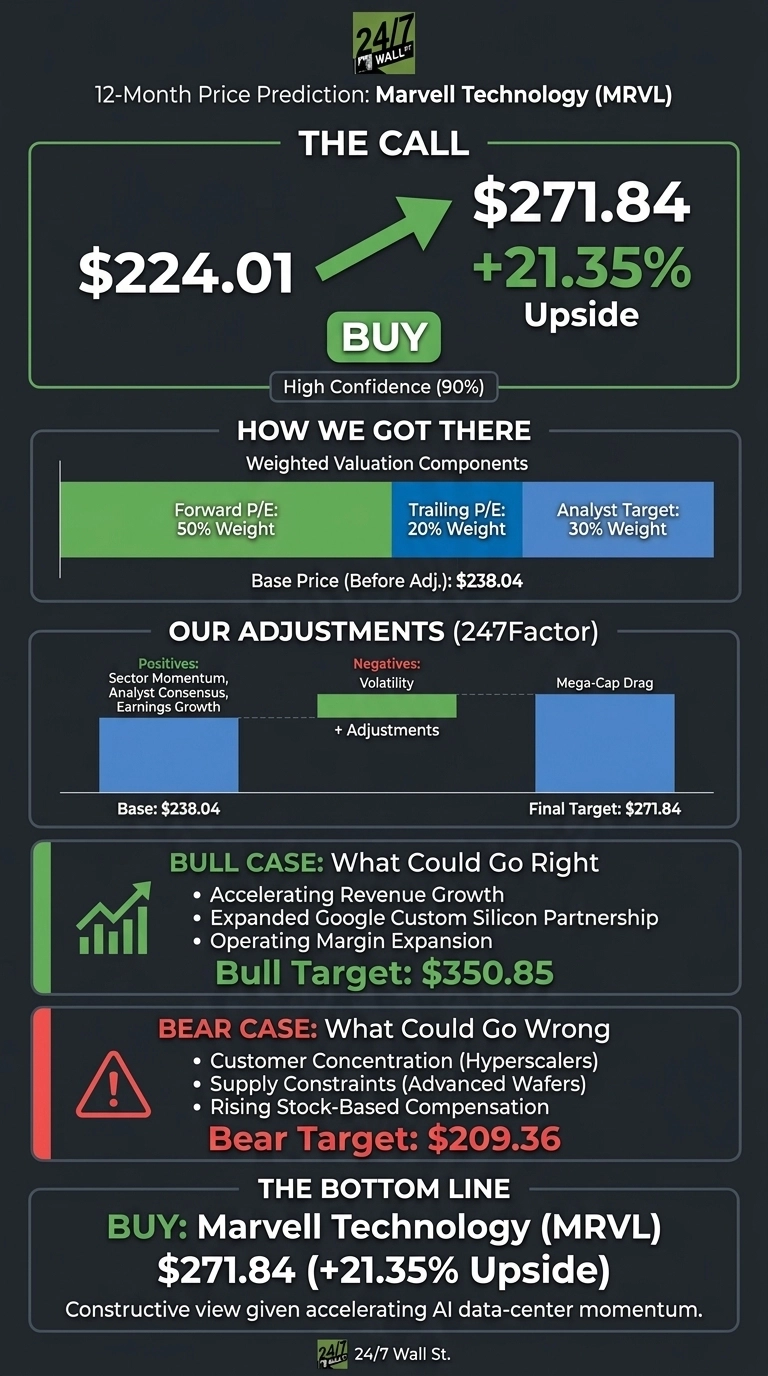
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $224.01 |
| 24/7 Wall St. Price Target | $271.84 |
| Upside/Downside | 21.35% |
| Recommendation | BUY |
| Confidence Level | 90% |

The stock and the business are heading in opposite directions right now. Management raised its revenue outlook for both fiscal 2027 and fiscal 2028 and guided Q3 revenue to $3.150B +/- 5%.
Wall Street’s consensus target of $341.63 sits well above ours, so I treat $271.84 as a measured base case with room to run higher.
A 165% Rally Hits an October Air Pocket
Marvell has fallen 8.33% over the past week and 12.62% over the past month. It is still up 165.04% year to date. Shares sit about 32% below the 52-week high of $329.73 and far above the low of $70.62.
Chip stocks as a group just came off nine consecutive losing days. Marvell then bounced nearly 7% on October 19, when traders moved back into risk.
The fundamentals are holding up well. Q2 fiscal 2027 revenue came in at $2.7393B, +36.5% YoY, ahead of the $2.707B consensus. Non-GAAP EPS of $0.94 beat the $0.9289 estimate.
Data Center revenue grew 46% and now makes up 79% of sales. At its October Investor Day, Marvell raised its long-term revenue forecasts and lifted its fiscal 2029 custom chip target.

Why Bulls See $350 and Beyond
Our bull case reaches $350.85, a 56.62% return. The October Investor Day raised management’s outlook above its earlier earnings-call targets of roughly $12 billion in fiscal 2027 revenue and about 50% growth in fiscal 2028. They also expected custom revenue to more than double next year.
Non-GAAP operating margin should reach the 38% to 40% target range in Q4. The expanded Google deal includes a warrant for up to 7% of Marvell shares, signaling confidence in the custom business.
CEO Matt Murphy said: “Even as our revenue base becomes significantly larger, our growth rate is accelerating.” Coverage counts 8 Strong Buy, 32 Buy and zero Sell ratings. The consensus target means 52.5% upside.

What Could Drag Marvell Toward $209
Our bear case is $209.36. Revenue depends on a handful of hyperscalers, and any of them could design more chips in-house. Supply of advanced wafers is tight, and stock-based compensation rose to $207.6M from $142.1M.
GAAP operating margin of 16.8% trails the non-GAAP 36.6%, partly because of a $331.8M contingent consideration charge. That charge is acquisition-related and should not repeat every quarter. Debt also looks manageable, with net debt at just 0.27 times EBITDA.
Is Marvell Pricier Than Broadcom and NVIDIA?
Broadcom (NASDAQ:AVGO) competes most directly with Marvell in custom AI silicon. Its AI semiconductor revenue grew 221% to $16.70 billion last quarter.
NVIDIA (NASDAQ:NVDA) sets the benchmark for AI accelerators and also partners with Marvell through NVLink Fusion. Both peers are growing faster and trade at lower forward multiples.
Our model gives half its weight to a forward-earnings value well below today’s price, which already builds in some multiple compression. That makes the peer comparison support our 24/7 Wall St. price target as reasonable.
| Company | Forward P/E | Latest Revenue Growth YoY |
|---|---|---|
| Marvell | 62x | 36.5% |
| Broadcom | 19x | 85.5% |
| NVIDIA | 25x | 105.85% |
Pullback Widens the Gap to Our Price Target
Our 24/7 Wall St. price target of $271.84, a buy rating and 90% confidence all reflect one thing above all: growth is speeding up while the stock is falling.
I’d grow more constructive if Q3 lands near the $3.150B guidance and custom revenue ramps on schedule. I’d turn cautious if supply constraints or a hyperscaler moving chip design in-house knocks fiscal 2028 targets off course. For now, the data favors the bulls.
Here is where the 24/7 Wall St. price target model projects Marvell could trade, assuming current growth trends hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $271.84 |
| 2027 | $277.30 |
| 2028 | $300.85 |
| 2029 | $348.88 |
| 2030 | $365.63 |
These projections assume Marvell keeps executing on custom silicon and optical connectivity. The results could land well above or below this path depending on scale-up optics adoption or a slowdown in hyperscaler spending.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.