Marvell Stock Eyes 35% Upside After Lumentum Deal
Marvell's stock has collapsed nearly 30% in a month while its own guidance keeps climbing, and the gap between those two lines is exactly where our model's price target lives.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
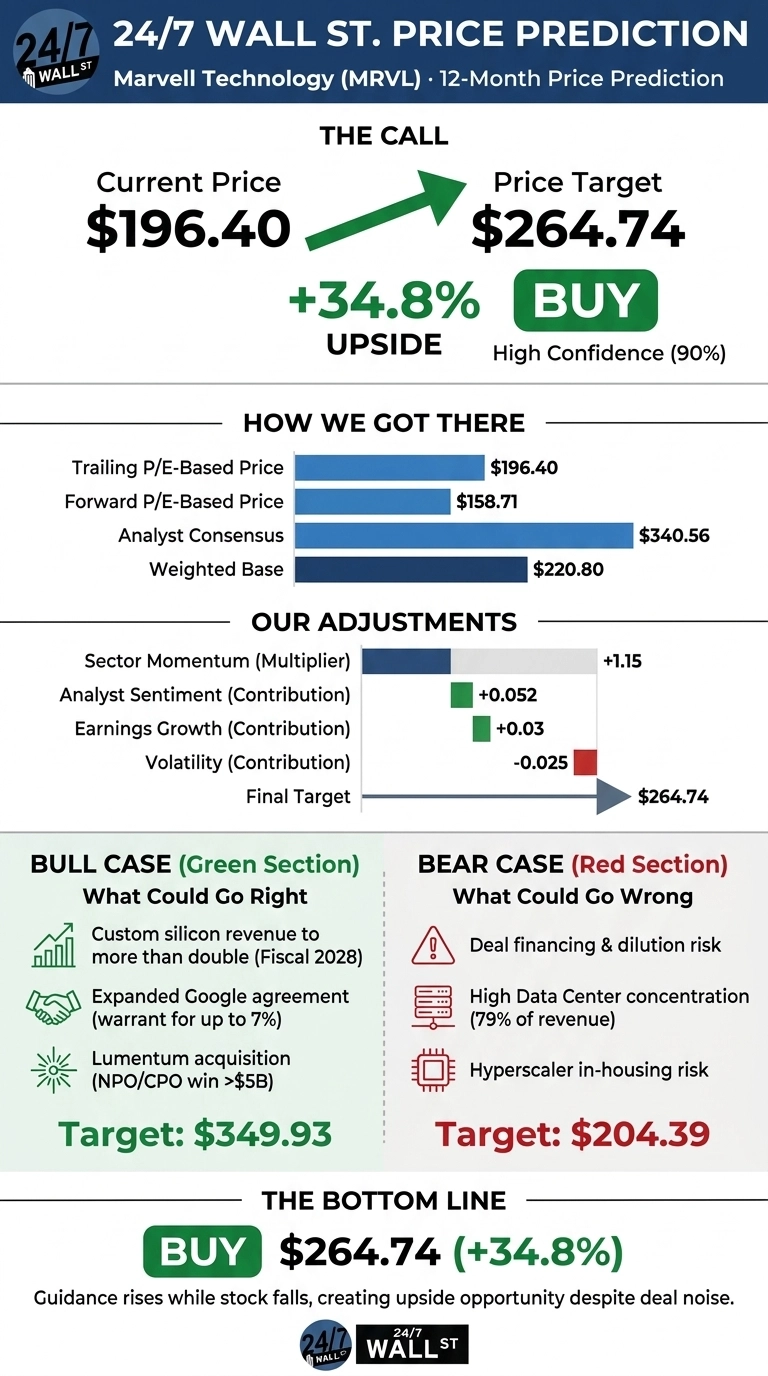
The 24/7 Wall St. price target for Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) is $264.74. The stock closed Friday at $196.40, so the target means 34.8% upside over the next 12 months. Marvell earns a buy rating from the model with 90% confidence, which is its highest conviction level.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $196.40 |
| Price Target from 24/7 Wall St. | $264.74 |
| Upside/Downside | 34.8% |
| Recommendation | BUY |
| Confidence Level | 90% |
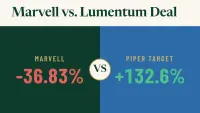
The selloff follows Marvell’s agreement to buy Lumentum (NASDAQ:LITE), the optical laser and module maker.
Reuters described the deal as a bet on AI data centers. Wall Street’s consensus target of $340.56 sits about 73% above Friday’s close, well above our own estimate.

Deal Jitters Erase a Month of Gains While Earnings Keep Climbing
Marvell fell 16.03% over the past week and 27.36% over the past month, measured to Monday’s premarket price of $191.87. The stock is still up 126.16% year to date. Friday’s close left it about 40% below its 52-week high of $329.73.
Barron’s linked the slide to investor dislike of a Lumentum buyout, as the market considered how Marvell would pay for a target valued at roughly $76.15 billion.
The business itself kept accelerating. Fiscal Q2 2027 revenue came in at $2.739 billion, up 36.5% year over year and ahead of the $2.707 billion consensus. Non-GAAP EPS of $0.94 beat the $0.9289 estimate. Management guided Q3 revenue to $3.150 billion ±5% and raised its fiscal 2028 outlook to roughly $18 billion, up from $16.5 billion.
Why Bulls See $350 Within Reach
Our bull case hits $349.93. Custom silicon is the main growth driver. Management expects custom revenue to more than double in fiscal 2028, and an expanded agreement with Alphabet (NASDAQ:GOOGL) gives its Google unit a warrant to acquire up to 7% of Marvell’s shares if revenue milestones are met. Optics is the second driver.
CEO Matt Murphy said scale-up optics is “much larger than we thought just a quarter ago.” Lumentum adds lasers and optical circuit switches, plus an NPO/CPO win backed by purchase commitments exceeding $5 billion.
BNP Paribas analyst Karl Ackerman said of Broadcom (NASDAQ:AVGO) that Broadcom is currently the only provider that combines compute and switch silicon with its own lasers. Lumentum would close that gap. Ratings stand at 8 Strong Buy, 32 Buy and 6 Hold.

Dilution and Concentration Risks Worth Watching
Our bear case lands at $204.39. The most immediate risk is how the deal gets financed and how much it dilutes current shareholders. Data Center makes up 79% of revenue, and hyperscaler customers could design more of their own chips (we covered seven suppliers positioned around that same AI expansion, from power to optics, in a free report you can grab here).
Long-term debt stands at $4.963 billion, and stock-based compensation rose to $207.6 million in Q1 from $142.1 million a year earlier. Q3 gross margin guidance of 57.5%-58.5% is below Q2’s 58.9%.
CFO Daniel Durn said product mix is “the primary driver,” because the fast-growing custom business carries lower margins.
Broadcom Trades Cheaper While Lumentum Commands a Premium
| Company | Forward P/E | Latest Quarterly Revenue Growth |
|---|---|---|
| Marvell | 26x | 36.5% |
| Broadcom | 17x | 85.5% |
| Lumentum | 40x | 136.53% |
Broadcom is Marvell’s closest rival in custom silicon and AI networking. The stock trades at a lower multiple while growing faster, and its consensus target is $530.14. That gap is one reason our target sits well below the Street’s $340.56. Lumentum, the deal target, grows faster still.
It guided next-quarter revenue to $1.575 billion to $1.625 billion. Paying 40x for that growth makes it harder for the deal to add to earnings, but it raises Marvell’s combined growth rate. Our target looks reasonable compared with these two companies.
A BUY Rating With 34.8% Upside Despite the Deal Noise
Our 24/7 Wall St. price target of $264.74 carries a buy rating and 90% confidence. A key factor is that guidance keeps rising while the stock falls.
The bull case gets stronger if deal financing limits dilution and the Q3 results meet the $3.150 billion guidance. It gets weaker if the financing leans heavily on new shares or custom ramps slip. At current levels, our model’s buy rating shows that gap between rising guidance and a falling share price.
Marvell Price Prediction 2026-2030
Looking further out, here is where the 24/7 Wall St. price target model projects Marvell could trade if current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $209.96 |
| 2027 | $262.82 |
| 2028 | $316.83 |
| 2029 | $382.24 |
| 2030 | $410.85 |
Marvell needs to keep executing on its custom silicon and optics strategy for these estimates to hold. How smoothly the Lumentum integration goes, and how much hyperscalers keep spending, could move results well above or below these figures.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.