Prediction: The Next Big AI Stock Winner Could Be Hiding in Plain Sight
Marvell just raised its outlook while shareholders sprinted for the exits, and a blockbuster all-stock deal is the likely trigger. Why would a business this strong get punished, and who stands to profit when panic outruns fundamentals?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) last closed at $171.97. Our 24/7 Wall St. price target for Marvell is $244.16 over the next 12 months, which implies 41.98% upside. Our model rates the stock a buy with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $171.97 |
| 24/7 Wall St. Price Target | $244.16 |
| Upside/Downside | 41.98% |
| Model Rating | BUY |
| Confidence Level | 90% |

Marvell just raised its fiscal 2028 revenue outlook to approximately $18 billion, yet the stock fell 30.2% in a week. That gap between business momentum and share price is why I see Marvell as an AI winner hiding in plain sight.
A Steep Weekly Slide Follows a Blockbuster Deal
Shares are down 37.55% over the past month but remain up 100.39% year to date. The stock sits about 48% below its 52-week high of $329.73.
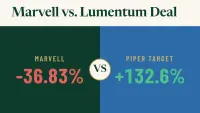
The selloff followed Marvell’s November 2, 2026 agreement to buy Lumentum (NASDAQ:LITE) in an all-stock transaction, which raised dilution concerns. Morningstar now argues the stock looks deeply undervalued.

The business looks healthy. Fiscal Q2 2027 revenue of $2.739B rose 36.55% and topped the $2.707B consensus. Non-GAAP EPS of $0.94 beat the $0.9289 estimate. Data Center revenue grew 46% and now makes up 79% of sales. Q3 guidance calls for $3.150B ± 5% in revenue.
Why Bulls See $350 and Beyond
Management raised its fiscal 2027 revenue outlook to roughly $12 billion and now expects the custom business to “more than double year-over-year in fiscal 2028.” The expanded Google partnership includes a warrant for up to 7% of Marvell’s shares.
On the earnings call, the CEO said, “Whatever you’ve modeled previously for custom numbers prior to the warrant definitely goes higher.” Non-GAAP operating margin is expected to reach the 38% to 40% target range in Q4.
Of the analysts covering the stock, 43 rate it a buy or strong buy, with a consensus target of $333.09. Our bull case is $352.61.

Risks That Could Cap the Rebound
A handful of customers account for much of Marvell’s revenue, and hyperscalers keep building in-house chips such as AWS Trainium. Integrating Lumentum adds execution risk.
Stock-based compensation reached $207.6M in Q1, up from $142.1M. GAAP EPS of $0.33 trailed non-GAAP results, partly because of acquisition costs such as a $331.8M Celestial AI fair-value charge. Leverage is manageable, with net debt at 0.27x EBITDA. Our bear case of $189.98 still sits above today’s price.
Is Marvell Cheaper Than Broadcom and AMD?
| Company | Forward P/E | Latest Quarterly Revenue Growth |
|---|---|---|
| Marvell | 28x | 36.55% |
| Broadcom | 17x | 85.5% |
| AMD | 32x | 44.68% |
Broadcom (NASDAQ:AVGO) competes head-to-head with Marvell for custom AI accelerator work. AI semiconductor revenue grew 221% last quarter, and Broadcom trades at a lower multiple despite faster growth. That comparison is the cleanest valuation test for Marvell.
Advanced Micro Devices (NASDAQ:AMD) gives us a growth-versus-valuation check. Its Data Center revenue grew 97%, and the market pays a premium to Marvell’s multiple for that growth.
Our 24/7 Wall St. price target implies about 40x forward earnings, which is aggressive against this group. That multiple is only justified if Marvell delivers its guided roughly 75% Data Center growth in Q3.
Fundamentals Have Run Ahead of the Selloff
The 24/7 Wall St. price target of $244.16 comes with a buy rating and 90% confidence. What tips the scale for me is the raised fiscal 2028 outlook.
The setup looks compelling if custom silicon and scale-up optics keep speeding up. It suffers if the Lumentum integration stumbles or a major hyperscaler shifts work in-house. On balance, the selloff has taken the stock below what the fundamentals support.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $178.85 |
| 2027 | $236.56 |
| 2028 | $306.36 |
| 2029 | $379.29 |
| 2030 | $400.68 |
These projections assume Marvell keeps executing on its current strategy. Hyperscaler custom programs could drive results well above these figures, while customer losses could pull them lower. We studied what the earliest signs of the biggest AI chip winners looked like and put the pattern in a free Next Nvidia playbook.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.