One Big Reason Investors Should Keep an Eye on DraftKings
DraftKings is making a costly bet on a product category so new that regulators are still writing the rules, and the bill is showing up in its stock price. Whether that spending becomes a competitive moat or a value trap…


DraftKings (NASDAQ:DKNG | DKNG Price Prediction) is spending heavily to lead a new product category. That one decision explains both why the stock has declined and where its upside could come from.
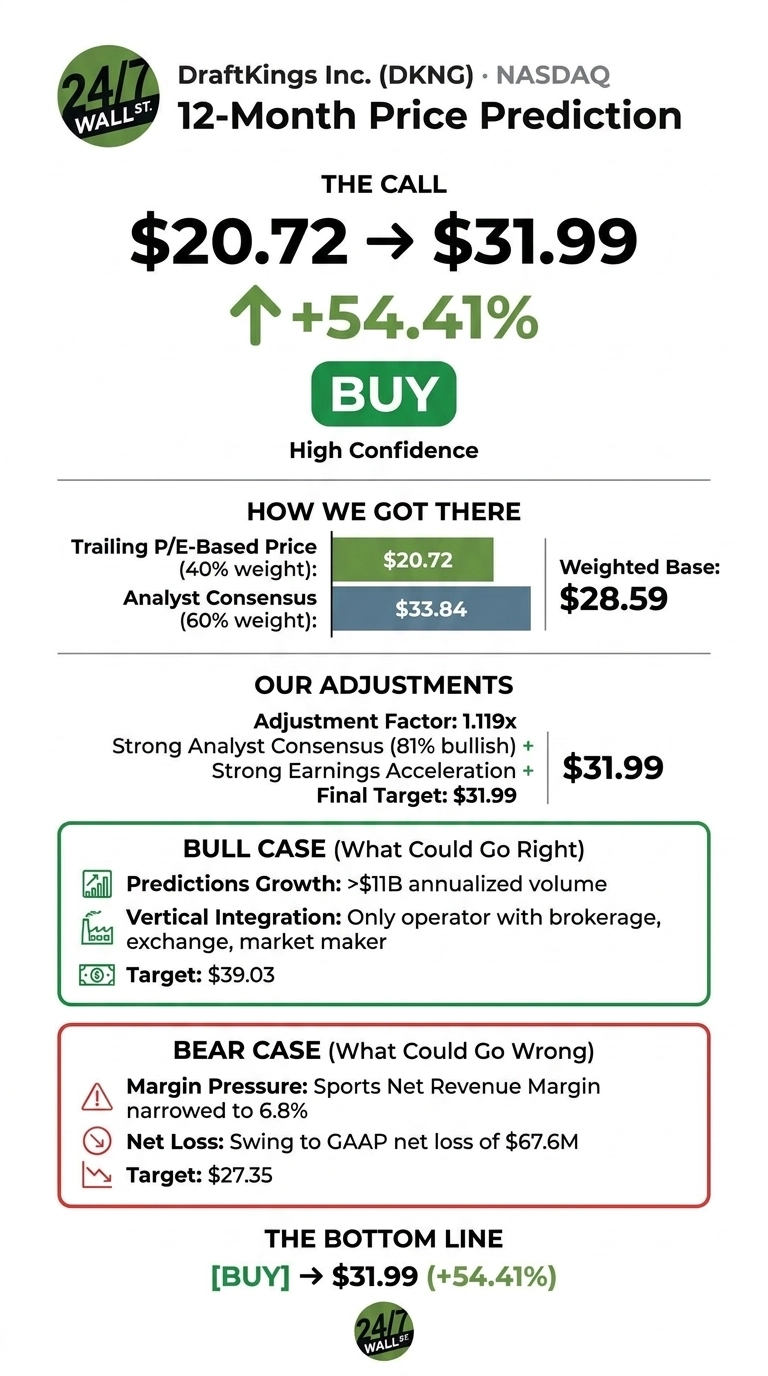
The 24/7 Wall St. price target for DraftKings is $31.99 over the next 12 months. The stock’s prior close was $20.72, so the target means 54.41% upside. Our model rates the stock a buy with 70% confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $20.72 |
| Price Target from 24/7 Wall St. | $31.99 |
| Upside/Downside | 54.41% |
| Recommendation | BUY |
| Confidence Level | 70% |
The one big reason to keep an eye on DraftKings is Predictions, its CFTC-regulated event-contracts platform. It launched in December 2025. On the August earnings call, CEO Jason Robins said Predictions is “already growing faster than we anticipated.”
The cost of acquiring those customers is pressuring near-term profits, which helps explain why the stock sits near the bottom of its 52-week range.

Predictions Spending Pushes Shares Down 41% This Year
Shares traded at $20.31 Friday morning. The stock is down 41.06% year to date and 3.01% over the past week, but up 3.68% over the past month. Shares also beat the broader market on Monday, according to MarketWatch. The 52-week span extends from $18.35 to $36.98.
Second-quarter revenue came in at $1.44 billion. That was down 4.58% from a year earlier and short of the $1.51 billion consensus. Adjusted EPS of $0.09 also missed the $0.1917 estimate.
Adjusted EBITDA fell to $114.60 million from $300.64 million as sales and marketing spending rose to $322.54 million. Management kept its 2026 guidance of $6.5 billion to $6.9 billion in revenue and $700 million to $900 million in adjusted EBITDA.
Why Bulls See a Path to $39
More than 600,000 customers have used Predictions so far this year. Annualized volume traded grew from $2.3 billion to $11 billion between April and July. DraftKings says it is the only operator running its own brokerage, exchange and market maker. It also found only about 1% customer overlap with the largest prediction market operator in sportsbook states, which points to new demand.
Management expects the core business to produce about $1 billion of adjusted EBITDA in 2026. Analysts lean bullish, with 5 Strong Buy and 25 Buy ratings, compared with 6 Hold and 1 Strong Sell. The bull scenario hits $39.03.

Margin Pressure Could Keep Shares Near Their Lows
Sports net revenue margin narrowed to 6.8% from 8.7%. DraftKings posted a GAAP net loss of $67.6M, compared with net income of $157.9M a year earlier. Debt-to-equity stands at 3.06. Management plans to spend an extra $200 million to $300 million on Predictions this year, and federal rules for event contracts are still uncertain.
Management attributed about $80 million of the revenue shortfall to sport outcomes. It also said underlying customer acquisition costs came in about 25% better than expected. The bear scenario lands at $27.35. Still, the stock could return to its $18.35 low if the spending fails to pay off.

DraftKings Trades in Line With Flutter and MGM on Earnings
Flutter Entertainment (NYSE:FLUT) is DraftKings’ direct rival. Its FanDuel unit holds 39% of U.S. sportsbook gross gaming revenue and runs the competing FanDuel Predicts. Flutter expects Predicts losses near the top of a $250-300m range, so the two market leaders are funding the same category.
MGM Resorts International (NYSE:MGM) owns 50% of BetMGM, which gives it online sportsbook exposure alongside its casinos. MGM missed third-quarter estimates with adjusted EPS of -$0.11.
| Company | Forward P/E | Price/Sales |
|---|---|---|
| DraftKings | 12x | 1.62 |
| Flutter | 13x | 0.801 |
| MGM | 12x | 0.408 |
On forward earnings, DraftKings trades in line with both peers, but it has a higher price-to-sales multiple as a digital-only operator. That makes the 24/7 Wall St. price target look reasonable, as long as Predictions turns trading volume into profit.
Predictions Tips the Scale Toward Upside
The 24/7 Wall St. price target of $31.99 and the buy rating at 70% confidence depend mainly on Predictions. I’d find the stock more attractive if its in-house exchange, DKeX, improves unit economics this NFL season and adjusted EBITDA lands within guidance.
I’d grow conservative if margins keep shrinking or regulators restrict event contracts. At 12x forward earnings, the potential reward exceeds the risk.
DraftKings Price Prediction 2026-2030
Looking further out, here is where our model projects DraftKings could trade if current growth patterns and the broader background continue.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $22.22 |
| 2027 | $31.48 |
| 2028 | $42.59 |
| 2029 | $53.81 |
| 2030 | $60.24 |
The projections rest on DraftKings continuing to execute on Predictions and its Super App. Federal rules for event contracts could move the stock sharply in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.