IonQ Beat and Raised. Can the Quantum Stock Buck the Tech Selloff?
Revenue more than tripled, guidance went up, and the stock still sank toward its yearly low. Behind IonQ's disconnect sit a sold-out 2027 order book, heavy dilution, and a cash burn that could swing the verdict either way.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
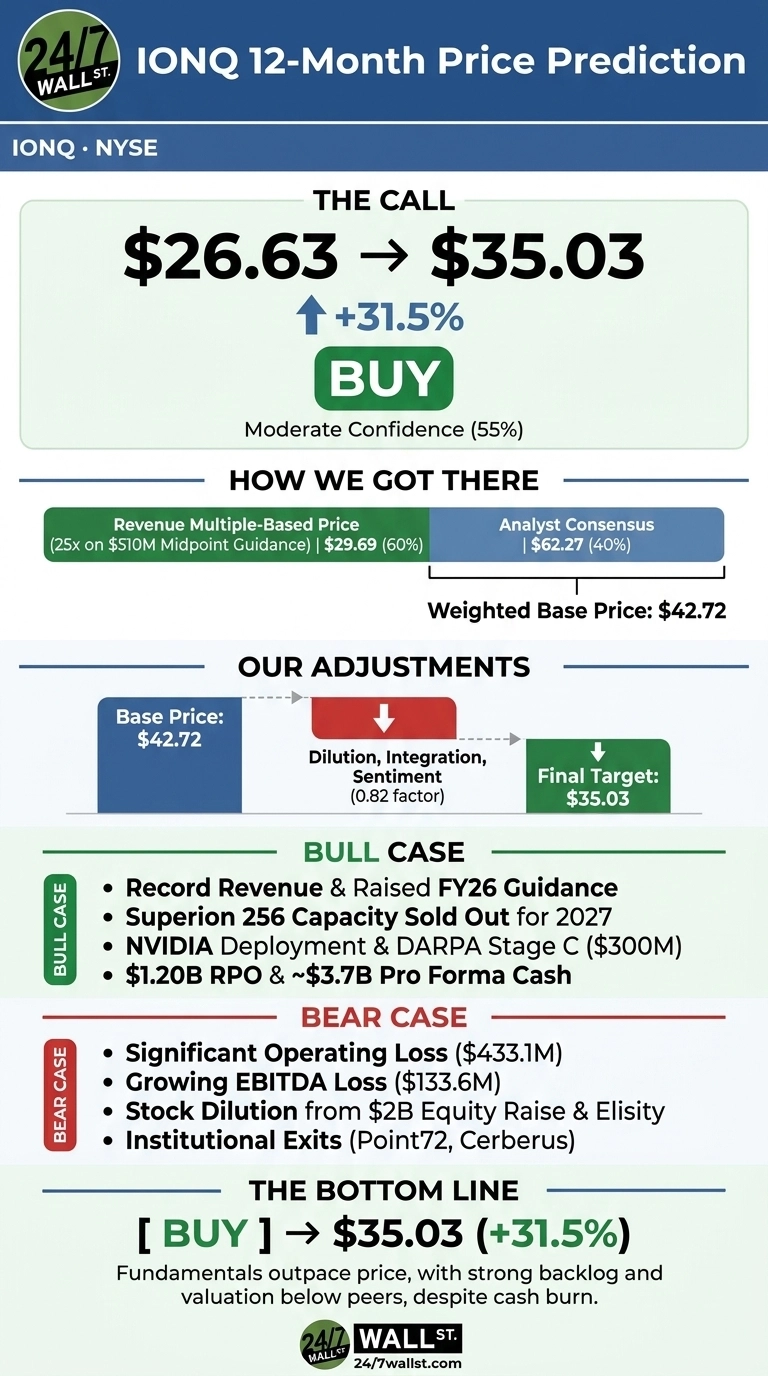
IonQ (NYSE:IONQ | IONQ Price Prediction) just reported the strongest quarter in its history, yet the stock trades at $26.63, near the bottom of its 52-week range. For IonQ, the 24/7 Wall St. price target is $35.03 over the next 12 months. That implies 31.5% upside, and our model rates the shares Outperform.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $26.63 |
| Price Target from 24/7 Wall St. | $35.03 |
| Upside/Downside | 31.5% |
| Model Rating | Outperform |
| Confidence Level | 55% |
A 55% confidence level means moderate conviction. Revenue of $173.83M beat the $141.20M estimate, and management raised FY2026 guidance to $505M to $515M. Even so, dilution and growing losses kept sellers in charge. In my view, the fundamentals now outpace the share price.
A 336% Revenue Surge Collides With a 41% Drawdown
IonQ shares fell 16.68% over the past week and 38.95% over the past month. They are down 41.1% year to date. The stock sits 63.8% below its $73.65 52-week high and only 6.9% above its $24.91 low.
In the quarter, revenue rose 336% YoY, and adjusted EPS of -$0.29 beat the -$0.80 estimate, IonQ’s fourth straight EPS beat. IonQ Platform revenue grew 127% to $90.3M, and newly consolidated SkyWater added $83.5M.
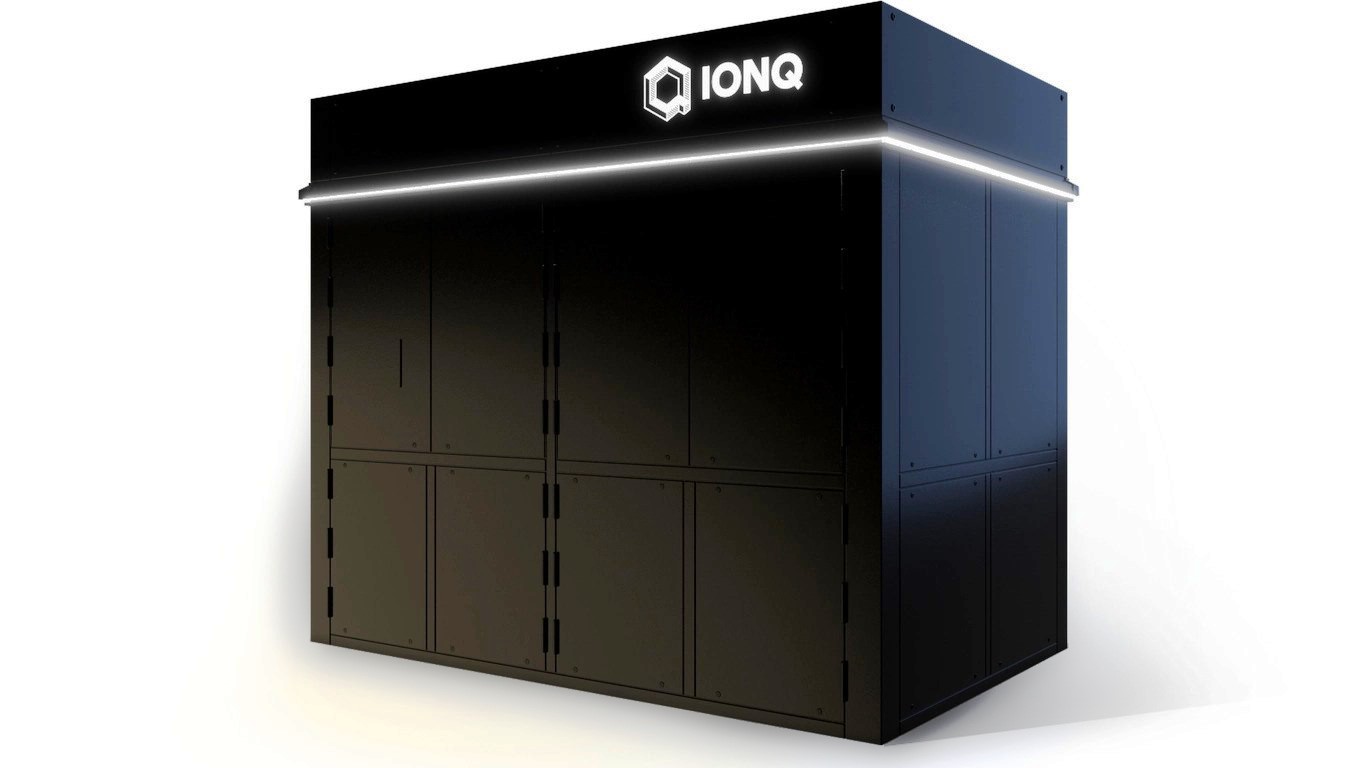
Remaining performance obligations more than doubled to $1.20B. NVIDIA (NASDAQ:NVDA) will deploy a Superion 256 system at its Accelerated Quantum Research Center. IonQ is also the only trapped-ion company to reach DARPA Stage C, a program worth up to $300M.

Why Bulls See $62 Within Reach
Analysts hold 1 Strong Buy, 11 Buy and 2 Hold ratings, with a consensus target of $62.27. Firm-level targets were not available to us. Management said the company has “sold out all of our 256 capacity in 2027” and is filling order books into 2028.
Elisity brings Zero Trust security and about 100 enterprise customers. Pro forma cash of roughly $3.7B funds the roadmap. In the bull scenario, those drivers lift the stock to $62.27.

Cash Burn and Dilution Could Drag Shares Toward $18
The operating loss reached $433.08M, and the adjusted EBITDA loss growing to $133.61M from $48.91M. GAAP net income of $563.96M depended on a $896.16M non-cash warrant gain. Elisity cost $1.15B in stock plus up to $150M in earnouts. Point72 and Cerberus exited their positions in the June 30 filing period. At 15x guided sales, the stock would be worth $17.82.
Offsetting some of that, the quarter absorbed about $40 million in one-time SkyWater integration costs, and management expects adjusted EBITDA to improve in Q4.
IonQ Trades at a Fraction of Rigetti and D-Wave on Sales
Rigetti Computing (NASDAQ:RGTI) is a direct gate-model rival. It is valued at $3.29B on Q2 revenue of just $5.14M.
D-Wave Quantum (NASDAQ:QBTS) is also an IonQ foundry customer. D-Wave carries RPO of $40.7M against IonQ’s $1.20B.
| Company | Market Cap | Price/Sales |
|---|---|---|
| IonQ | $11.44B | 22x (FY26 guidance) |
| Rigetti | $3.29B | 246x (trailing) |
| D-Wave | $3.43B | 276x (trailing) |
IonQ’s multiple uses forward guidance, so the comparison flatters it somewhat. Even so, the gap is wide enough that our 25x assumption looks conservative.
Outperform, With Cash Burn as the Swing Factor
My 24/7 Wall St. price target stays at $35.03 with 55% confidence. What tips the balance is $1.20B in contracted backlog at a valuation well below its peers.
The bull case strengthens if Superion 256 deliveries and the NVIDIA deployment land on schedule in 2027. The bear case gains weight if adjusted EBITDA losses fail to narrow from here. On balance, the beat-and-raise wins IonQ a rebound.

IonQ Price Prediction 2026-2030
The 24/7 Wall St. price target model projects where IonQ could trade if current growth trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $28.03 |
| 2027 | $35.03 |
| 2028 | $45.54 |
| 2029 | $59.20 |
| 2030 | $74.00 |
We project 30% annual gains through 2029 and 25% in 2030. The outcome could swing sharply in either direction depending on fault-tolerant milestones, further dilution and the pace of government quantum spending.
For readers hunting the next monster run in compute, we reverse-engineered what the earliest winners looked like before the headlines in a free playbook here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.