Joby Is Still Down 56% in 2026: Is JOBY Stock Ready to Fly or Is This a False Start?
Joby's FAA certification is entering its final stretch, a defense deal is on deck, and billions sit in the bank. So why does a mounting share count have bears betting this air taxi story stalls before takeoff?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
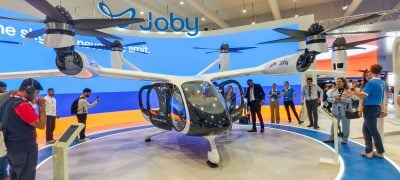
Few air taxi developers have tested investor patience in 2026 like Joby Aviation (NYSE:JOBY | JOBY Price Prediction). Joby stock is at $5.78, up 9% in afternoon trading after the company’s third-quarter report. That rebound still leaves the stock down 56% year to date (YTD).
Over the past 52 weeks, Joby has traded between $4.43 and $17.10. The big question is whether Joby is close to commercial launch or still a long way from proving itself, and its latest results give both sides fresh material.
Where Joby Stands After Its Q3 2026 Report

Joby reported Q3 2026 results on November 4, and Blade, its passenger air mobility business, did the heavy lifting. Revenue at Joby reached $55.1 million, topping Wall Street’s consensus estimate, as Blade flew a record 44,000-plus passengers. On a per-share basis, Joby lost $0.22, smaller than analysts expected and better than the $0.48 loss a year earlier.
The bottom line improved more than the business did. Joby’s net loss narrowed to $211.8 million from $401.2 million a year earlier, largely because of a $286 million improvement in other income. Stripping out that line, the company’s operating loss was still $278.1 million.
Looking ahead, Joby raised its full-year 2026 revenue outlook to $135 million to $140 million from $115 million to $125 million. Joby management expects second-half cash use of $385 million to $415 million, unchanged from its prior forecast.
Joby’s Bull Case: Certification Enters the Final Stretch
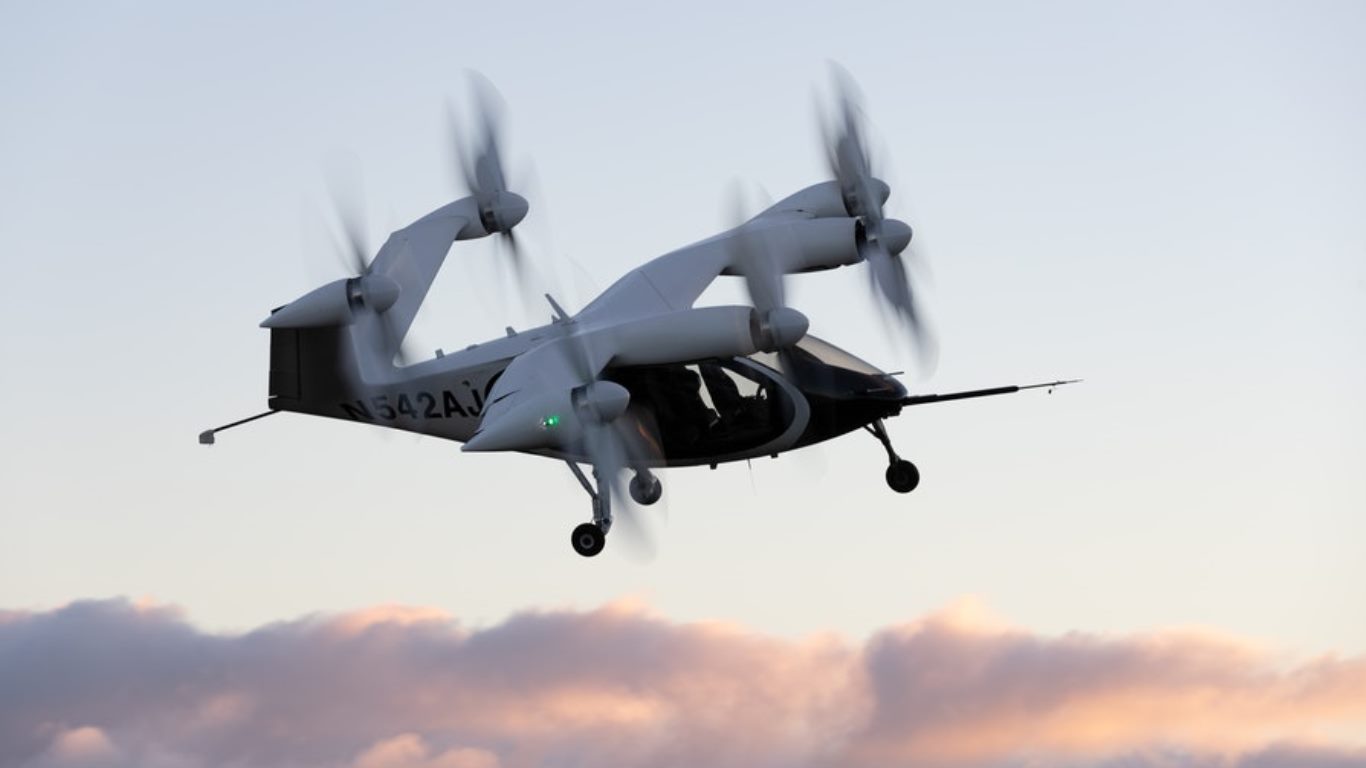
On the November 4 call, CEO JoeBen Bevirt said Joby has completed a wide range of for-credit testing in the fifth and final stage of Federal Aviation Administration (FAA) type certification. Bevirt added that Joby expects to finish its own flight tests and have FAA pilots train on its aircraft in the first half of 2027, and the company now has 17 aircraft in production. Chief Policy Officer Greg Bowles described that next phase as one “where the FAA moves from witnessing bench tests and ground tests and starts flying the aircraft itself.”
Defense adds another leg for Joby. The planned $500 million Resonant Sciences acquisition, expected to close early in 2027, brings a dedicated defense business with more than $100 million in trailing revenue and 40% annual growth. Joby’s cash and investments of $2.2 billion at quarter end also give it a healthy buffer.
Wall Street’s bulls see upside too. H.C. Wainwright keeps a Buy rating and a Street-high $18 price target on Joby. Canaccord Genuity upgraded Joby to Buy while cutting its target to $7 from $11.50.

Joby’s Bear Case: Dilution and a Costly Runway
Dilution is central to the Joby bear case. Joby’s share count climbed from 784.2 million at the end of 2024 to 1.01 billion at September 30. A $750 million at-the-market stock program, set up August 11, produced $128 million in net proceeds for the company in Q3.
Analysts expect a large free cash flow burn for Joby in 2027, on top of the Resonant purchase. Barclays rates Joby Underweight with a $4 price target, questioning the factory can keep up. Needham cut its Joby target to $10 from $15, and the average analyst target has fallen over the past year.
Revenue at Joby remains small next to its $5.76 billion market value. Certification schedules can slip, and Bowles acknowledged on the call that there are no guarantees because Joby is certifying a new aircraft category.
How Joby Stacks Up Against Archer and EHang
Joby’s decline sits between those of its two closest air taxi peers. By comparison, Archer Aviation (NYSE:ACHR) stock is down 42% YTD to $4.34, a smaller decline than Joby’s. Meanwhile, EHang Holdings (NASDAQ:EH) stock is down 71% YTD to $3.84 per American depositary share.
Each company is taking a different path to market. Vertical integration defines Joby, which builds its aircraft in-house and owns Blade for passenger revenue and customer relationships ahead of its air taxi launch. Archer is pairing its Midnight air taxi with defense and artificial intelligence (AI) work, and it agreed to acquire Wisk, Insitu and SkyGrid from Boeing (NYSE:BA). In China, EHang builds pilotless EH216 aircraft and runs drone light shows, though it withdrew its 2026 revenue guidance after a late-June accident involving another company’s piloted aircraft led regulators to slow approvals.
Joby’s Path to FAA Flight Tests and Its Dilution Risk

A key question for Joby is whether FAA pilots begin flying its aircraft for credit, a step management expects to start in the first half of 2027. Success there could move the company into the last major step before a type certificate, and the Resonant deal might add defense revenue along the way. Dilution remains the main offset, since any delay could mean more stock sales to fund the operating loss.
Joby offers a real path to commercial service, along with a real chance of further share issuance, and whether the stock is ready to fly or facing a false start is a call each reader will need to make. The timing of Joby’s FAA flight tests may be the key variable for the stock from here.
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk.His work has appeared in The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, TalkMarkets, Finmasters, 24/7 Wall St., and others.With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.