MCD Stock Outlook: Wall Street Eyes a Potential Upside Breakout After Q3 Results
McDonald's stock bounced hard after earnings, yet U.S. guest counts are still sliding and revenue missed again. One variable could decide whether the rally runs or stalls, and it starts with a cheap bundle being tested in 1,900 restaurants.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

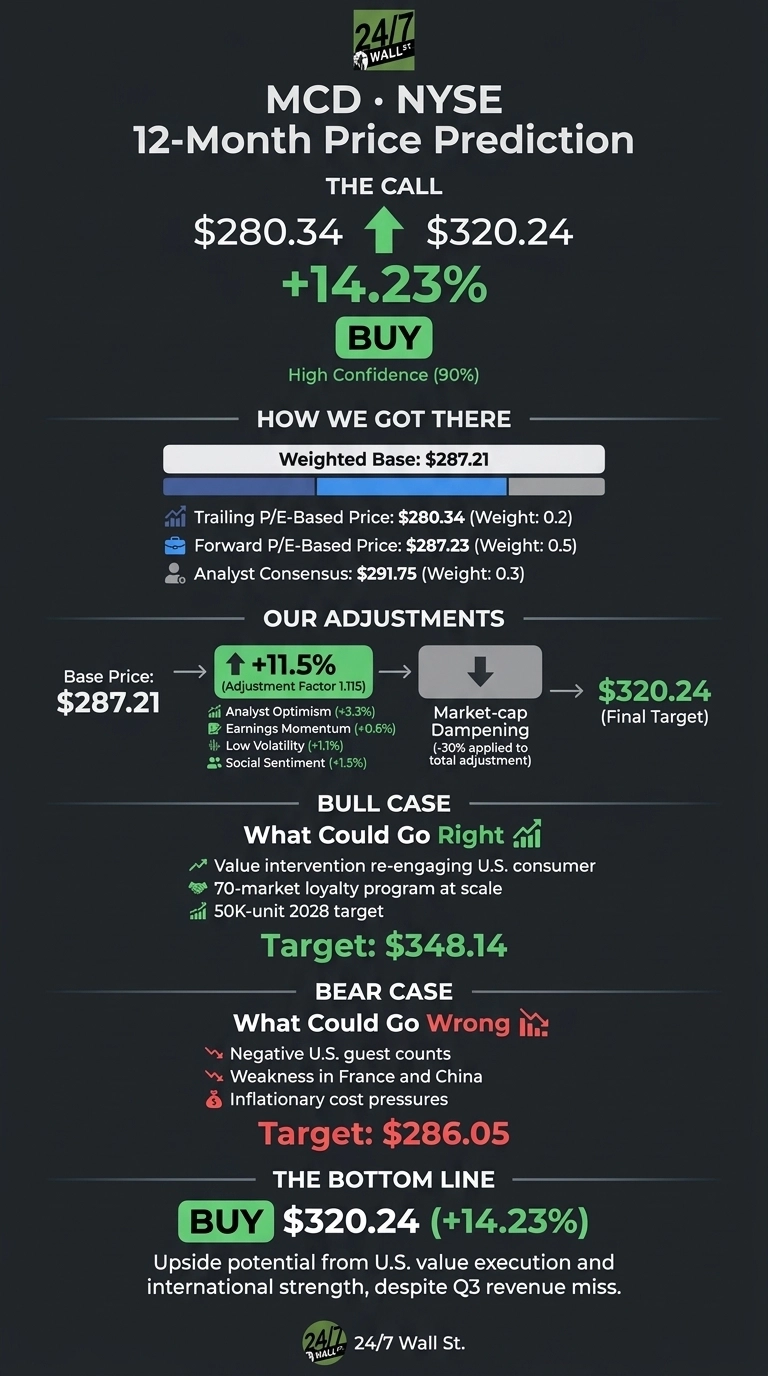
McDonald’s (NYSE:MCD | MCD Price Prediction) closed at $280.34 after investors cheered a third-quarter earnings beat. Our 24/7 Wall St. price target for McDonald’s is $320.24 over the next 12 months, meaning 14.23% upside.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $280.34 |
| 24/7 Wall St. Price Target | $320.24 |
| Upside/Downside | 14.23% |
| Recommendation | BUY |
| Confidence Level | 90% |
That high confidence rests on a low-volatility stock (beta of 0.431), a 4-quarter EPS beat streak, and analyst sentiment that is 58% bullish versus 3% bearish. Our target also sits above the Wall Street consensus of $291.75. The swing variable is the U.S. business, where value deals are only beginning to lift traffic.

Q3 Beat Extends a Sharp One-Month Rebound
Shares rose 6.58% on earnings day and are up 11.86% over the past week and 20.25% over the past month. The stock remains down 6.52% year to date, sitting 16.4% below its 52-week high of $335.18 and 22.3% above its low of $229.20.
Adjusted EPS of $3.57 beat the $3.38 consensus, while revenue of $7.16B missed the $7.29B estimate. Global comps rose 1.5%, and U.S. comps slipped 0.2% before turning positive in September. Barron’s noted the stock rose despite the revenue miss as investors pinned hopes on the NEXT strategy. The quarterly dividend also rose 4% to $1.93.
Why Bulls See $348 on the Table
Our bull scenario hits $348.14. The driver is entry-level value: McDonald’s is testing new bundles in about 1,900 restaurants, with franchisees covering another 4,000 adopting similar deals, together more than 40% of the U.S. system. A national launch is targeted for early 2027.
Specialty drinks already run in nearly 18,000 restaurants, with 7,000+ more in Europe planned by mid-2027. Constant-currency adjusted EPS grew 11%, and loyalty sales hit $41B over the trailing 12 months.
Wall Street totals 4 Strong Buy and 15 Buy ratings against 1 Sell.

What Could Hold MCD Near $286
The bear case lands at $286.05. U.S. guest counts stayed negative, and Chief Executive Chris Kempczinski warned, “I did not say that fourth quarter U.S. comps would be better.” France, Ukraine, and China remain drags, restructuring runs through 2027, and net debt/EBITDA sits at 3.70. Revenue also missed estimates in back-to-back quarters.
Bulls have a counter. Company-operated revenue fell 3% largely because of refranchising (about 175 restaurants this year), which trades top-line dollars for higher-margin fees. Operating income still rose 7.09%.
McDonald’s Trades at a Discount to Yum and Starbucks
Yum! Brands (NYSE:YUM) is the closest franchise-model rival. It trades at 23x forward earnings, versus 19x for McDonald’s. Yum’s trailing multiple of 13x shows 131.6% quarterly earnings growth, an unusual jump that flatters trailing figures.
Starbucks (NASDAQ:SBUX) offers a turnaround contrast at 33x forward earnings, with a 12.8% operating margin against McDonald’s 46.5%.
| Company | Forward P/E | Beta |
|---|---|---|
| McDonald’s | 19x | 0.431 |
| Yum! Brands | 23x | 0.527 |
| Starbucks | 33x | 1.012 |
Our 24/7 Wall St. price target meaning about 24x forward EPS, in line with Yum. That makes the target look reasonable.
U.S. Value Execution Tips the Scale
The 24/7 Wall St. price target of $320.24 has a buy rating at 90% confidence. The deciding factor is whether entry-level value restores U.S. traffic.
I’d grow more constructive if the early 2027 national rollout lifts guest counts. I’d turn cautious if U.S. comps slip negative again into 2027. For now, the upside case is the stronger one.

Here is where our model projects McDonald’s could trade if current trends hold:
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $284.00 |
| 2027 | $318.39 |
| 2028 | $353.11 |
| 2029 | $385.76 |
| 2030 | $407.63 |
These projections assume McDonald’s keeps executing on McDonald’s Next. The 50,000-unit goal for 2028 and a U.S. value reset could push results higher, and a sustained traffic slump could pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.