$1,000 Invested in KLA 10 Years Ago Would Be Worth Over $21,000 Today

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
From Chip Inspector to AI Choke Point
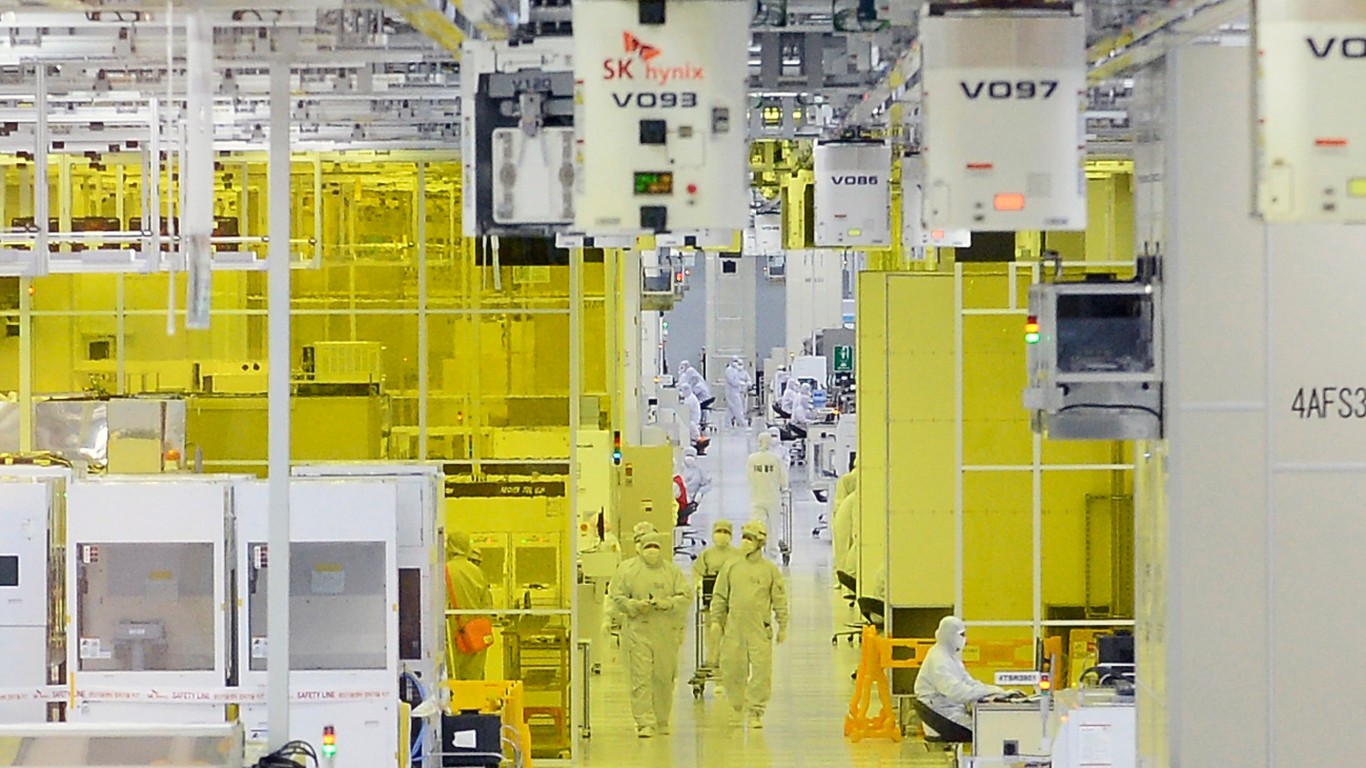
Ten years ago, KLA (NASDAQ:KLAC | KLAC Price Prediction) sold a narrow line of equipment: inspection and metrology tools that catch defects before they destroy a wafer. That segment became a choke point. Chips kept shrinking, and designs kept getting more complex, so every new node needed more process control. KLA leads that market.
The company dropped the Tencor name and became KLA Corporation in 2019. Then AI arrived. Leading-edge logic, DRAM, and advanced packaging all need tighter inspection, and management now talks about KLA’s “critical role as a key enabler of the AI ecosystem”. Revenue for fiscal 2026 came in at $13.579 billion, up 11.71%. The September quarter then set a record at $4.136 billion, up 28.86%.

A Dividend That Grew 342%
The quarterly payout was $0.52 per share in 2016. By May 2026, it had reached $2.30, a 342% increase that marked KLA’s 17th consecutive annual raise. After the 10-for-1 split in June 2026, that works out to $0.23 per share. Because the yield is only about 0.65%, nearly all of the total return came from price appreciation. The dividend was a small extra.
Your $1,000 Became $23,304
1-Year Return
- Initial Investment: $1,000
- Current Value: $1,275
- Total Return: 27.54%
- S&P 500 (same period): $1,122 (12.18%)
5-Year Return
- Initial Investment: $1,000
- Current Value: $3,929
- Total Return: 292.86%
- Annualized Return: 31.5%
- S&P 500 (same period): $1,624 (62.35%)
10-Year Return
- Initial Investment: $1,000
- Current Value: $23,304
- Total Return: 2,230.42%
- Annualized Return: 37.0%
- S&P 500 (same period): $3,478 (247.79%)
KLA’s figures include dividends, while the S&P 500 figures reflect price only. KLA still beat the index at every horizon by a wide margin, and the gap grew the longer you held. Holding on took heart, though. Shares fell from a $430.11 monthly close in December 2021 to $302.63 in September 2022 (pre-split) as the chip cycle turned.
The same kind of swing is happening right now. The stock fell 22.6% over the past month and trades about 50% below its 52-week high of $307.03. Investors who bought near that peak are deep underwater, so timing clearly matters.

What Could Drive KLA’s Next Leg Higher
KLA’s growth case strengthens if wafer equipment spending tops $200 billion in calendar 2027, as management expects. The CEO cited “backlog growth and the visibility in the funnel” as support for several more quarters of sequential growth. December-quarter guidance calls for $4.70B +/- $200M in revenue and non-GAAP EPS of $1.44 +/- $0.11. At about 24 times forward earnings, the valuation depends on those numbers holding.

The risk case grows if U.S. export rules tighten further. China is still expected to make up 27% to 29% of December-quarter revenue. Rising memory costs are pressuring margins, debt of $5.95 billion is larger than cash of $4.7 billion, and the 2021 equipment boom ended in a sharp correction.
Investors exploring the stock will need to consider both cases. The business keeps posting record revenue, and the stock has just been cut nearly in half. Another decline remains possible, and KLA is a reminder of how often the biggest winners hide in plain sight (we studied a group of recent runners most investors walked past and pulled out the pattern in a free report here).
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.