Intel’s Turnaround Could Rewrite the Stock’s Story

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Intel (NASDAQ:INTC | INTC Price Prediction) just posted a steep one-week fall. The selloff has left the share price well below what the fundamentals support.
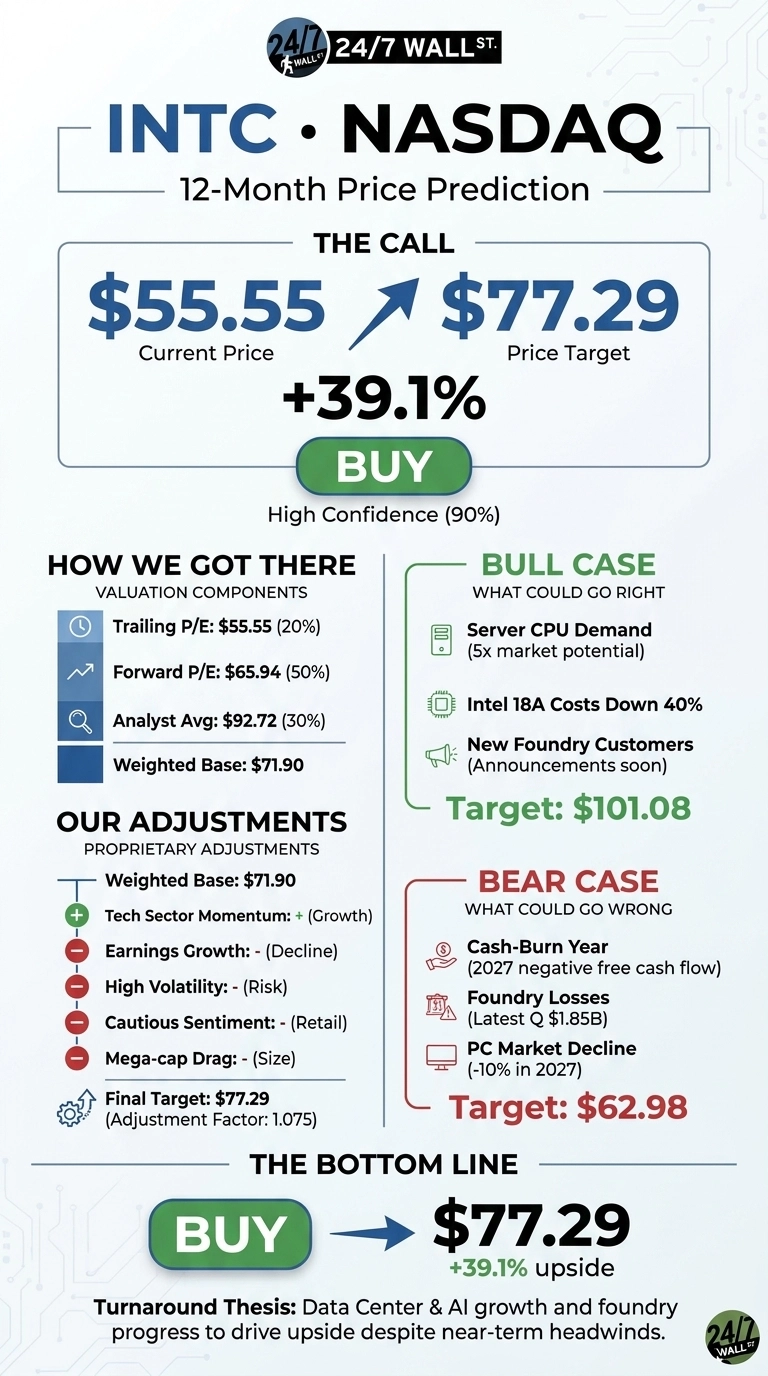
The 24/7 Wall St. price target for Intel sits at $77.29, measured against a model reference price of $55.55. That works out to 39.1% upside, and the model gives the stock a buy rating at high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $55.55 |
| Price Target from 24/7 Wall St. | $77.29 |
| Upside/Downside | 39.14% |
| Recommendation | BUY |
| Confidence Level | 90% |

The market is pricing in a weak PC market and a heavy 2027 spending cycle. Meanwhile, Data Center and AI revenue grew 78% last quarter, which was Intel’s strongest data center growth in 15 years. My model looks past the next two quarters to the earnings power that chief executive Lip-Bu Tan is building.
A 29% One-Day Plunge Wiped Out Months of Gains
Shares fell 29% on October 30, according to the WSJ. Over the past week the stock is down 42.9%, and over the past month it has lost 53.05%, trading near $54.55 midday. Even so, Intel is still up 47.83% year to date. Its 52-week range runs from $32.89 to $142.35.
The third quarter itself was solid. Revenue rose 20.95% to $16.51 billion, and non-GAAP EPS came in at $0.52 against a $0.40 consensus. The guidance did the damage.
Management called for non-GAAP EPS of $0.25 in the fourth quarter and said an accident at its Israel factory would cut fourth-quarter revenue by about $300 million. On top of that, CFO Dave Zinsner said “I don’t think that this will be a year in which we see positive cash flow” about 2027.
Why Bulls See $101 and Beyond
The core of the bull case is server CPUs. Tan estimates that the server CPU market “could increase as much as five times from where it is today from $40 billion to more than $200 billion over five years.” Clearwater Forest is already shipping for revenue, and Diamond Rapids is set to ramp in 2027.
Oracle (NYSE:ORCL) and the DGX Rubin NVL8 platform from NVIDIA (NASDAQ:NVDA) have both adopted Xeon. Intel 18A costs have dropped about 40% since Q1, and Tan expects “a couple of customers ready to announce the next two quarters” for the foundry business.
Wall Street remains cautious, with 12 buy or strong buy ratings against 36 holds. My bull case points to $101.08.

Foundry Losses and a Cash-Burn Year Cloud the Path
Intel Foundry lost $1.85 billion last quarter. Management expects PC unit sales to fall about 10% in 2027. The U.S. government’s stake raises governance questions, and 14A could stall if Intel fails to land a major outside customer.
The foundry loss narrowed by $236 million from the prior quarter. The $12.53 billion second-quarter GAAP charge was a non-cash mark-to-market item. Most of the 2027 spending goes to equipment for nodes that already have demand. My bear case is $62.98.

How Intel Compares to AMD and NVIDIA
Advanced Micro Devices (NASDAQ:AMD) competes with Intel directly in server and PC CPUs. Its data center revenue grew 97%, and it trades at 12.67 times book.
NVIDIA is both a partner and the benchmark for AI growth, with a trailing P/E of about 40x and revenue up 105.85%. Both companies grow faster than Intel, but Intel’s price-to-book multiple is far lower. That makes our target look reasonable, and even conservative, if margins keep improving.
| Company | Price-to-Book | Latest Quarter Revenue Growth |
|---|---|---|
| Intel | 2.71 | 20.95% |
| AMD | 12.67 | 44.68% |
| NVIDIA | 30.72 | 105.85% |
Selloff Has Overshot the Fundamentals
The model sets a 24/7 Wall St. price target of $77.29 with a buy rating and 90% confidence. The deciding factor for me is a server CPU business where demand is still outpacing supply.
The thesis gets stronger if supply of Intel 3 and substrates improves in the second half of 2027 and foundry customers are announced on schedule. It gets weaker if the Israel disruption drags on or 14A fails to win an outside customer. Today’s price already reflects most of that downside.
If current growth trends continue, here is where the model projects Intel could trade.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $58.20 |
| 2027 | $79.15 |
| 2028 | $99.11 |
| 2029 | $118.69 |
| 2030 | $133.77 |
The projections rest on Intel continuing to execute its current strategy. Signing up outside customers for 14A could lift results well above these figures, while continued foundry losses could pull them well below.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.