Prediction: This Stock is Going to Plummet in The Second Half of 2026

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Intel (NASDAQ:INTC | INTC Price Prediction) has been one of the most explosive turnaround stories of 2026, with shares up 263.12% year to date through June 18. After a 12% single-day surge on news of an Apple (NASDAQ:AAPL) manufacturing partnership, the chipmaker trades at $133.99.
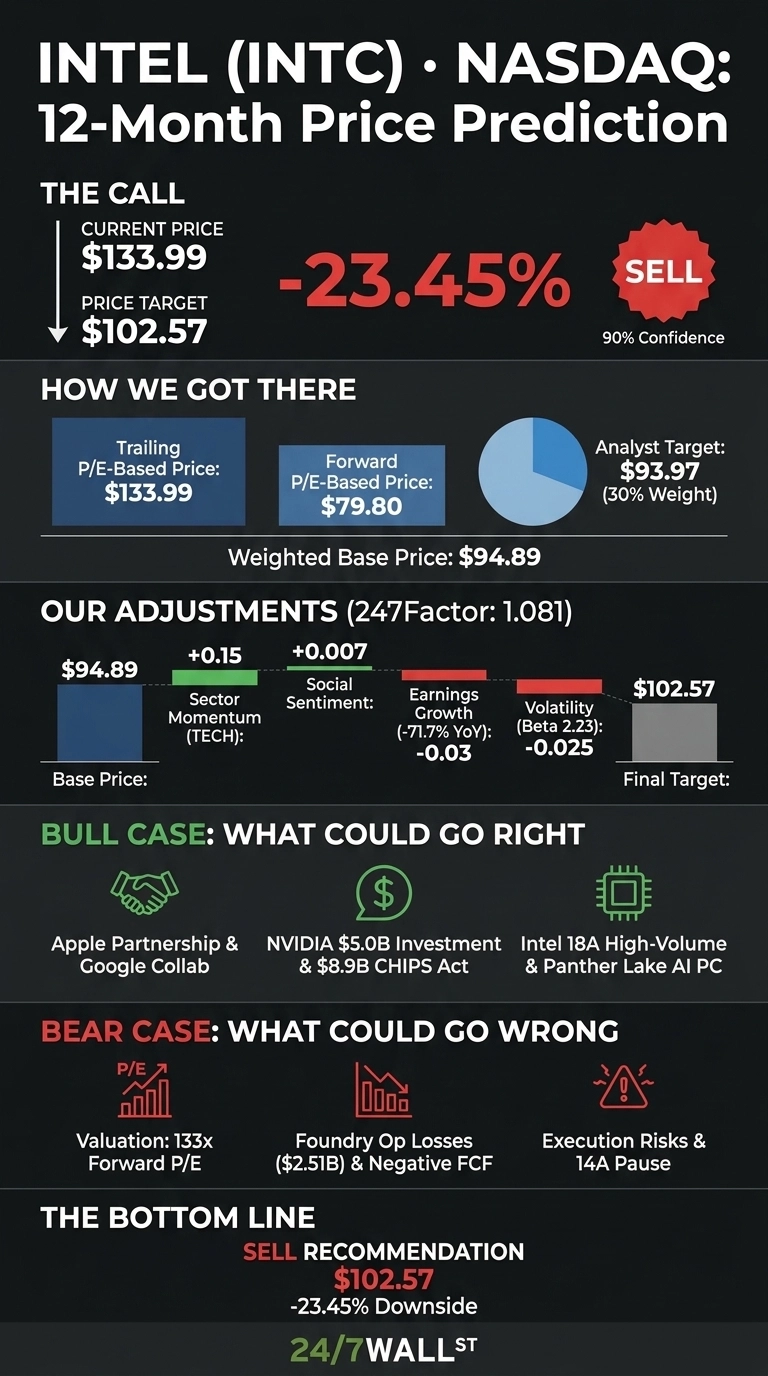
Our 24/7 Wall St. price target for Intel is $102.57, implying a 12-month return of -23.45%. The model rates the stock a sell at current levels with 90% confidence.
| Metric | Value |
|---|---|
| Current Price | $133.99 |
| 24/7 Wall St. Price Target | $102.57 |
| Upside/Downside | -23.45% |
| Model Rating | SELL |
| Confidence | 90% |
Why We Could Be Wrong
Our 24/7 Wall St. price target sits well below current levels. The Apple foundry deal, the 10% U.S. government stake, and a confirmed role producing host CPUs for NVIDIA (NASDAQ:NVDA)’s DGX Rubin NVL8 systems carry potential to push earnings well above our model. A full bull case appears below.

A 523% Rally Reset the Setup
Intel gained 523.5% over the past year and 20.93% in the past month. Trump’s June 18 announcement that Apple would partner with Intel on U.S. chip production sent shares up 10.64% in one session.
Q1 2026 non-GAAP EPS came in at $0.29 against $0.0127 consensus, revenue grew 7.18% to $13.577 billion, and Data Center and AI revenue jumped 22%. CEO Lip-Bu Tan flagged a “sixth consecutive quarter of revenue above our expectations.”
The Case for $150+
If the bull case plays out, Intel’s foundry strategy resembles a second TSMC. The Apple partnership, the multiyear Google (NASDAQ:GOOGL) collaboration on custom ASIC IPUs, and the $5 billion NVIDIA equity investment represent the external customer flywheel Tan has promised.
Combined with $8.9 billion in CHIPS Act funding, Intel 18A entering high-volume manufacturing, and a Panther Lake AI PC platform spanning 200-plus OEM designs, the foundry segment could swing from a $2.51 billion quarterly operating loss to breakeven faster than consensus. Forward EPS could reset toward $1.50, and a 100x multiple gets Intel to $150.
Where the Math Breaks
The bear case rests on valuation. Intel trades at a forward P/E of 133x against TTM EPS of -$0.60. The Q1 GAAP net loss of $3.728 billion reflected a $4.07 billion Mobileye goodwill impairment, so the underlying business is operationally profitable, with non-GAAP gross margin reaching 41.0%. F
ree cash flow remains weak at -$3.867 billion on $4.963 billion in capex. If foundry losses persist or Intel 14A pauses on weak customer commitments, shares could fall to $76.56.
Intel Price Prediction 2026-2030
The 24/7 Wall St. price target stays at $102.57 with 90% model confidence. Forward earnings of $0.60 cannot support a $134 share price under any reasonable multiple.
Revisit the bull case if Intel signs a second flagship foundry customer and forward EPS estimates rise above $1.20. The setup weakens if foundry losses widen or 2026 free cash flow remains negative through year-end.
Our model projects Intel could trade at these levels, assuming current growth trajectories and foundry ramp progress on schedule.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 (year-end) | $119.17 |
| 2027 | $102.57 |
| 2028 | $96.00 |
| 2029 | $90.00 |
| 2030 | $87.00 |
These projections assume Intel executes on its foundry strategy. Significant upside could come from sustained external customer wins, while a 14A pause or prolonged free cash flow burn would skew toward our $62.81 five-year bear case.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.