Micron Has Lost Over 40% Since June. Where Does Its Price Target Stand Now?
Micron just guided to the biggest quarter in its history, yet the market is treating the memory boom like it already peaked. Does one brutal chip selloff reveal a real warning, or a rare mismatch between fear and fundamentals?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
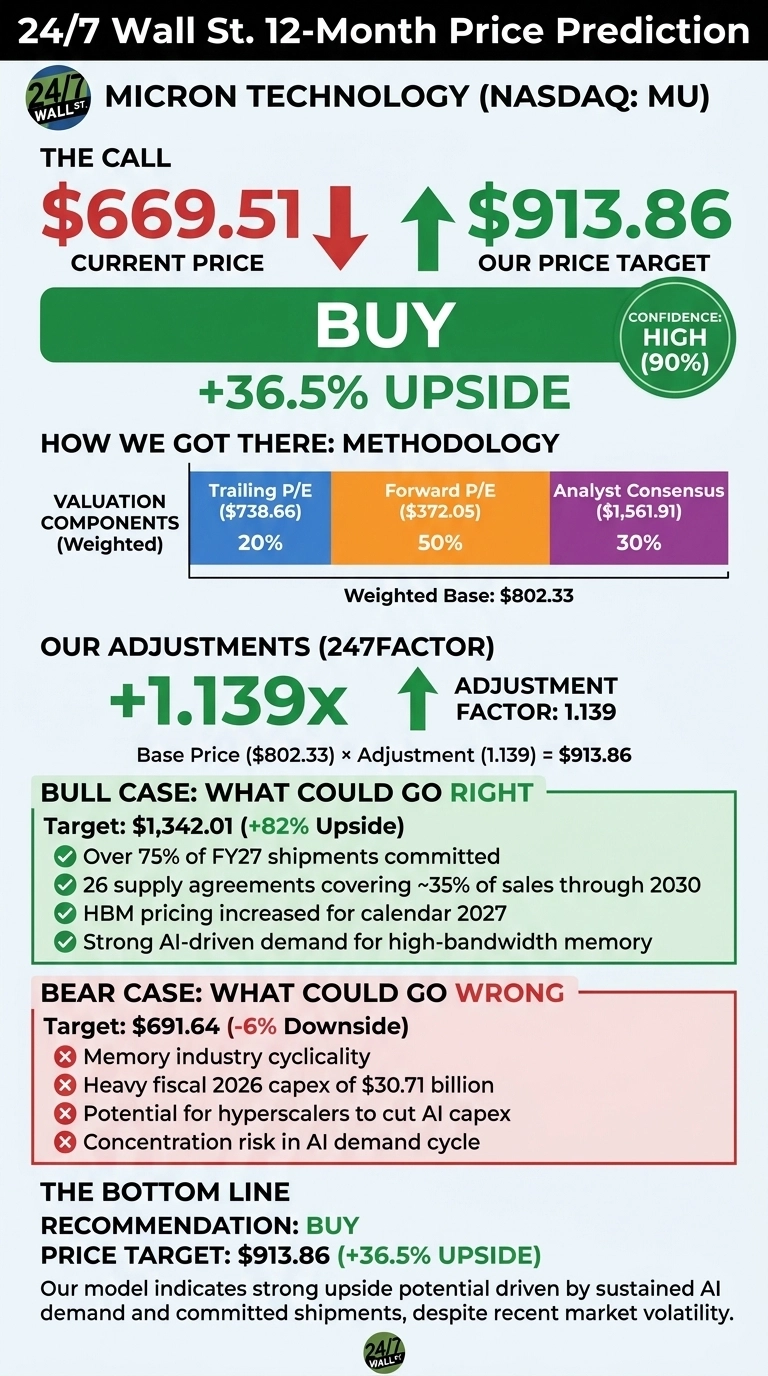
Thursday’s chip selloff knocked Micron Technology (NASDAQ:MU | MU Price Prediction) down 15.81% in one session, to $669.51. The 24/7 Wall St. price target is $913.86, which means 36.5% upside. Our model rates the stock a buy with high confidence.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $669.51 |
| Price Target from 24/7 Wall St. | $913.86 |
| Upside/Downside | 36.5% |
| Recommendation | BUY |
| Confidence Level | 90% |
The market is pricing Micron as if the memory cycle has already topped out.
Management just guided to its largest quarter ever: fiscal Q1 2027 revenue of $61.5 billion ± $1.5 billion and non-GAAP EPS of $38.15 ± $1.00. At about 4x forward earnings estimates, I think view has fallen faster than the fundamentals.
A 46% Slide From the High Despite Eight Straight Beats
Micron fell 29.74% over the past week and 37.21% over the past month. Since June 1 it is down 36.59%, and it now stands 46.6% below its 52-week high of $1,254.61. The stock is still up 130.16% year to date.
The selloff hit NVIDIA (NASDAQ:NVDA), Intel (NASDAQ:INTC) and Sandisk (NASDAQ:SNDK) too, and Bloomberg reported that Micron paused work on a Taiwan plant after a labor dispute. Fundamentals have held up. Fiscal Q4 revenue came in at $54.23 billion against a $50.97 billion estimate, and EPS of $33.42 marked the eighth consecutive beat.
Why Bulls See $1,342 Within Reach
More than 75% of fiscal 2027 shipments are already committed. Micron now has 26 supply agreements covering about 35% of sales through 2030.
HBM pricing was raised for calendar 2027, and management has no “line of sight to when supply and demand balance.” Among analysts, 45 rate the stock buy or strong buy and just one rates it a strong sell. Our bull case is $1,342.01.

What Could Drag Micron Even Lower
Memory remains a cyclical business, and fiscal 2026 capex reached $30.71 billion. Our bear case of $691.64 was calculated from a higher starting price, and the stock has already fallen below it. If investors treat current earnings as peak earnings, the forward-multiple value of $372.05 shows how far the floor could drop.
On the other side, most of the new construction spending goes to clean rooms that open in late 2028, and customer agreements back that expansion. Q4 still produced $33.20 billion in free cash flow.
Micron Trades at a Steep Discount to NVIDIA and Western Digital
NVIDIA is the most direct demand read-through. Its supply obligations of $279 billion are largely linked to memory for Vera Rubin, and it trades at 37x earnings.
Western Digital (NASDAQ:WDC) is a fellow AI storage play. It is guiding to 66%–72% revenue growth next quarter. Both comparisons make our target look conservative. The same AI expansion driving Micron also flows through the power, cooling, and networking suppliers we profiled in a free report on seven AI infrastructure names outside the chipmakers.
| Company | Trailing P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Micron | 11x | 379.27% |
| NVIDIA | 37x | 105.85% |
| Western Digital | Not available | 55.46% |
Thursday’s Plunge Widened the Upside
The 24/7 Wall St. price target holds at $913.86, with a buy rating and 90% confidence. The key factor for me is that the stock has fallen while committed demand has kept growing.
I’d stay constructive as long as HBM pricing adjustments hold and supply agreements keep expanding. Caution would set in if hyperscalers cut AI capex or the Taiwan pause spreads. At these levels, the model’s target far tops the present price.

Micron Price Prediction 2026-2030
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $913.86 |
| 2027 | $1,014.94 |
| 2028 | $1,127.19 |
| 2029 | $1,251.86 |
| 2030 | $1,390.32 |
These figures assume Micron keeps executing its current strategy. A faster HBM4E ramp could push results well above them, and an early end to the memory shortage could drag them well below.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.