Warren Buffett Paid A One-Time Tax To Convert $11.6 Million Into A Roth. Here’s The Math For A 63 Year Old With $800,000 Who Wants To Use The Same Trick To Never Have To Think About RMDs

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
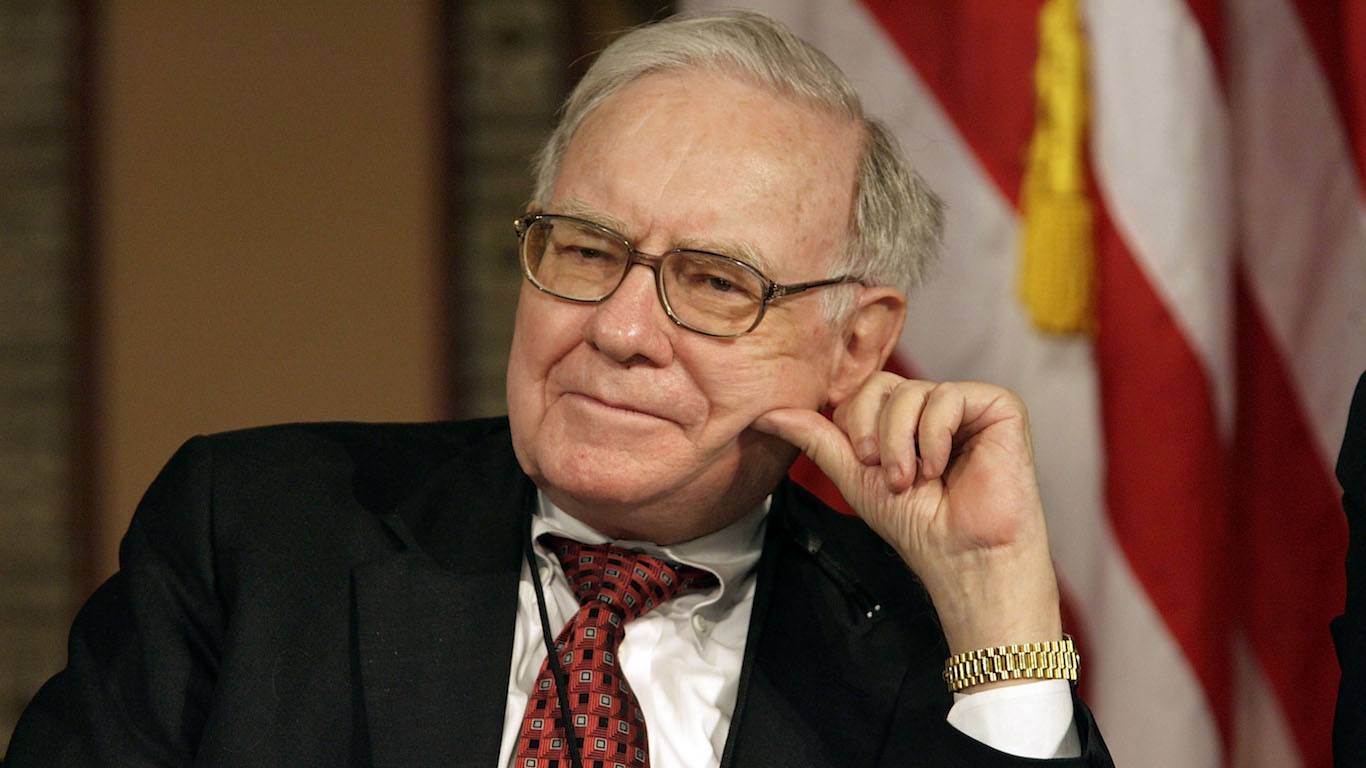
Warren Buffett paid a one-time tax to move $11.6 million from a traditional retirement account into a Roth IRA, according to tax records obtained by ProPublica, and by the end of 2018 the Roth held $20.2 million. ProPublica reported the conversion in June 2021, in its "Lord of the Roths" story built on leaked IRS data: "After paying the one-time tax, both men saw their Roth accounts soar." The other man was Ted Weschler, one of Buffett’s investment deputies. Buffett did not respond to the questions ProPublica sent him, and the records do not show which year he converted or what the tax came to, so this story does not guess at either.
What the records do show is the shape of the trade. Buffett had $20.2 million growing in an account with no required withdrawals for as long as he lives, because IRS rules spare Roth IRAs the required minimum distributions every traditional IRA owner faces. He was 88 at the end of 2018. Had that $20.2 million been sitting in a traditional IRA, the IRS table in force today would have required him to withdraw $1,474,453 in 2019 and pay ordinary income tax on it, with a larger withdrawal every year after. The door he walked through opened in 2010, when the cap that had limited conversions to people earning under $100,000 a year came off.
A conversion reads as a bet that the tax you pay now will be smaller than the tax you would pay later, on a bigger balance or at a higher rate. The limit of that reading is that nobody knows what the brackets will be in 2038, and Buffett has never said why he did it. What you can do is run the numbers under today’s rules.
Say you are 63, single, retired, and born in January 1963. That birth year matters: anyone born in 1960 or later takes a first required minimum distribution at 75 rather than 73, so your first RMD lands in 2038 and is set by the balance on Dec. 31, 2037. You have $800,000 in a traditional IRA and $400,000 outside it, in a brokerage account and cash, which throws off about $10,000 a year of interest and dividends. Social Security will be $3,000 a month, claimed at 67, the full retirement age for anyone born after 1959. Medicare starts at 65, in 2028. The math below holds the 2026 brackets, deductions, Medicare lines and the Social Security check flat in 2026 dollars (they all rise with inflation, so holding them still is fair), assumes 6% a year on invested money, and pays every conversion tax from the outside account the following April. A married couple gets roughly twice the room at every line; the single return shows the rules at their harshest.
What leaving it alone costs at 75
At 6% a year, $800,000 becomes $1,609,757 by the end of 2037. The IRS Uniform Lifetime divisor at 75 is 24.6, so your first RMD is $65,437, or $5,453 a month, 1.8 times the Social Security check. That withdrawal is ordinary income. It pushes 85% of your Social Security into the taxable column, and the federal bill for the year comes to $14,047, against zero without it.
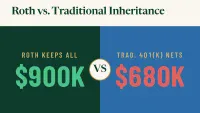
The divisor shrinks every year and the balance keeps growing, so the RMD rises: $85,214 at 80, $108,942 at 85, $133,255 at 90. From 76 on, the RMD alone carries your income past Medicare’s $109,000 surcharge line. Over the 16 years from 75 to 90 the forced withdrawals total $1,563,820, the federal tax on those years comes to $344,129, the Medicare surcharges add $32,852, and $1,582,004 is still in the IRA at 91 for your heirs, who must empty it within ten years at their own rates.
Buffett’s way: all of it at once
Convert the whole $800,000 in January 2026 and your 2026 return shows $810,000 of income, $793,900 of it taxable after the $16,100 standard deduction. The brackets do the rest:
| Slice of 2026 taxable income | Rate | Tax |
|---|---|---|
| First $12,400 | 10% | $1,240 |
| Next $38,000 | 12% | $4,560 |
| Next $55,300 | 22% | $12,166 |
| Next $96,075 | 24% | $23,058 |
| Next $54,450 | 32% | $17,424 |
| Next $384,375 | 35% | $134,531 |
| Last $153,300 | 37% | $56,721 |
Federal income tax: $249,700, plus $380 of net investment income tax on the interest and dividends, $250,080 in all, 31.3 cents on every converted dollar. $592,125 of the conversion is taxed at 32% or higher.
Then Medicare sends its own bill. Part B and Part D premiums are set by the tax return from two years earlier, so your 2026 income sets your premium for 2028, your first year on Medicare. At $810,000 of income you land in the top tier: $689.90 a month for Part B instead of $202.90, plus $91 a month on Part D, which is $6,936 extra for 2028. All in, Buffett’s way costs $257,016, and the outside account drops to $149,920.
Paying from the outside account is what makes it work. The full $800,000 goes into the Roth and grows to $1,609,757 by 75, every dollar of it free of tax and free of RMDs. Have the custodian withhold the tax from the IRA instead and only $549,920 is converted, which grows to $1,106,547 by 75, $503,211 less.
Four years, finished before Social Security
The second plan uses the four years before your first Social Security check, when the return is nearly empty. Fill the 24% bracket each year: a $207,875 conversion in 2026 and again in 2027, $209,925 in 2028 (the extra $2,050 standard deduction arrives at 65), and the $249,141 that remains in January 2029, part of which spills into the 32% bracket. Growth inside the IRA means $874,816 gets converted in total.
The federal tax over the four years is $178,165. Medicare charges for it too: each of those returns sits above $205,000, so your 2028 through 2031 premiums carry the $649.20 Part B tier and an $83.30 Part D surcharge, $6,355 a year, $25,421 in all. Total cost $203,586, or 20.4 cents per converted dollar, and the IRA is empty at 66, a year before Social Security starts.
Twelve years, finished before 75
The third plan converts $90,000 every January from 2026 through 2036 and the $90,344 that is left in January 2037, at 74. That is the last year it can be done. In 2038 the RMD must come out first, and the IRS says an RMD can never be rolled over, which rules out converting it.
For the four years before Social Security, a $90,000 conversion plus the $10,000 of interest is $100,000 of income, under Medicare’s $109,000 line, and the tax is $13,170 a year with a top rate of 22%. From 67, your $36,000 of Social Security joins the return, $30,600 of it taxable, and the same $90,000 conversion now costs $19,586 a year, in the 24% bracket, with income of $130,600. That crosses the first Medicare tier, so 2032 through 2039 carry a $284.10 Part B premium and a $14.50 Part D surcharge, $1,148 a year, $9,187 over eight years.
Twelve years of conversions move $1,080,344 into the Roth, because the growth gets converted too. The federal tax is $207,559, the total with Medicare is $216,746, or 19.2 cents per converted dollar, and the top rate never passes 24%. The Roth at 75 is the same $1,609,757 as in the other two plans: when the tax comes from outside money, the balance grows at the same 6% wherever it sits, so the plans differ only in what they cost.
The three plans side by side
| All at once, 2026 | Four years, by 66 | Twelve years, by 74 | |
|---|---|---|---|
| Dollars converted | $800,000 | $874,816 | $1,080,344 |
| Federal tax | $250,080 | $178,165 | $207,559 |
| Medicare surcharges | $6,936 | $25,421 | $9,187 |
| All in | $257,016 | $203,586 | $216,746 |
| Cost per converted dollar | 31.3 cents | 20.4 cents | 19.2 cents |
| Highest bracket touched | 37% | 32% | 24% |
| Roth at 75 | $1,609,757 | $1,609,757 | $1,609,757 |
| RMD at 75 | $0 | $0 | $0 |
Buffett’s way costs $40,270 more than the twelve-year ladder and $53,430 more than the four-year sprint, and it sends $250,080 to the Treasury in April 2027 that the ladder spreads out to 2038.
Where the plans are weak
The 6% assumption is a middle-of-the-road guess. Higher returns favor converting early, because more of the growth lands in the Roth; a bad first year after an $800,000 conversion is tax paid on money that no longer exists. Congress made the current rates permanent in 2025 and can change them again, and the slower plans leave more of your money exposed to that. The $6,000 senior deduction that trims the 2028 return ends after that year. And the ladder needs discipline: skip a year and an RMD arrives in 2038 on whatever is left.
The bottom line
A 63-year-old with $800,000 who wants what Buffett got, an account with no required withdrawals for life, can have it three ways. All at once in 2026 costs $257,016 and puts $153,300 in the 37% bracket. Four conversions before Social Security cost $203,586, top-tier Medicare premiums included. Twelve conversions of about $90,000 cost $216,746, never leave the 24% bracket, and finish at 74, the last year the IRS allows. All three end with $1,609,757 in a Roth at 75 and an RMD of zero, against a $65,437 first withdrawal that grows every year if you leave the IRA alone.
Contact [email protected] for any questions or corrections.
AJ spent 10 years writing about financial markets at The Motley Fool. His coverage centers on technology stocks and the broader macroeconomic trends, from interest rates to geopolitics, that shape where markets are headed next. AJ is drawn to the stories where big-picture economics and individual companies collide.