Hyperscalers Are About to Lean Into Broadcom Now That Nvidia Faces Serious Heat in The $160s

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

I added to my Broadcom (NASDAQ:AVGO | AVGO Price Prediction) position this week, and I plan to add more after the next earnings report. When a frontier AI lab decides an off-the-shelf GPU costs too much, Broadcom often gets the design work. With NVIDIA (NASDAQ:NVDA) under pressure, Barron’s reported Thursday that Broadcom stock got a boost from Nvidia’s loss. That headline means the market is starting to see what the filings have shown for months.
Why Custom Silicon Keeps Pulling Me Back
CEO Hock Tan made the case on the September call: “The lesson here is when you co-develop a chip that is optimized for your particular large language model workloads, you will outperform any GPU.” Broadcom shipped OpenAI’s first custom accelerator, Jalapeno, and began production shipments of TPU version 8i for Alphabet (NASDAQ:GOOGL) unit Google. It also signed a long-term deal to deliver multi-tens of billions of dollars of TPUs annually over the next several years. Management says custom XPUs often run workloads at less than half the cost compared to GPUs. Hyperscalers prioritize that kind of saving, and it is why I keep coming back.
Three Reasons Behind Every Purchase
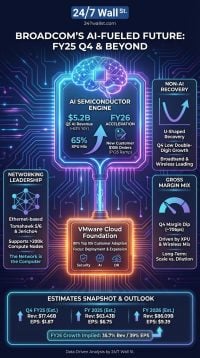
Growth that compounds. Fiscal Q3 AI semiconductor revenue reached $16.70B, up 221% YoY and 54% QoQ. Q4 guidance calls for ~$21.70B (+236% YoY). Management also says it has secured supply for about $115 billion of AI revenue in fiscal 2027 and sees a path to $230 billion in fiscal 2028.
Cash that rewards patience. Free cash flow hit $13.67B (46% of revenue), and cash grew to $23.98B. Broadcom also repaid $5.6 billion of longer-maturity debt in the quarter. The quarterly dividend of $0.65/share reflects the 15th consecutive annual dividend increase. At $364.36, the yield is only about 0.71%, so the income case depends on how fast the payout keeps rising.
A valuation I can live with. Broadcom expects to exceed $30 in earnings per share in fiscal 2028. Today’s price works out to about 12x that figure. Management has also beaten EPS estimates for nine consecutive quarters, which gives me some confidence in the forecast.
Why My Money Skips Arista
Arista Networks (NYSE:ANET) is the obvious alternative. Q3 revenue rose 58.45% YoY, its fastest growth since its IPO. The price is what keeps me out: a P/E of 74, an FCF yield of 1.63% and no dividend at all. Shares already rose 57.8% this year, compared with 5.85% for Broadcom. Arista’s own 10-K says it relies on Broadcom as its predominant merchant silicon vendor for switching chips. So when Arista sells a switch, Broadcom has usually already sold the chip inside it.
Risk I Track Every Quarter
Customer concentration is the biggest threat to this position. Broadcom serves six frontier-model customers, and management describes only four of them as able to fund themselves. Broadcom also set up financing vehicles for Anthropic and OpenAI that may carry residual-value guarantees, and the CFO gave no maximum exposure. Gross margin should fall to about 73%, down from 78% a year ago. I still hold my thesis because operating margin reached a record 67.9%, and the Google agreement runs for years.
What Could Extend Broadcom’s Custom Silicon Run
Tomahawk 7 has taped out as the industry’s first 200-terabit-per-second Ethernet switch. Management expects AI networking to grow as fast as XPUs. My next update is December 9, 2026. As long as the hyperscalers keep designing their own chips, the custom silicon thesis for Broadcom remains intact (we reverse-engineered what the biggest tech winners looked like early and put the pattern in a free playbook here).
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.