Taiwan Semiconductor Just Became Even More of an AI Anchor On Nvidia’s -25% Plummet

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
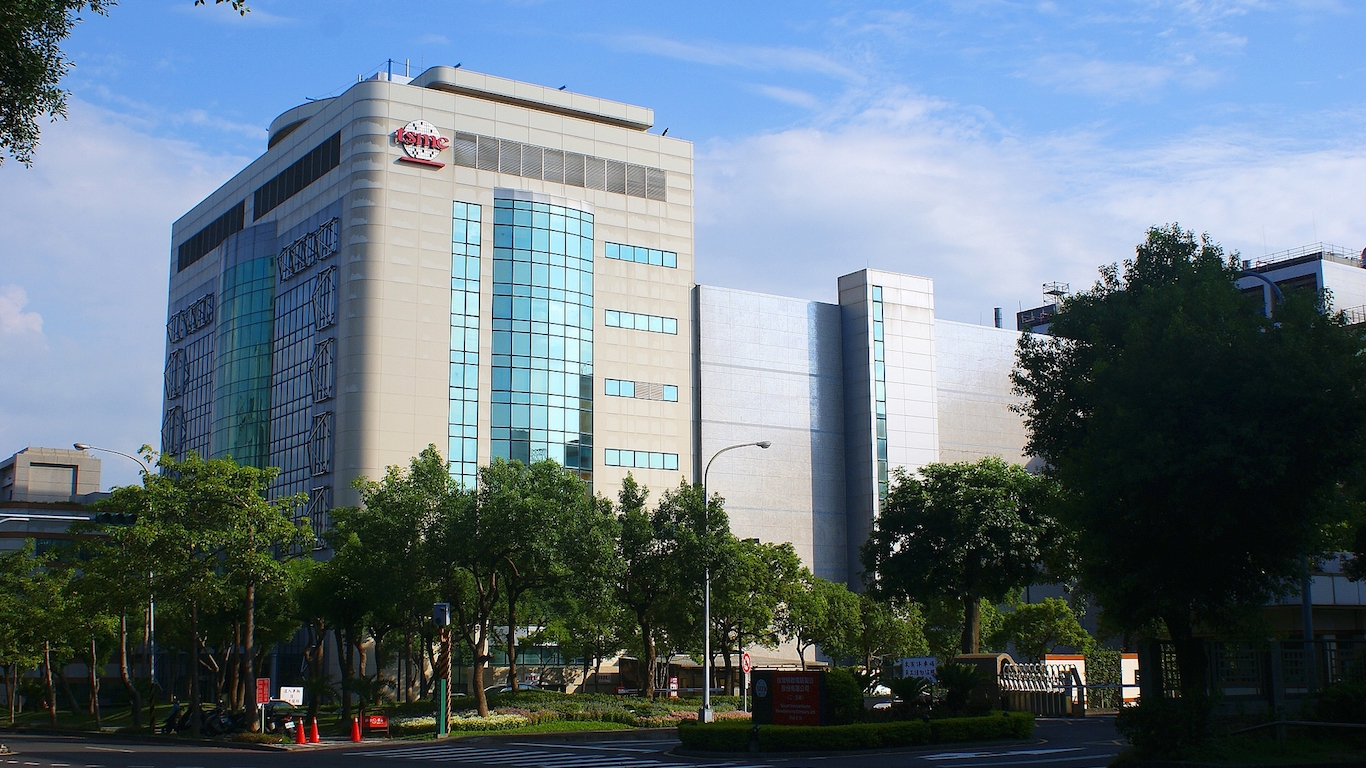
I added to my Taiwan Semiconductor (NYSE:TSM | TSM Price Prediction) position again this week, and every new data point reinforces my conviction to keep buying. Over the past month, Nvidia (NASDAQ:NVDA) shares fell 27.28%. My foundry shares slipped 8.87% over the same stretch. That gap shows me which company actually holds the AI build-out together.
Nvidia’s slide sped up after reports that Jensen Huang had an affair with a woman U.S. officials reportedly concluded was “a Chinese intelligence asset”. Then came his resignation as CEO. As investors lose trust in a single chip designer, I expect more of them to look at the picks-and-shovels companies that supply the whole industry (we covered seven of those AI suppliers, from power to cooling, in a free report you can grab here).
Why I Keep Clicking Buy
TSMC makes the chips, so it gets paid for every wafer no matter which designer wins. The chief executive put it plainly on the October call: “Therefore, all the AI players are working with TSMC.” He also said “Demand is still far above our capability to supply today.” When a company holds the rarest capacity in technology, I want to own it no matter whose logo ends up on the chip.
Three Receipts Behind My Conviction
One key factor is how much of the leading edge TSMC controls. Nodes of 7nm and below made up 79% of wafer revenue in the third quarter. The 2nm share rose to 8% from 3% one quarter earlier, and high-performance computing accounted for 68% of revenue.
Growth keeps showing up in earnings as well. Third-quarter EPS came in at $4.60 against a consensus of $4.46. Management raised its full-year forecast to about 44% revenue growth in U.S. dollars, up from slightly above 40%. October revenue rose 59.7% year over year.
I also still get a reasonable price and a growing income stream. Shares trade at a forward P/E of 18. The quarterly ADR dividend rose from $0.683789 in April 2025 to $1.366286 declared on November 10, 2026. Management also reaffirmed its goal of “a sustainable and steadily increasing cash dividend per share”.
Why My Money Goes Here Instead of ASML
Plenty of readers would reach for ASML (NASDAQ:ASML) first. It costs more: 23 times forward earnings against 18 for TSMC. Its third-quarter gross margin was 57.5%, compared with TSMC’s 66.4%. Its operating margin was about 44.4%, against TSMC’s 58.7%. Over five years, TSMC shares returned 270.16%, while ASML returned 84.9%. ASML makes money when chipmakers spend on new equipment, and that spending runs in cycles. TSMC earns money on every wafer it ships. I would rather own the customer that keeps those tool orders coming.
Risks I Track Every Quarter
Taiwan is the risk I take most seriously. European auditors wrote that “cross-strait tensions between China and Taiwan represent a source of persistent insecurity for the sector.” Margins also face pressure. Gross margin fell 1.3 percentage points from the prior quarter, and management expects drag from overseas fabs to grow to 3%–4%.
Neither risk has changed my thesis, because TSMC is spreading its exposure. Its second Arizona fab should begin volume production in the third quarter of 2027, and a Japan fab is scheduled for 2028. Even with that drag, fourth-quarter gross margin guidance of 65% to 67% still stands above ASML’s current margins.
What Keeps the Buy Button Active
N2 capacity should more than double in 2027, and A14 volume production starts in 2028. When analysts asked about AI accelerator growth, the chief executive answered: “It probably will be higher.” Chip designers will keep trading places at the top of AI, and every one of them will still need TSMC to build its chips.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.