Nebius Will Reach True Profitability Just Before CoreWeave But Here’s Who Grows Faster After That

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Nebius Group (NASDAQ:NBIS | NBIS Price Prediction) and CoreWeave (NASDAQ:CRWV) reported Q3 results two days apart, and both now have target dates for profitability. Nebius targets pre-tax breakeven in the fourth quarter of 2027[1]. CoreWeave expects positive adjusted net income in the first half of 2028[2]. The bigger question is what each company does after it gets there.
Prepayments Fuel Nebius While Repricing Lifts CoreWeave
Nebius posted revenue of $980.8M, up 571.3% YoY[3]. That jump looks a bit better than it is because roughly $325M[3] came from a one-time asset-light partnership. The underlying demand is still real. Q3 deals closed above $25 million per megawatt[1], and prepayments covered more than 100% of the capex needed to bring that capacity online. In practice, customers are paying for Nebius’s expansion. CEO Arkady Volozh put it plainly: “Our customers are paying more, they pay earlier, and they’re committing for longer.”[1]
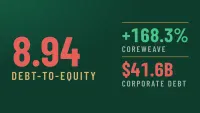
CoreWeave’s revenue rose 168.3% to $3.661B[4], so its percentage growth is slower but the dollar base is far bigger. Its edge is older hardware. Pricing on Ampere and Hopper GPUs rose 30% to 50% quarter over quarter[2], which means GPUs it already paid for are earning more. Interest expense of $846M[4] still pushed the quarter to a $709M net loss.
Both companies sit directly in the AI infrastructure trade, and they are far from the only names profiting. We highlighted seven suppliers supporting the data-center expansion, from electricity to cooling and networking, in a free report you can grab here.
| Business Driver | Nebius | CoreWeave |
|---|---|---|
| Profit Milestone | Pre-tax breakeven, Q4 2027 | Adjusted net income, 1H 2028 |
| Funding Lever | Customer prepayments | Contract-matched term loans |
| Software Layer | Token Factory inference | Forge, managed inference |
Nebius Grows Faster in Percentage Terms. CoreWeave Grows Faster in Earnings.
Nebius guided 2027 revenue to $12-13B, roughly 4x 2026[3]. That is about the size of CoreWeave’s full-year 2026 guidance of $13.0-$13.3B[4]. A smaller base makes rapid percentage gains easier, and Nebius plans to supply most of that growth from its own sites.
CoreWeave’s advantage is earnings leverage. More than 130,000 GPUs[2] come off contract in 2027, and re-signing them at today’s prices could add revenue approaching $4 billion a year with no new capex. Management expects EBITDA less interest to more than double in 2027[2]. In CFO Nitin Agrawal’s words, “That is the path to earnings.”[2]
Owned Sites and GPU Renewals Will Decide 2027
The key question is whether Nebius’s owned sites in Alabama, Missouri and Finland come online on time. Colocation delays have already pushed New Jersey capacity to Q2 2027[3], and 2027 capex of $40-45B gives the company little room for another slip. For CoreWeave, keep an eye on Q4 interest expense, guided at $1.05-$1.15B[4], and on whether renewal pricing holds up.
Why I Lean Toward CoreWeave for Earnings and Nebius for Growth
I find CoreWeave’s path to profits easier to trust. Hardware it has already paid for is getting revalued higher, and that falls almost straight to the bottom line. The balance sheet worries me, though: liabilities of $87.456B[4] against equity of just $4.025B.
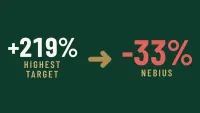
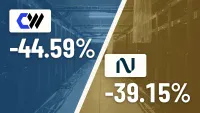
Nebius is the stronger growth story, and customer prepayments make that growth more credible. The market already seems to agree, pricing Nebius at $27.81 billion against CoreWeave’s $23.24 billion. After a 24.26% drop over the past week, I would want to see Nebius’s owned sites ramp on schedule before deciding that premium is justified. Nebius offers the stronger growth profile, while CoreWeave offers the closer path to visible earnings.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.