Rocket Lab’s $57 Share Price is a Highly Attractive Entry Point For Forward-Looking Bulls

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
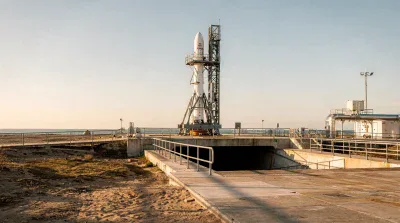
Rocket Lab (NASDAQ:RKLB | RKLB Price Prediction) has turned into a full-stack space company. It flies Electron and HASTE, makes Flatellite spacecraft and has already took over Mynaric and Motiv. A deal for Iridium Communications (NASDAQ:IRDM) is still pending. CEO Peter Beck put it this way: “Our end-to-end space strategy is delivering exactly as designed.”[1] The stock has moved the other way. Shares are down 17.76% year to date at $57.37, about 62% below the 52-week high of $151. Here’s how Rocket Lab could hit $100 in 2027.
Wall Street Sees 62% Upside From Today’s Price
The average analyst target is $93.10, which implies 62% upside. Analysts carry 5 Strong Buy and 13 Buy ratings against 4 Holds and zero Sells. Consensus has revenue climbing from $980 million in 2026 to $1.34 billion in 2027, growth of roughly 37%.
Rocket Lab has also exceeded revenue estimates for four straight quarters. In Q3, revenue came in at $267.83 million[1] against a $257.18 million consensus, up 72.71% from a year earlier. GAAP EPS of -$0.12[1] missed the -$0.0665 estimate, but most of that gap came from one-time charges: a $27.26 million loss on debt repayment and $21.34 million in Iridium transaction costs.
Can Rocket Lab Really Hit $100? Let’s Do the Math
Rocket Lab isn’t profitable yet, so price-to-sales is the better metric. At a $36.26 billion market cap, the stock trades at about 27x 2027 revenue estimates. At $100, that multiple rises to roughly 47x. That’s a premium price, and the backlog helps support it. Backlog hit a record $3.57 billion[1], up 52% in one quarter.
Four catalysts could push Rocket Lab to $100:
- Neutron pricing power: Neutron hasn’t flown yet, but its first 16 launches are booked[2] at a base price of $70 million. The next open slots are in the 2030s[2]. Management expects Neutron to become a 50%-plus[2] non-GAAP gross-margin business.
- Defense spending: The FY2027 defense budget sets aside $59.7 billion for space-based systems. Rocket Lab already holds an $816 million SDA contract, the largest in its history.
- Iridium: The deal is fully financed, and management says it would add strong cash flow as soon as it closes.
- Higher launch prices: Beck expects “price increases across Electron and HASTE.”[2]
Rocket Lab’s History Says a 74% Gain Is Within Reach
A move to $100 would require a 74% gain. Rocket Lab has done more than that before: shares roughly quadrupled in 2024 and are up 252.4% over five years. With a beta of 3.176, the stock tends to move hard in both directions. The main risks are dilution (the company issued 36.8 million shares[2] through its at-the-market offering) and any further Neutron delays.
Is $100 Realistic? Here’s My Take
Reaching $100 would mean a 74% gain from here. Analysts already see 62% upside. Revenue keeps beating estimates, the backlog is at a record, and Neutron is sold out into the next decade. If Neutron flies smoothly in 2027 and the Iridium deal closes, $100 looks achievable. Gains of that magnitude are rare, which is why we studied what the biggest tech winners looked like early and put the pattern in a free playbook here. This is the plan for how Rocket Lab could post an outsized gain in 2027.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.