Billionaires Split on Lam Research. Is the Stock a Buy, Sell or Hold?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
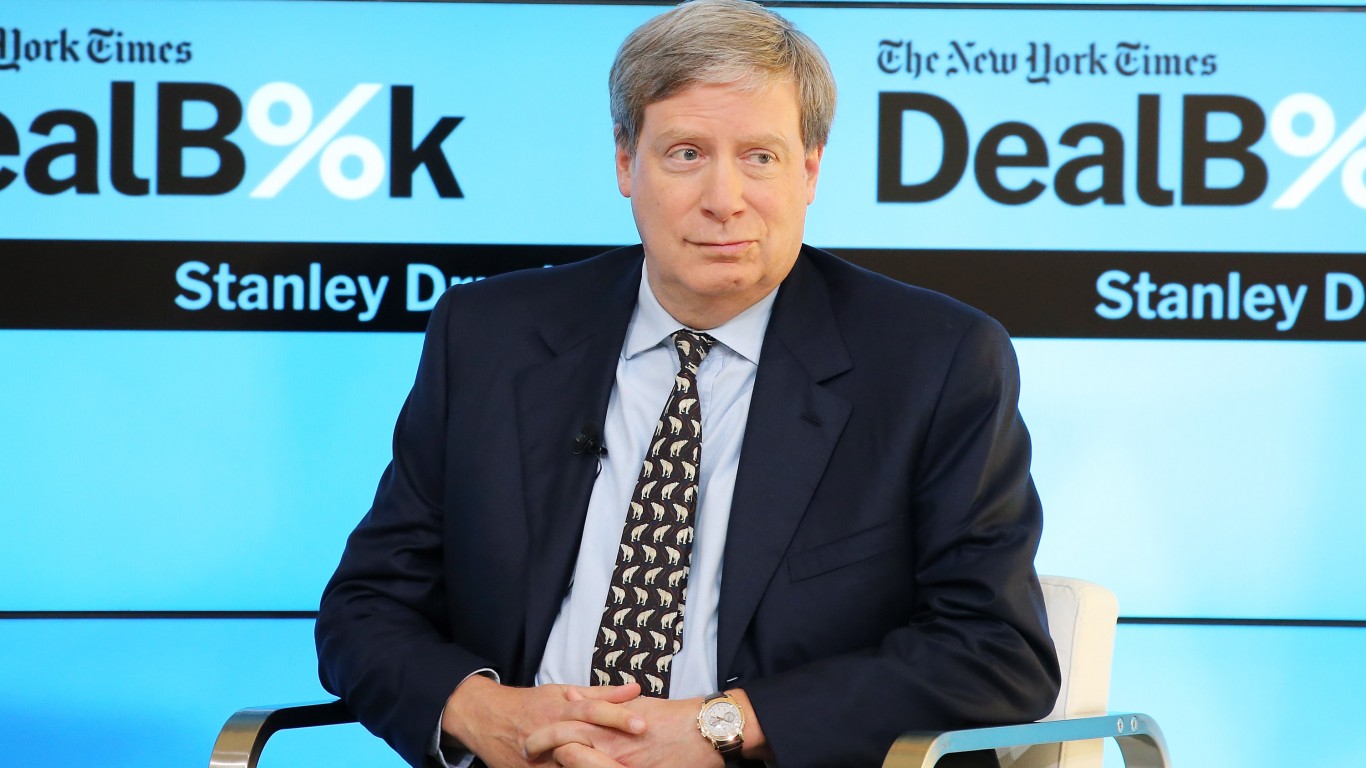
Lam Research (NASDAQ:LRCX | LRCX Price Prediction) looks attractive at $210.69, even though two billionaires have split on it. In 13F filings covering holdings as of Sept. 30, 2026, and reported Nov. 16, 2026, David Tepper’s Appaloosa added 242,500[1] shares to finish the quarter with 625,000[2]. Stanley Druckenmiller’s Duquesne Family Office sold its entire 43,600-share stake. So what are investors to do?
Lam makes the deposition and etch tools chipmakers use to form transistors, memory cells, and interconnects, and it sells spares, upgrades, and services to a large installed base. AI demand raised September-quarter revenue to $8.22 billion[3], up 54.4% year over year. Even so, shares have fallen 22.6% over the past month.
Tepper’s Chip-Equipment Push Rides a $200 Billion Spending Cycle
The traits that showed up early in past semiconductor winners, before the monster runs, are the subject of our free Next Nvidia Playbook.
Tepper’s Lam addition came alongside a new 225,000-share stake in Applied Materials (NASDAQ:AMAT) and 15,000 more shares of ASML (NASDAQ:ASML), for a total of 65,000. Lam management’s outlook supports Tepper’s bullish thesis. It projects calendar 2027 wafer fabrication equipment spending of “more than $200 billion,” with customer visibility “through 2028.”
Lam’s execution keeps improving. Non-GAAP EPS of $2.20[3] beat the $2.1771 consensus estimate, and operating margin exceeded 40% for the first time. December-quarter guidance calls for $8.60 billion[3] in revenue and $2.33 in EPS. A forward P/E of 23 and a PEG ratio of 0.983 look cheap for that growth.

China Exposure and Supply Bottlenecks Threaten Momentum
China supplied 35%[4] of revenue last quarter, up from 26% in the June quarter. That leaves Lam exposed to export controls, and management expects China’s share to fall “meaningfully”[4] this quarter. Supply-chain constraints also trimmed December guidance.
The size of the earnings beats is shrinking, from 8.10% in the June quarter to 1.05%[3]. With a trailing P/E of 31 and a beta of 2.01, the stock can fall hard if orders cool.
Druckenmiller’s Exit Makes a Case for Waiting
Druckenmiller also sold all 118,300 of his Entegris (NASDAQ:ENTG) shares. A full exit can reflect position sizing, profit-taking, or a shift in theme. Lam shares trade below both the $277.66 50-day average and the $283.87 200-day average. Patient investors may want to see the delayed revenue ship in the March quarter and the China mix settle first.
Analysts See Plenty of Upside After a Steep Monthly Slide
The average analyst target of $362.10 suggests 71.7% upside from the most recent close. Targets carry no guarantee, but the coverage is broad.

Lam is up 23.1% year to date, compared with 7.2% for the S&P 500. Over the past month, it has lost 20.2%, while the index has slipped 4.2%.
Tepper’s Side of the Split Wins This Debate
The pullback has knocked the valuation down while the fundamentals keep getting stronger. Revenue growth sped up from 22.14%[5] to 54.38% over four quarters. Free cash flow reached $3.24 billion[3] last quarter.
Further gains depend on the next quarterly report and 2027 spending plans. If the December quarter lands near guidance and March picks up the delayed shipments, the gap to analyst targets should start to close.
China export restrictions are a genuine concern. Still, Lam beat estimates even with China at 35%[4] of revenue, and memory and foundry demand elsewhere is driving the growth. A sharp cut to 2027 spending forecasts would undercut this view.
The selloff offers investors an opportunity to get Tepper’s preferred equipment name at a lower price, with a record growth cycle still underway.


Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.