Jim Cramer Told Nvidia’s Interim CEO “the Cheapest Stock in the World Is Yours”

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
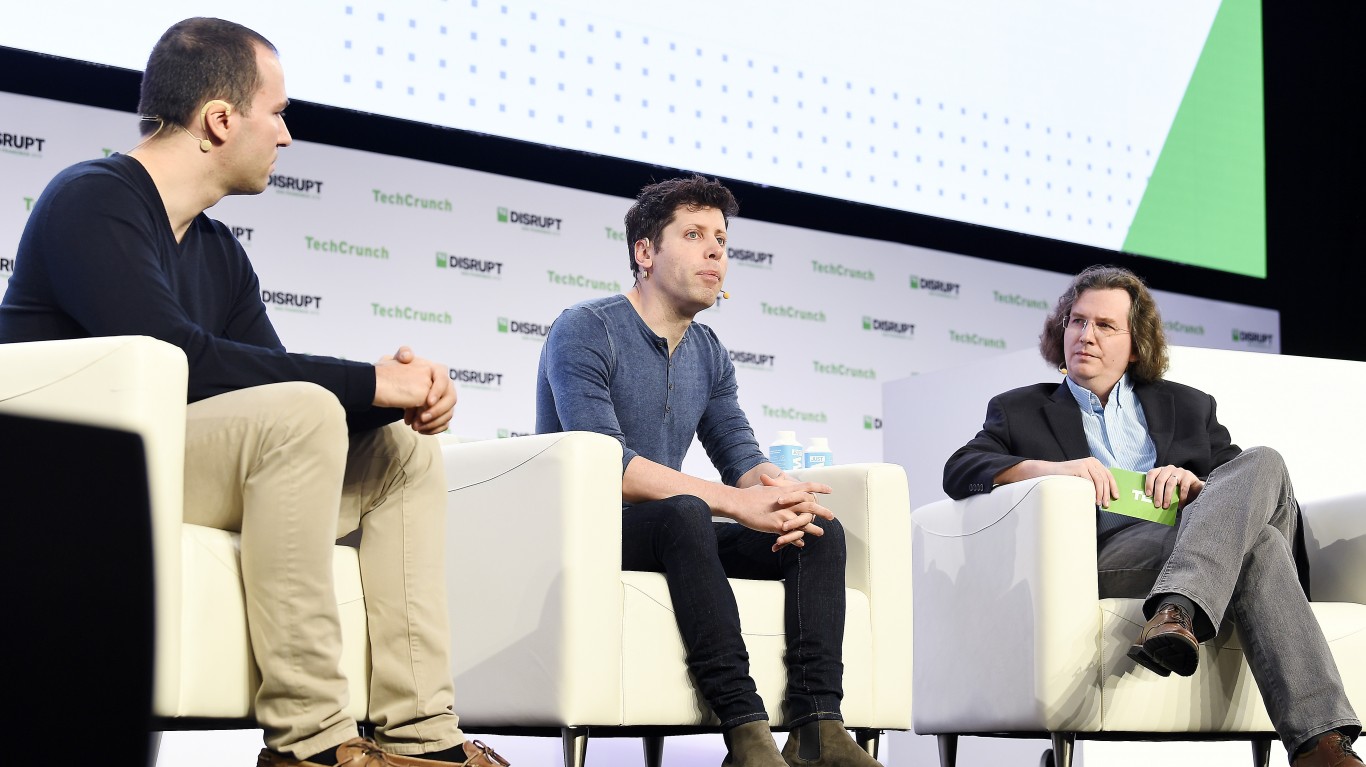
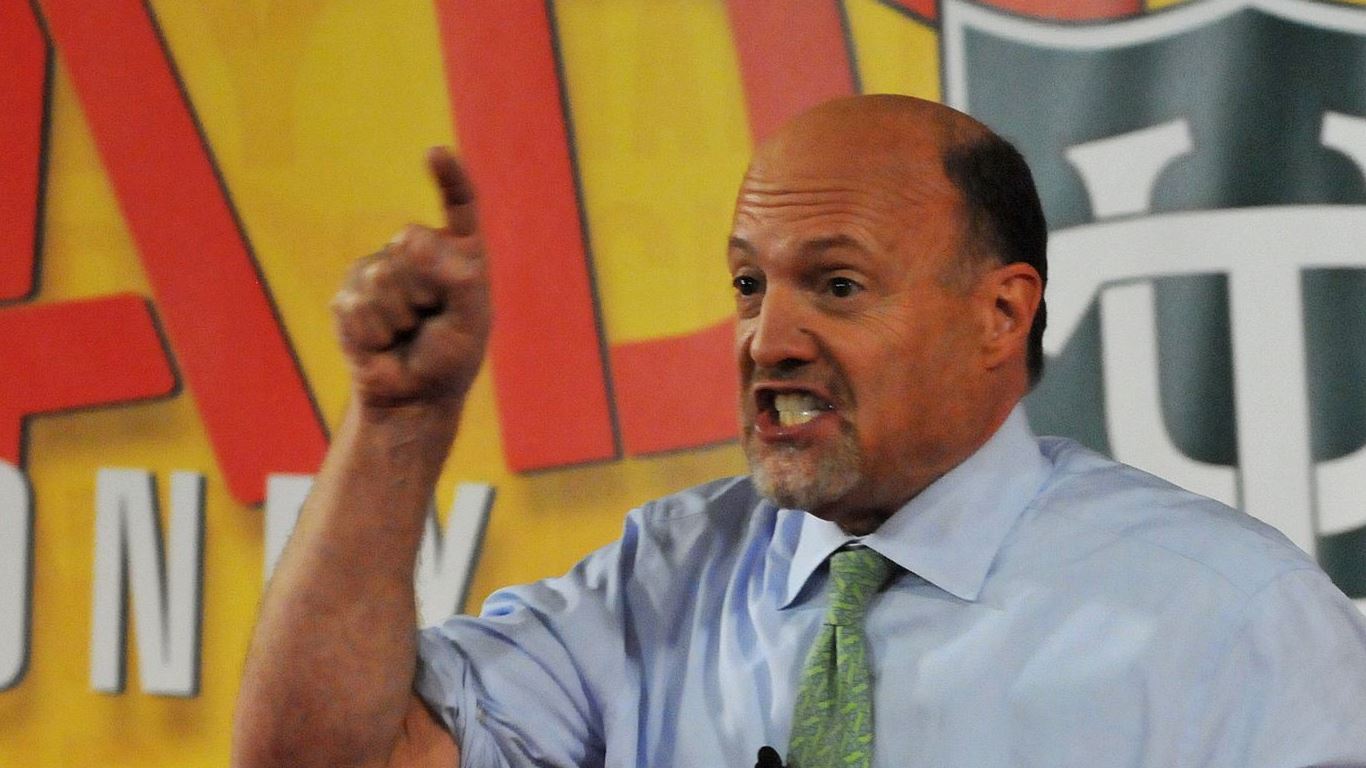
About two hours after its fiscal third-quarter report, NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) sent its interim CEO, Colette Kress, onto Mad Money. Jim Cramer opened with a pitch he said he had made to her many times before: “the cheapest stock in the world is yours.”
This was her first TV interview since Jensen Huang resigned. His resignation took effect November 11, and Kress said the board will not bring him back.
The stock closed at $155.46, down 0.44%, and then traded at $162.94 after hours at 7:59 p.m. ET, up 4.81%. That jump came from the earnings report, which was released before the interview aired, and it leaves the shares down 27.4% over the past month.
Kress dodged the valuation pitch and answered instead with a buyback figure that doesn’t match what NVIDIA filed.
What Kress Committed To on Mad Money
Cramer asked why NVIDIA should loan “aggressive amounts of money” to neoclouds when it could buy its own shares. Neoclouds are smaller cloud companies that rent out GPU capacity. Many borrow to build them, so financing them adds credit risk to NVIDIA’s balance sheet. The same expansion feeds a wider set of suppliers. These span power, cooling, and networking, which we profiled in a free report on seven AI infrastructure names that aren’t chipmakers: here.
Kress said the board added more than $150 billion of authority, put the total at $277 billion, and said NVIDIA expects to finish “to the end of 2027.”
The filings show a $150 billion increase in September and $227.3 billion remaining as of October 25. The plan runs through fiscal 2028, which ends in early 2028, so the filed numbers are the ones that count.
Why the Cash Supports a Buyback This Size
Free cash flow reached $43.8 billion in the quarter and $113.7 billion over the past nine months. Operating cash flow rose to $48.3 billion from $23.8 billion a year earlier, partly because federal tax payments fell at different times.

NVIDIA returned a record $28.1 billion to shareholders in the quarter. Still, the buyback yield is only 1.06% against a $3.75 trillion market value, so even record spending retires a small piece of the shares.
The stock trades at 11 times forward earnings with a PEG ratio (P/E divided by expected growth) of 0.23. Amazon (NASDAQ:AMZN) trades at 26 times. A multiple that low also suggests investors doubt that peak earnings will last.
Where the Guarantee Risk Sits
Cramer cited an analyst estimate that NVIDIA could be on the hook for about $530 billion in guarantees. Kress put the figure at about $118 billion, mostly for land, power, and a shell foundation for a 4.5-gigawatt site she called Portsmouth.
The CFO commentary lists maximum exposure of $118.0 billion. It includes up to $105 billion tied to SB Energy, and says NVIDIA has paid nothing on its guarantees so far. A guarantee means NVIDIA pays if a partner can’t, and nearly all of this exposure rides on one counterparty’s project. That clean payment record likely reflects easy financing conditions, so it says little about how the guarantees would hold up if credit tightened.
What the Numbers Mean for NVIDIA Stock Now
Third-quarter revenue reached $115.8 billion, up 103%, and guidance calls for $130.0 billion, plus or minus 3%. After the monthly slide, the valuation sits low relative to that cash generation.

Cramer is right that buybacks serve shareholders better than loans to customers, but the guarantee book and Kress’s inconsistent figures explain why the multiple stays low, and both can be checked in the filings.

The test is the quarterly 10-Q filing. If it shows guarantee exposure above $118.0 billion, the bullish argument weakens. The next dated event is the $0.25 dividend for holders of record on December 2, payable on December 23, 2026.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.