NVIDIA Just Cut Its Intel Stake. Intel Is Down 40% in a Month. Where’s the Stock Headed?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
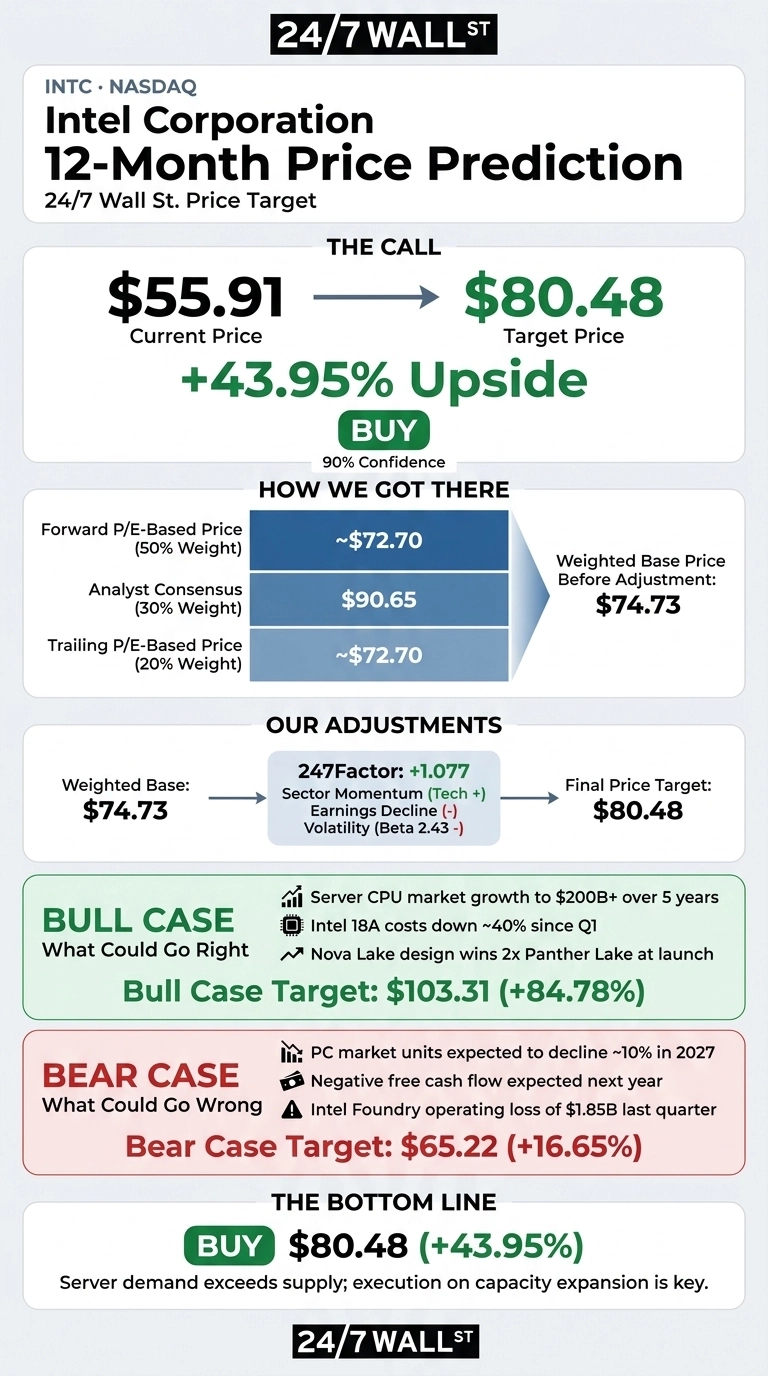
Over the past month, Intel (NASDAQ:INTC | INTC Price Prediction) has lost 39.45%, and a new regulatory filing has added more selling pressure. The 24/7 Wall St. price target for Intel is $80.48, which implies 43.95% upside from the model’s reference price of $55.91.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $55.91 |
| Price Target from 24/7 Wall St. | $80.48 |
| Upside/Downside | 43.95% |
| Recommendation | BUY |
| Confidence Level | 90% |

Intel earns a buy rating with high confidence from the model. In my view, the selloff has priced in a weak PC market and a partial exit by NVIDIA (NASDAQ:NVDA) but gives little credit to a data center business that grew 78%[1] last quarter.
Intel’s revenue problem is near-term weakness in PCs. Its server business is limited by how much it can produce, and demand still exceeds supply.
NVIDIA’s 13F and a PC Slump Sent Intel Reeling
NVIDIA filed a 13F on Nov. 16. It showed 161,082,488 Intel shares at Sept. 30, down from 214,776,632, a 25% cut to the stake NVIDIA built through its $5.0 billion[2] purchase.
Barron’s linked the move to Jensen Huang, who resigned as NVIDIA’s chief executive on Nov. 12. Intel shares fell 8.37% this week and were at $54.40 premarket. Even after the drop, the stock is still up 47.43% year to date. Its 52-week range runs from $32.89 to $142.35.
Third-quarter revenue rose 20.95%[1] to $16.513 billion. Non-GAAP EPS came in at $0.52[1], ahead of the $0.3953 consensus. The fourth-quarter outlook was weaker: revenue of $15 billion to $16 billion[1], non-GAAP EPS of $0.25, and client revenue expected to fall greater than 20% sequentially[3].

Why Bulls See $103 or More
The bull case reaches $103.31. Intel’s management expects the server CPU market to grow from $40 billion to more than $200 billion over five years[3], driven by agentic AI. Intel 18A costs have fallen approximately 40% since Q1[3]. Nova Lake design wins are expected to be twice those of Panther Lake at launch[3].
Intel also has about $54 billion[3] in cash and short-term investments to fund the expansion. The chief financial officer, David Zinsner, said Intel has “line of sight to long-term double-digit revenue growth with meaningful leverage and improving margins.”[3]

Cash Burn and a PC Recession Could Hold Intel Near $65
The bear case is $65.22. Management expects the PC market to shrink by roughly 10%[3] in units in 2027 and does not expect positive free cash flow next year. Intel Foundry lost $1.85 billion[1] last quarter.
Analysts lean cautious, with 36 Hold ratings against 11 Buys. The weak GAAP numbers reflect a non-cash item. Trailing diluted EPS of -$2.35 includes a non-cash charge of $12.53 billion[4] on escrowed shares. Zinsner described 2027 as an investment year aimed at a “20% return.”[3]

Intel Trades Richer Than Micron and Close to AMD
Advanced Micro Devices (NASDAQ:AMD) competes with Intel directly in server and PC CPUs. AMD trades at a lower forward multiple than Intel and is growing revenue roughly twice as fast, with data center revenue up 97%.
Micron Technology (NASDAQ:MU) belongs in the comparison because high memory prices are a main cause of Intel’s PC slowdown. Micron trades at a single-digit forward P/E even with revenue up several-fold.
Against these two peers, Intel’s 35x multiple only makes sense if its earnings recover. That leaves our target reasonable, though it depends on Intel executing.
| Company | Forward P/E | Quarterly Revenue Growth YoY |
|---|---|---|
| Intel | 35 | 20.9% |
| AMD | 32 | 44.7% |
| Micron | 4 | 379.3% |
Server Demand Supports Our BUY Rating
The 24/7 Wall St. price target is $80.48, with a buy rating and 90% confidence. What decides it for me is server demand that still exceeds Intel’s supply.
This case strengthens if Intel adds substrate and Intel 3 capacity on schedule. The case weakens if the PC inventory correction runs past the second quarter of 2027 or if Intel 18A wins few outside foundry customers. At these levels, the model’s 43.95% implied upside reflects that view.
Looking further out, this is the price the 24/7 Wall St. model projects Intel could trade at if current growth trends and market conditions continue.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $80.48 |
| 2027 | $94.57 |
| 2028 | $111.13 |
| 2029 | $130.59 |
| 2030 | $153.46 |
Intel would need to keep executing on its current strategy for these projections to hold.
The 2026 figure is our 12-month target. The later years follow the model’s five-year base case, which ends at $153.46 in November 2031. Results could swing well above or below these levels depending on whether Intel 14A reaches production on time and whether foundry losses narrow.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.