Buying a Car Wash to Fund Your Retirement? Nobody Mentions the Water Bill.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
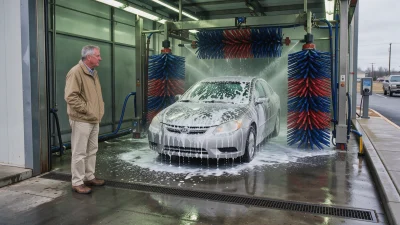
The listing describes a business that seems to run itself. Cars roll through an automated tunnel, customers pay at a booth or through an app, and one attendant handles the lot. For someone in their late 50s or 60s, it reads like a way to turn savings into monthly income without working a second career. What the listing leaves out is the meter, and you will be paying it every month.
Utility Bills and Repairs Hit Before Any Profit
A car wash buys water, pays to send it down the drain, and pays again to heat it and pump it. In many places, sewer charges are based on how much water you use, so every gallon is billed twice. Electricity runs the pumps, blowers, vacuum cleaners and conveyor. Those costs rise with volume, so a busy summer brings bigger bills along with the bigger revenue.
Then come the costs that never show up in a pitch deck:
- Cleaning chemicals: soaps, waxes, tire shine and spot-free rinse are bought again and again, and suppliers can raise prices.
- Maintenance and breakdowns: brushes wear out and controllers fail. If the tunnel goes down on a sunny Saturday, you take in nothing on your best day while the mortgage and utilities stay the same.
- Insurance: you are exposed to claims that the equipment damaged a customer’s car, plus the usual premises liability.
- Wastewater rules: local governments control what a car wash can send into the sewer. That can mean settling tanks that have to be pumped out, reviews, and paying for upgrades when the rules change.
Membership Chains Decide What You Can Charge
Chains built around unlimited monthly memberships compete on price and convenience. They sign customers up for recurring plans, use apps and license-plate readers to move cars through faster, and can open new tunnels close to existing washes. If a chain opens down the road, the price you can charge for a single wash may stop being your call. Before you buy, check local zoning and permit records for new car washes nearby, and ask the seller whether membership numbers are rising or falling.
Putting Your Retirement Savings Into One Business
Your age group is where the money sits. Households aged 55 to 69 held 41%[1] of U.S. household net worth in the second quarter of 2026[1], according to the Federal Reserve’s Distributional Financial Accounts. The same group held 49.5%[1] of all defined contribution retirement plan assets, the 401(k)-type accounts many buyers would tap to pay for a business.
A car wash is illiquid. You can sell part of a stock fund to pay a medical bill, but you can’t sell part of a tunnel. The business also has to keep covering your living costs in a bad year. Average annual household spending was $81,905 in 2025, according to the Bureau of Labor Statistics Consumer Expenditure Survey. If the appeal is a monthly check rather than running a business, there are smoother ways to build one from the savings you already have (we laid out the mix, the payout calendar, and the withdrawal order in a free guide here).
Using retirement accounts to fund a business you control adds tax risk. IRS Publication 590-A for tax year 2025 warns that "if your IRA is invested in nonpublicly traded assets or assets that you directly control, the risk of engaging in a prohibited transaction in connection with your account may be increased." If that happens, the account "stops being an IRA as of the first day of that year" and is treated as having paid out all its assets to you at fair market value. That can create a large tax bill in one year. Before any retirement money moves, have a retirement plan attorney and a CPA review the structure.
Get the Seller’s Utility Bills and Repair Records Before You Make an Offer
Ask for several years of the seller’s actual water, sewer and electric bills, along with maintenance logs, chemical invoices, insurance claims and any wastewater reviews reports. Check them against the profit-and-loss statement month by month. If the bills don’t line up with the reported car counts, or the seller won’t hand them over, you’ve found out what you need to know before putting any of your retirement savings at risk.
Contact [email protected] for any questions or corrections.
Austin Smith is a financial publisher with over two decades of experience as an investor, analyst, and advisor. He covers stocks, ETFs, Artificial intelligence and personal finance for 24/7 Wall St. Previously, he spent over a decade at The Motley Fool as a senior editor for Fool.com, portfolio advisor for Millionacres, and launched The Ascent to help reader take control of their personal finances.
His work has been featured on Fool.com, NPR, CNBC, USA Today, Yahoo Finance, MSN, AOL, Marketwatch, and many other publications. He is as an advisor to private companies, and co-hosts The AI Investor Podcast with Eric Bleeker.
When not looking for investment opportunities, he can be found skiing, running, or playing soccer with his children. Learn more about Austin's investment approach here.