IonQ Has 2 Opportunities That Could Transform Its Long-Term Growth Story

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
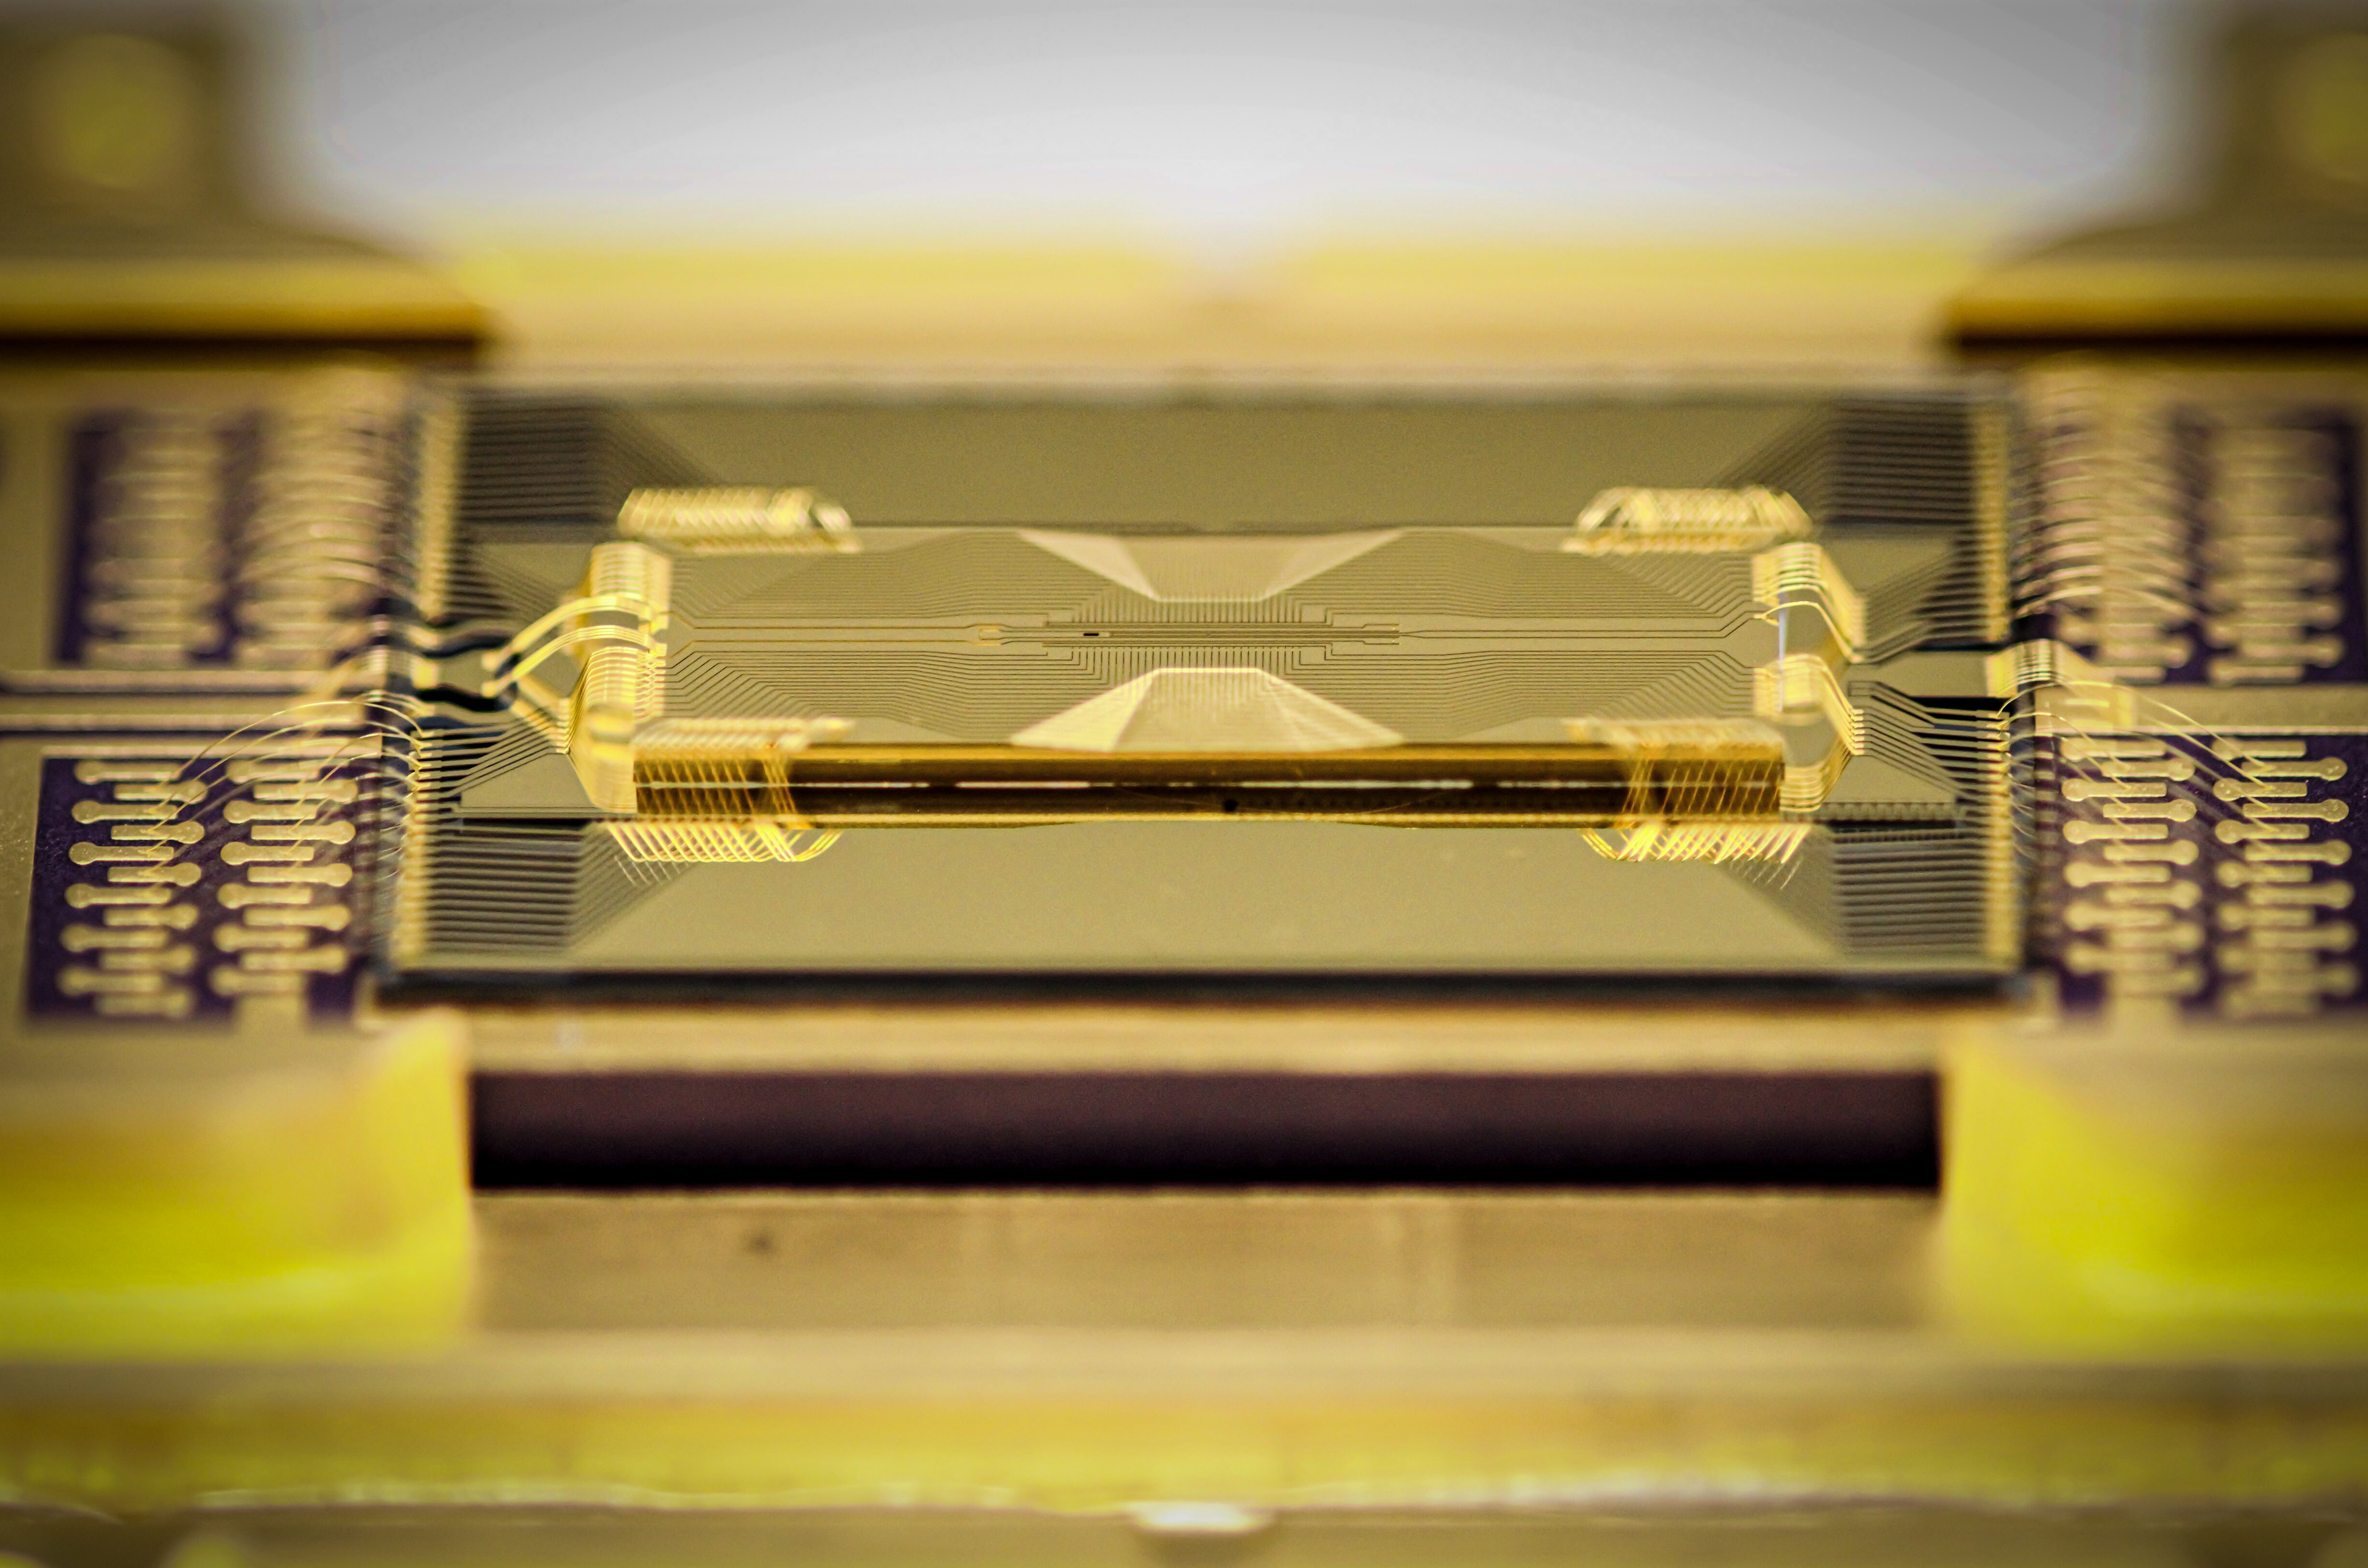
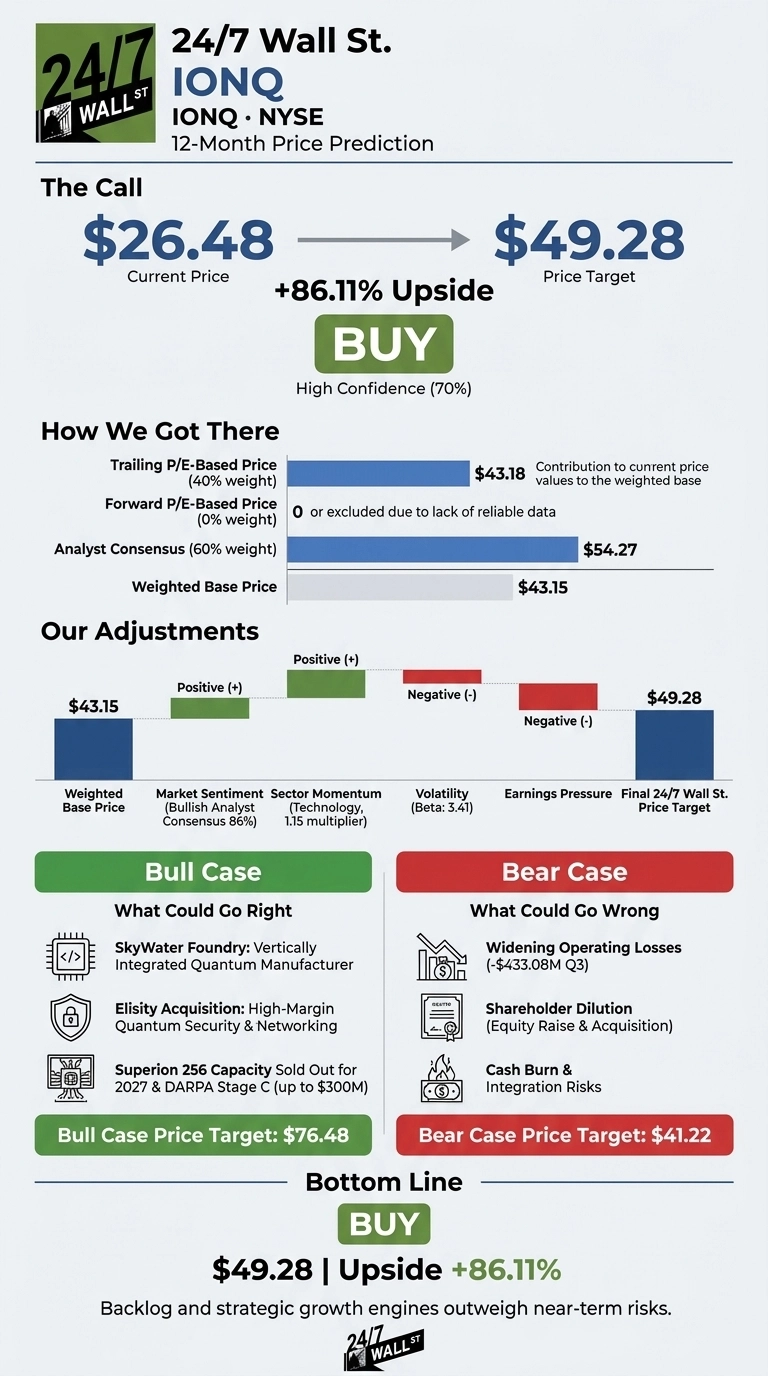
Our 24/7 Wall St. price target for IonQ (NYSE:IONQ | IONQ Price Prediction) is $49.28 over the next 12 months. Shares last traded at $26.48, which implies 86.11% upside. Our model rates the stock a buy with moderately high confidence.
| Metric | Value |
|---|---|
| Current Price | $26.48 |
| Price Target from 24/7 Wall St. | $49.28 |
| Upside/Downside | 86.11% |
| Recommendation | BUY |
| Confidence Level | 70% |

Two opportunities drive my thesis. The first is the SkyWater foundry, which turns IonQ into a vertically integrated quantum manufacturer.
The second is Elisity, a Zero Trust security business that moves IonQ further into post-quantum cryptography. A record quarter and a deep backlog support the target, and the stock now trades near its 52-week low.
A Record Quarter Met a 24% Weekly Slide
Shares fell 24.27% over the past week, 14.44% over the past month and 40.35% year to date. That leaves IonQ 64% below its $73.65 52-week high and 6.3% above its $24.91 low.
The selloff came after strong numbers. Third-quarter revenue reached $173.83 million[1] against a $141.20 million consensus, a gain of 336.04% year over year. Adjusted EPS of -$0.29[1] came in well ahead of the -$0.80 estimate. Management raised 2026 revenue guidance to $505 million to $515 million[1], and remaining performance obligations more than doubled to $1.2 billion.

Two Growth Engines Bulls Are Counting On
Opportunity 1: SkyWater. SkyWater contributed $83.5 million[1] of third-quarter revenue. Management said joint work delivered 12 times more wafer lots[2] and tape-out cycles for 256-qubit chips that run more than three times faster.
Superion 256 capacity is sold out for 2027, and NVIDIA (NASDAQ:NVDA) will install one of the systems at its Accelerated Quantum Research Center. IonQ also advanced to DARPA’s Stage C, a program worth up to $300 million[1].
Opportunity 2: Elisity. Chief Financial Officer Inder Singh called quantum security “a recurring-revenue, high-margin, uniquely positioned opportunity”[2] and said its addressable market could one day be larger than quantum computing’s.
Recurring software revenue at higher margins would speed the path to profitability. The analyst consensus target of $54.27 reflects 12 positive ratings and no Sells. The bull case reaches $76.48.

Cash Burn and Dilution Are the Risks to Track
IonQ posted a third-quarter operating loss of $433.08 million[1], and its adjusted EBITDA loss extended to $133.61 million. GAAP EPS of $1.35 diluted[1] relied on an $896.2 million non-cash warrant gain. The $2 billion equity raise and the stock-funded Elisity deal both dilute shareholders. Some backlog also depends on government funding that has not yet been allocated.
Offsetting those risks, the $3.7 billion pro forma cash position covers years of investment, and management expects fourth-quarter adjusted EBITDA to improve. The bear case still lands at $41.22.
IonQ Trades at a Discount to Rigetti and D-Wave on Revenue
Rigetti Computing (NASDAQ:RGTI) is a full-stack gate-model competitor. Its third-quarter revenue of $1.41 million missed estimates by 59.91%.
D-Wave Quantum (NYSE:QBTS) uses SkyWater for manufacturing, and its revenue reached $4.51 million. Both companies trade at far higher multiples of quarterly revenue than IonQ. Our target looks reasonable by comparison, and arguably conservative.
| Company | Market Cap | Market Cap / Q3 Revenue |
|---|---|---|
| IonQ | $12.29B | 71x |
| Rigetti | $3.11B | 2,201x |
| D-Wave | $3.26B | 723x |
Backlog Outweighs Volatility in Our Buy Rating
The 24/7 Wall St. price target of $49.28 carries a buy rating at 70% confidence. The backlog is what tips the scale for me.
The setup looks compelling if Elisity cross-selling raises margins and SkyWater supports Superion 256 production. It becomes far less attractive if losses keep extended into 2027. On balance, our model weighs the backlog more heavily than these risks.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $49.28 |
| 2027 | $51.96 |
| 2028 | $78.58 |
| 2029 | $105.10 |
| 2030 | $125.25 |
These projections assume IonQ keeps executing its current strategy.
Integration problems, dilution or delays in government funding could produce significant downside. A DARPA Stage C award could produce significant upside. For investors hunting the traits that showed up early in the biggest tech winners before their monster runs, we cataloged them in a free playbook here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.