IonQ Has a $3.7 Billion Runway That Could Send Prices to $65 or Higher in 2027

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

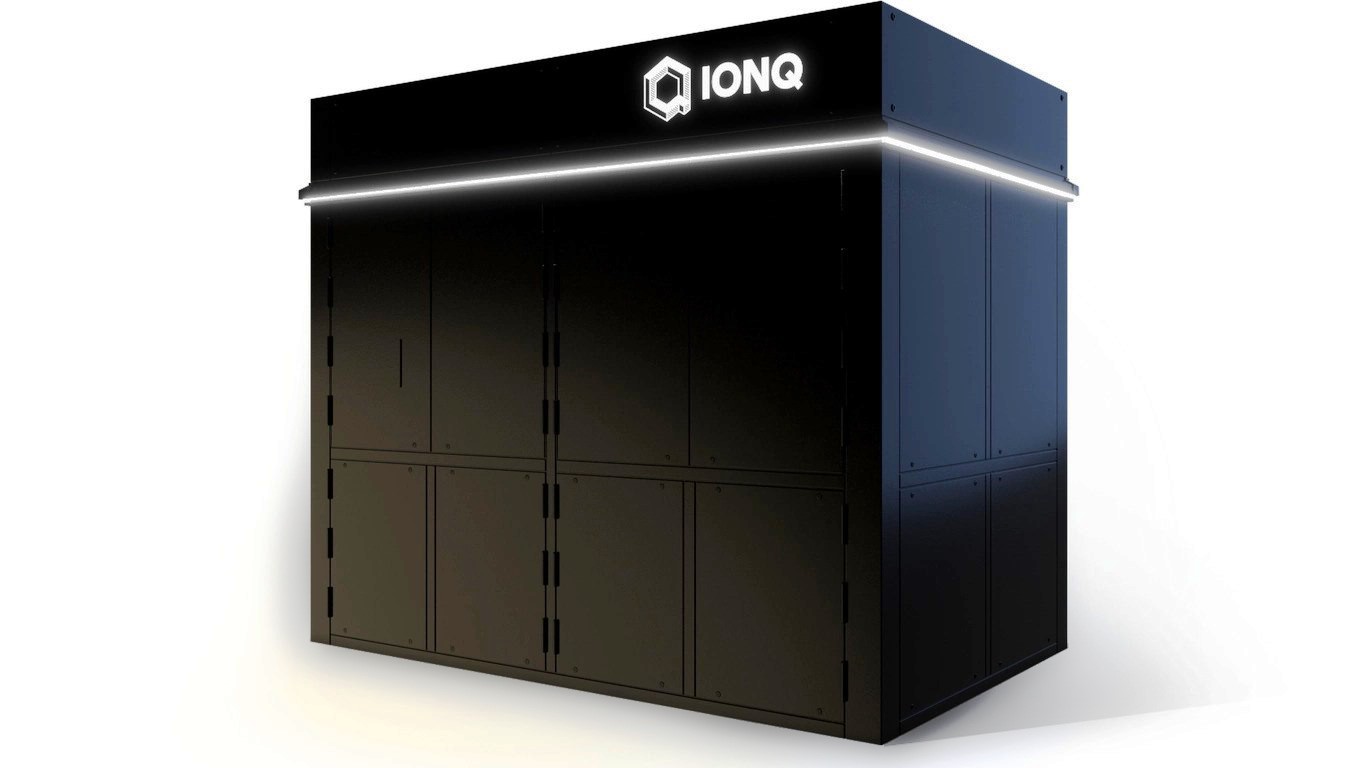
IonQ (NYSE:IONQ | IONQ Price Prediction) just posted what CEO Niccolo de Masi called “the strongest quarter in our company’s history”[1]. Third-quarter revenue reached $173.83 million[1], up 336% year over year. The stock still fell. Shares sit at $23.47, down 47.67% year to date and 31.06% in the past week alone. That gap between business results and share price raises the question for 2027: what would it take for IonQ to reach $65?
Wall Street Already Sees 131% Upside
The average analyst price target is $54.27, which means 131% upside. Analysts have issued 11 buy ratings and 1 strong buy, with zero sells. The consensus calls for 2027 revenue of $874.13 million, about 71% growth over 2026’s expected $510.47 million. IonQ has also beaten EPS estimates for four consecutive quarters. Most recently it reported -$0.29[1] against a -$0.80 consensus. The 2026 EPS estimate now stands at -$2.2291, better than -$3.7276 90 days earlier.
How a $3.7 Billion Cash Pile Changes the $65 Math
After a $2.0 billion equity raise closed October 16, IonQ holds $3.7 billion in pro forma cash. Spread across 462.88 million shares, that comes to about $7.99 per share, or roughly 34% of today’s price. The October dilution already did the painful work upfront. Once you subtract that cash, the market values the operating business at about 8x 2027 sales.
IonQ remains unprofitable, with a 2027 EPS consensus of -$3.1421, so price-to-sales is the better metric. At $65, shares would trade near 34x 2027 revenue estimates. That is close to the trailing price-to-sales ratio of 32x the stock carried recently.
What Could Push IonQ to $65?
- Sold-out demand: De Masi said, “We have, in fact, sold out all of our 256 capacity in 2027.”[2]
- Contracted visibility: Remaining performance obligations, meaning contracted revenue not yet recognized, more than doubled to $1.20 billion[1].
- AI validation: NVIDIA (NASDAQ:NVDA) plans to make a Superion 256 the first on-premise quantum computer at its Accelerated Quantum Research Center, with installation expected in 2027[2].
- DARPA Stage C: IonQ is the only trapped-ion company to advance, with a potential program value of up to $300 million[1].
- Cost discipline: Inder Singh, the chief operating officer and chief financial officer, expects fourth-quarter adjusted EBITDA to improve on the third quarter’s -$133.6 million[2]. Back-office consolidation is planned for 2027.
IonQ Traded Above $65 Within the Past Year
Reaching $65 requires a 177% gain. That’s a big move, but IonQ’s 52-week high is $73.65, and its beta of 3.41 shows how sharply the stock moves in either direction. Shares are still up 117.41% since 2021. The risks are real: operating cash flow was -$315.5 million last quarter, and stock-based compensation reached $146.9 million.
Bottom Line: A Cash Floor Makes $65 a Credible 2027 Stretch Goal
Hitting $65 means a 177% gain. Analysts already expect $54.27, revenue is projected to grow 71%, and close to $8 of each share is cash. If management combines that runway with disciplined cost cuts after its mergers, the stock could return to valuations it held within the past year. Returns at this level are rare, and we’ve outlined the plan for how IonQ could see strong gains by 2027.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.