One AI Catalyst Could Change This Stock’s Entire 2030 Forecast

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Broadcom (NASDAQ:AVGO | AVGO Price Prediction | AVGO Price Prediction) is expanding AI chip sales, but its stock is 2.41% lower year to date. In fiscal Q3, AI semiconductor revenue reached $16.70B[1], up 221% from a year earlier. Management expects $21.70B[1] in Q4.
The shares trade at $336.89. So can Broadcom reach $600 per share by 2030? I think the answer depends on one thing: the custom accelerator pipeline.

What’s Holding Broadcom Back Right Now
The stock is down 1.18% over the past year. Gains of 5.15% over one week and 2.18% over one month look like an early rebound. The stock has a beta of 1.508, so expect large moves in both directions.
I see three reasons investors are holding back. First, management warned that more XPU and memory content will reduce gross margin. Second, chip shipments and data center deployments may not line up on the same timeline. Third, the CFO said there is no overarching maximum[2] on future residual value guarantees tied to AI financing. A small group of six XPU customers[2] also carries most of the growth.
Analysts Are Optimistic. Here’s Whether That’s Justified
Wall Street’s consensus target is $529.24. There are 8 Strong Buy ratings, 41 Buys, 2 Holds and 0 Sells. Our model is more conservative. Its base case is $412.45, or 22.43% upside, inside a range of $366.74 to $537.55. The model’s confidence score is high, at 0.9.

I side with the analysts. Analyst sentiment is 96% bullish, yet earnings growth adds only 0.03 to the model’s adjustment. That small weight looks too low for a company that expects about $115 billion[2] in AI revenue in fiscal 2027.
Here’s What It Takes for Broadcom to Reach $600
Reaching $600 from today’s price of $336.89 would require a gain of 78.1%.
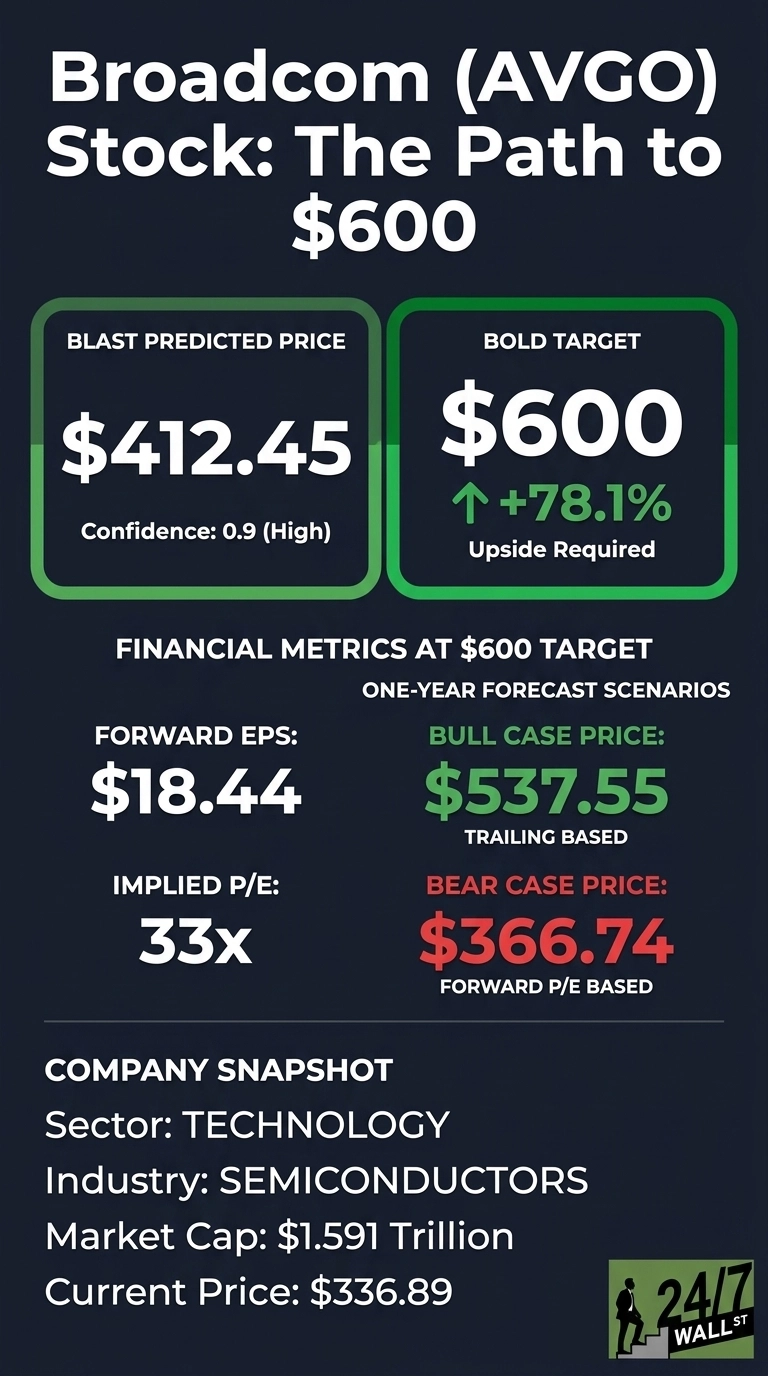
Forward EPS is $18.4365, so a $600 share price implies a forward P/E of 33x. Our base case of $412.45 implies 35x on a different earnings basis, about 2x above the bold target’s multiple. Still, $600 requires multiple expansion from today’s level.
Earnings growth does the work. The model’s adjustment factor of 1.146 reflects a technology sector multiplier of 1.15. Hock Tan said Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028.”[2]
At $600, that works out to just 20x earnings. He also said: “We have line of sight for fiscal 2028 AI semiconductor revenue growth to again double to $230 billion.”[2]
On October 26, 2026[3], four major banks and asset managers announced a $63 billion financing structure to fund AI computing capacity built with Broadcom. The main risk is that power, land or HBM shortages push deployments past 2028.
Where Broadcom Trades Today vs Its Earnings Power
At today’s price, Broadcom trades at 18x forward earnings. That is cheap for a company whose Q3 non-GAAP EPS grew 96%[2].
The stock sits between its 52-week low of $288.98 and its high of $493.32. Over 10 years, shares have returned 2,467.14%. In my view, today’s multiple prices in little of the fiscal 2028 outlook.
$600 Is a Stretch, but Here’s Why It’s Possible
Getting to $600 means a 78.1% gain. I call that a stretch, but a realistic one. The model’s own November 2030 targets are $577.86 in the base case and $870.39 in the bull case.
Three things need to go right. Anthropic, OpenAI and Google (NASDAQ:GOOGL) need to deploy on schedule. EPS needs to clear $30. Operating margins need to hold up as gross margin gets reduce.
A broad pullback in hyperscaler spending would undermine the thesis, and the chipmakers aren’t the only names exposed to it (we covered seven of the power, cooling, and networking suppliers riding the same expansion in a free report). The next targets is the fiscal Q4 report on December 9, 2026[3].
Returns at this level shouldn’t be expected every year, but we’ve outlined the path for how Broadcom could reach $600 in 2030.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.