This Is How Many Americans Have Socked Away At Least $500K for Their Retirement Years

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Millions of Americans are working to put money away for retirement, with outcomes that vary enormously from household to household. The number falling critically short is staggeringly high, leaving a large share of the population at genuine risk of a financially strained retirement that could last two decades or more.
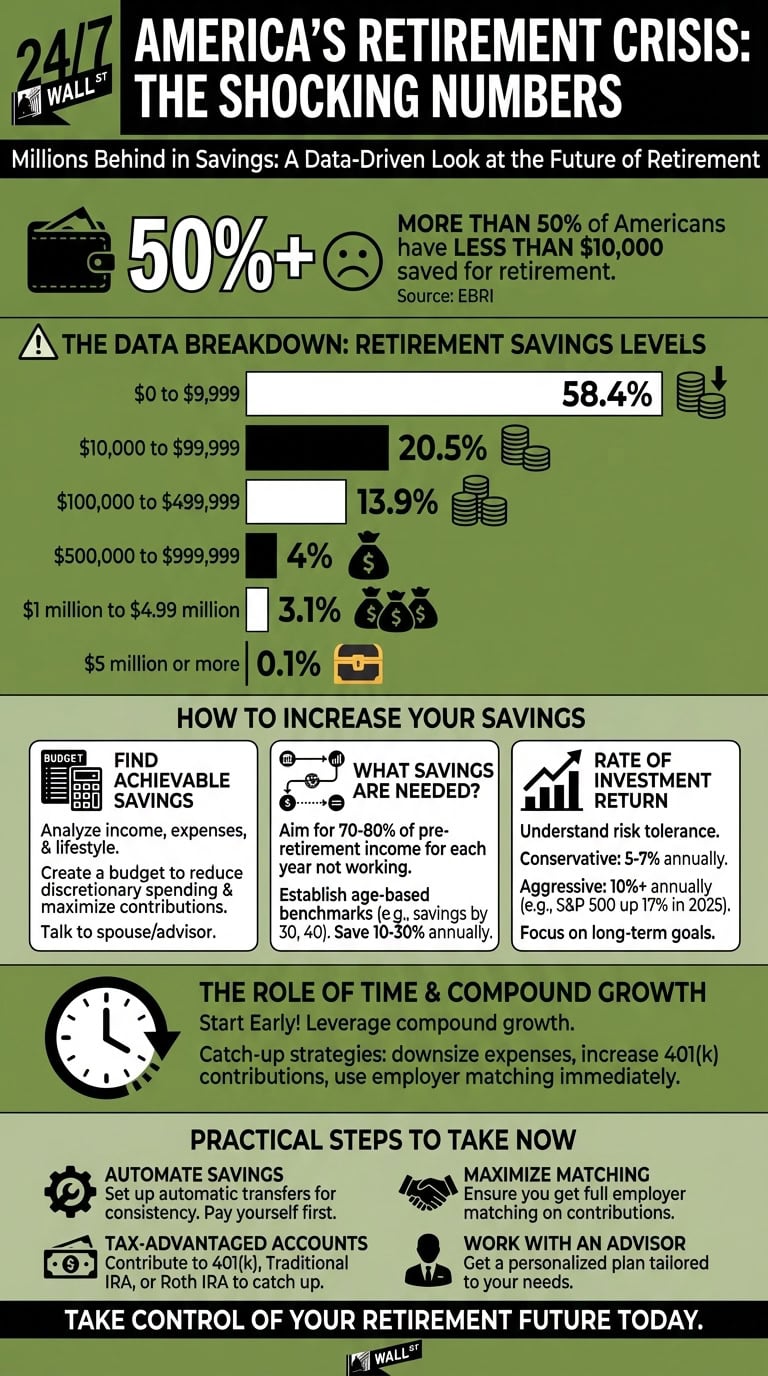
According to the Employee Benefit Research Institute, more than half of Americans have less than $10,000 saved for retirement. That figure is troubling on its own, but it becomes more striking when set against the far smaller share who have actually crossed the $500,000 threshold. Athene’s 2026 Retirement Outlook framed the total shortfall starkly: a $4 trillion retirement savings gap nationwide, with roughly 12,000 Americans reaching retirement age every single day.
The Data Breakdown
The EBRI data paints a vivid portrait of where Americans actually stand. The distribution of retirement account balances reveals a widening gulf between those who have saved meaningfully and the majority who have not:
- $0 to $9,999: 58.4%
- $10,000 to $99,999: 20.5%
- $100,000 to $499,999: 13.9%
- $500,000 to $999,999: 4%
- $1 million to $4.99 million: 3.1%
- $5 million or more: 0.1%
Fewer than 8% of Americans have crossed the half-million-dollar mark. Nearly 4.1 million Americans were set to turn 65 in 2025 alone, meaning this wave of retirees entered a system where only a small fraction had built the kind of cushion financial planners consider adequate for a comfortable, multi-decade retirement. Vanguard’s How America Saves 2026 report found the average 401(k) balance stands at $167,970, a figure that sounds substantial until measured against two or three decades of living expenses. The gap between what most people have saved and what a secure retirement actually costs has rarely been more visible.
The psychological toll is compounding the financial one. EBRI’s 2026 Retirement Confidence Survey found that worker confidence in having a comfortable retirement fell six percentage points from 2025 to just 61%, the lowest reading since 2017. Approximately 60% of workers said healthcare expenses are negatively affecting their ability to save, and about two in three said debt is a problem for their household finances. Those twin pressures are making it harder for people to feel secure about their retirement, even as contribution rates have improved.
The Inflation Factor: COLA and Purchasing Power
A $500,000 nest egg sounds substantial, but inflation steadily erodes its real-world value. On October 14, 2026, the Social Security Administration officially announced a 3.6% cost-of-living adjustment for 2027, the largest increase since 2023. The adjustment adds an average of $75 per month for nearly 72 million Social Security beneficiaries, lifting the typical monthly retirement benefit from approximately $2,095 to $2,170 beginning in January 2027. The 2027 COLA exceeds the 2.8% adjustment retirees received in 2026 and comes in well above the roughly 3.1% average over the past decade.
The deeper problem is structural. The CPI-W measures prices for urban wage earners rather than retirees, so it routinely understates the healthcare and housing costs that dominate a senior’s budget. According to the Senior Citizens League’s 2026 Loss of Buying Power report, Social Security benefits lost 13.7% of their purchasing power between 2016 and 2026, leaving the average benefit worth roughly 86 cents on the dollar compared to a decade ago. To restore benefits to their 2016 value, the average check would need to increase by about $295.85 per month, a gap no near-term COLA is likely to close. Compounding the challenge, the 2026 Medicare Trustees Report projects that the standard Part B premium will rise to approximately $209.50 per month in 2027, up from $202.90, which will absorb a portion of any COLA increase before it reaches a retiree’s bank account. Diversified income strategies, including equities and annuities, remain essential tools for protecting a portfolio’s real purchasing power over a long retirement.
Legislative Relief: The Social Security Fairness Act
Public sector workers received significant financial relief when the Social Security Fairness Act was signed into law on January 5, 2025. The legislation repealed the Windfall Elimination Provision (WEP) and the Government Pension Offset (GPO), two rules that had reduced Social Security benefits for millions of teachers, police officers, firefighters, and other government employees whose jobs were not covered by Social Security. By July 7, 2025, the Social Security Administration completed sending over 3.1 million payments totaling $17 billion to eligible beneficiaries, finishing five months ahead of its original timeline.
The practical effect for affected public servants is a meaningful boost in monthly income, cash flow that can be redirected into retirement savings. The repeal is retroactive to January 2024, so many recipients also collected lump-sum payments covering prior reductions. A separate dispute remains over whether certain beneficiaries who never filed a prior claim are entitled to a full 12 months of retroactive benefits, with senators pressing the SSA for clarity as recently as February 2026. Beyond the federal change, a growing number of states are also phasing out their own taxes on Social Security income, further increasing effective take-home pay in retirement.
What Role Does Time Play? Leveraging Super Catch-Ups
Starting early remains the most reliable path to a strong retirement balance, but the SECURE 2.0 Act created a powerful tool for those who are starting later. Workers aged 60 to 63 can take advantage of super catch-up contributions, an enhanced limit that exceeds the standard age-50-plus catch-up. For 2026, the super catch-up stands at $11,250, per IRS Notice 2025-67, which replaces rather than stacks on top of the standard $8,000 catch-up for that age group. Added to the base deferral limit of $24,500, eligible savers can contribute up to $35,750 per year into an employer-sponsored 401(k) before counting any employer matching contributions.
To illustrate the impact: a late starter who reaches age 60 with $250,000 saved and maximizes these contributions over a four-year window at a 7% average annual return could add roughly $163,000 in principal and compounded growth, closing nearly a third of the remaining gap to a half-million-dollar balance. The window is narrow, expiring when the participant turns 64, so confirming that your employer’s plan has adopted the super catch-up provision is a critical first step.
The Mandatory Roth Catch-Up Rule
High earners who want to use these enhanced limits face a new requirement under SECURE 2.0. Beginning January 1, 2026, workers whose FICA wages from their current employer exceeded $150,000 in the prior year must route all catch-up contributions into a Roth account rather than a traditional, pre-tax account. This applies to all catch-up contributions, including the super catch-up for those aged 60 to 63. The $150,000 threshold was set by IRS Notice 2025-67, which raised the original $145,000 statutory floor after a cost-of-living adjustment.
Paying taxes upfront on catch-up contributions reduces take-home pay in the short term, but the trade-off is tax-free growth and tax-free qualified distributions in retirement. For high earners who expect to remain in elevated tax brackets throughout their later years, that structural benefit can more than offset the immediate cost. One important caveat: if an employer’s plan does not currently offer a Roth option, the plan will need to add one before high-earning participants can make any catch-up contributions at all under the new rules.
Rate of Investment Return and Portfolio Volatility
The return assumptions built into a retirement plan matter enormously over a multi-decade horizon. A conservative 5% to 7% annual return is a reasonable baseline for a diversified portfolio, while more aggressive savers who concentrate in equities often target 10%. In the current market environment, with AI-driven technology stocks commanding elevated valuations, the higher end of that range is achievable but comes with meaningful volatility risk.
As balances approach the $500,000 mark, the nature of risk shifts in an important way. A poorly timed market correction at the start of retirement can permanently impair a portfolio, because withdrawals lock in losses before the portfolio has time to recover. Financial planners call this sequence-of-returns risk, and it is one reason why gradually shifting toward a more conservative allocation in the five years before retirement is widely recommended for anyone who cannot afford a deep early drawdown. EBRI research tracking retirees over two decades found that low-asset retirees without pension income lost 89% of their savings over a 21- to 22-year retirement period, compared to just a 29% decline for those who received defined-benefit pension income. That gap underscores how critical a steady income floor can be to portfolio longevity.
Practical Steps You Can Take
Automating contributions remains the simplest way to build consistency. Payroll deferrals remove the temptation to spend first and save later, and automatic increases tied to raises can push savings rates higher without requiring active decisions year after year. The EBRI 2026 survey found that total 401(k) savings rates, including employer contributions, climbed to 14.4%, approaching the 15% rate many retirement experts recommend. That direction is encouraging, even if average balances still fall far short of what most households will ultimately need.
Beyond 401(k)s and IRAs, the tax treatment of withdrawals deserves careful attention. As state-level Social Security taxation continues to evolve across the country, coordinating Roth conversions with a qualified advisor can lower the effective tax rate on retirement income and preserve more of a hard-earned balance for actual living expenses rather than tax bills.
Editor’s note: This pass corrected the description of the 2027 COLA from “the largest increase in four years” to “the largest since 2023,” reflecting the actual 8.7% COLA issued that year; the average pre-COLA monthly Social Security benefit was updated to approximately $2,095, with the post-COLA figure confirmed at approximately $2,170. Language around the Medicare Part B 2027 premium was updated to reflect that the $209.50 figure remains a projection from the 2026 Medicare Trustees Report, not yet an official CMS figure.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.