A $1.7 Million Portfolio That Quietly Pays $9,800 a Month and Outpaces the Median U.S. Mortgage Payment Twice Over
Pulling in $9,800 a month from a portfolio without selling a single share is the kind of math that can completely reshape a retirement plan. That works out to $117,600 a year, more than four times the median U.S. monthly…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Pulling in $9,800 a month from a portfolio without selling a single share is the kind of math that can completely reshape a retirement plan. That works out to $117,600 a year, more than four times the median U.S. monthly mortgage payment of approximately $2,134 for principal and interest, based on the April 2026 median existing home price of $417,700 and current mortgage rates. For a 64-year-old couple with a paid-off home, that level of income can comfortably cover their own living expenses while also helping two adult children with housing costs.
The Capital Required at Three Yield Levels
The equation is straightforward. Income target divided by yield equals the capital you need. Everything else is a tradeoff conversation.
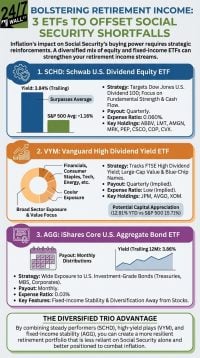
Conservative tier, 3% to 4% yield. At a 3.5% blended yield, $117,600 divided by 0.035 equals roughly $3.36 million. This is the broad dividend growth lane: large-cap dividend aristocrats and quality dividend ETFs. Schwab U.S. Dividend Equity ETF (NYSEARCA:SCHD) is the canonical example. Its March 2026 reconstitution shifted the portfolio toward financials, health care, and technology while trimming energy and consumer cyclical names, leaving current top holdings that include Merck, ConocoPhillips, and Chevron at a rock-bottom 0.06% expense ratio. SCHD paid approximately $1.05 per share in total distributions over the trailing year. The Q1 2026 payout was $0.2569 per share, and Q2 2026 came in at $0.2525, a modest quarter-to-quarter dip that reflects normal seasonal variation rather than a change in the underlying growth trend. The share price sits at roughly $35, yielding close to 3.1% on a trailing basis. You need the most capital at this tier, but the principal is most likely to grow with the market and the payout typically rises every year.
Moderate tier, 5% to 7% yield. At nearly 7%, $117,600 divided by 0.0692 equals roughly $1.7 million. This is the headline portfolio. The blueprint mixes 30% dividend equity and REITs at 4.5%, 25% high-yield bond ETFs at 7.0%, 25% covered-call ETFs at 8.5%, 10% preferred shares at 8.7%, and 10% midstream MLPs at 8.0%. Midstream names like MPLX (NYSE:MPLX | MPLX Price Prediction | MPLX Price Prediction) and Enterprise Products Partners (NYSE:EPD) anchor the high-yield sleeve. MPLX confirmed a Q2 2026 quarterly distribution of $1.0765 per unit, matching its Q1 level and translating to $4.31 annualized, with management targeting a 12.5% increase in annual distributions for 2026 and 2027. Enterprise Products Partners raised its Q2 2026 payout to $0.56 per unit ($2.24 annualized), a 2.8% increase over the prior-year quarter, extending its streak of consecutive annual distribution increases to 28 years.
Aggressive tier, 8% to 14% yield. At 12%, $117,600 divided by 0.12 equals roughly $980,000. The capital required collapses, but so does the safety net. This tier leans on leveraged covered-call funds, business development companies, mortgage REITs, and high-yield bond funds. Distributions get cut, NAV erodes during recessions, and a portfolio that looks flush on paper can quietly shrink in real value even while mailing large monthly checks.
Why Yield Alone Misleads
A 3.5% yield growing at 8% annually can double its income stream in roughly nine years. A flat 12% payout stays flat and can sometimes shrink. That difference becomes critical in retirement, where purchasing power matters as much as current income.
SCHD illustrates the compounding story well. The Q1 2026 payout of $0.2569 per share was the largest first-quarter distribution in the fund’s history, up 3.3% from Q1 2025. The Q2 2026 distribution followed at $0.2525 per share, a normal seasonal dip that has appeared in prior years as well. SCHD has also attracted renewed investor attention in 2026, drawing $679 million in net inflows over a single five-day stretch in August as a defensive rotation away from growth accelerated. EPD tells a parallel story from the MLP side: the partnership raised its Q2 2026 distribution to $0.56 per unit, extending 28 straight years of annual increases, with units trading around $37.
Over a 20-year retirement window, lower starting yields paired with growing distributions often outperform high yields that stagnate. That calculus grows sharper when 10-year Treasury yields hover near 4.7% and inflation continues to press on purchasing power. The 10-year note finished August 2026 near its highest level in more than a year, reinforcing that income investors who anchor too heavily to headline yield today risk shortchanging themselves a decade from now.
Three Moves Before You Build It
- Pressure test the $9,800 number against actual spending. The household above already owns the home outright, so the $2,400 equivalent rent is optional. Most pre-retirees model salary replacement when they should model spending replacement, and the gap is often 20% to 30%.
- Place each yield bucket in the right account. Ordinary-income payers (high-yield bond ETFs, BDCs, mortgage REITs) belong in the IRA. Qualified-dividend ETFs like SCHD belong in the taxable brokerage. MLPs such as MPLX and Enterprise Products Partners generate K-1 forms with tax-deferred return-of-capital characteristics, and many investors prefer the AMLP wrapper to skip the K-1 entirely.
- Compare 10-year total return rather than headline yield. Pull a 10-year chart of a 3.5% dividend-growth fund against a 10% covered-call fund. The compounding gap is the entire argument for accepting a lower current payout when you have the capital to do so.
A $1.7 million portfolio at roughly 7% yield is achievable, repeatable, and quiet. The harder discipline is choosing the yield level that still leaves the principal intact two decades from now.
Editor’s note: This pass updated the SCHD share price from roughly $32 to roughly $35 to reflect late-August 2026 trading levels, refreshed the SCHD top-holdings list to reflect the March 2026 reconstitution (which removed Bristol-Myers Squibb and several other names), added Q2 2026 distribution data for both SCHD ($0.2525 per share) and MPLX ($1.0765 per unit), noted MPLX management’s 12.5% annual distribution growth target for 2026 and 2027, updated the 10-year Treasury yield reference from “around 4.6%” to “near 4.7%” consistent with late-August 2026 readings of 4.72% to 4.75%, and added context about the August 2026 defensive rotation into dividend ETFs.
Contact [email protected] for any questions or corrections.
Drew Wood has edited or ghostwritten nine books and published more than 1,500 articles on investing, business, politics, travel, world cultures, wildlife, and earth science. He holds a doctorate and four master's degrees and has nearly 30 years of college teaching experience. His travels have taken him to 25 countries, including three years living in Ukraine.