Roger Whitney to 60-Year-Old With $3.5M: ‘Continue to Save in Your Roth 401(k) and Use Your After-Tax Cash’

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A 60-year-old caller named Sue brought a question to the Retirement Answer Man podcast that sounds routine but could shape the rest of her retirement. Her decision about whether to keep saving in a workplace plan is one of the most consequential choices a pre-retiree can make.
She and her husband hold just under $3.5 million: $2.1 million pre-tax, $1.3 million taxable, $80,000 in Roth savings, and $300,000 in cash. Sue is still working and plans to retire at 62. Before that date, she wants roughly $100,000 for home projects.
Her instinct, in her own words: “I would like to stop saving for retirement and use the cash for projects around the house. About $100,000 before I retire.” Her plan was to halt Roth 401(k) contributions, let each paycheck rebuild the cash account, and pay for the renovations without touching the $300,000 reserve.
Roger Whitney recommended the opposite: keep maxing out the Roth 401(k), and spend the cash.
The verdict: Whitney’s advice holds up
Whitney is a CFP, CIMA, CPWA, and RMA who hosts the Retirement Answer Man podcast. His view of this call is that it should be judged by tax buckets rather than by the size of each account balance. That framing is what separates his answer from a simple cash-versus-investments comparison. tax buckets
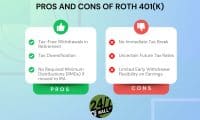
Whitney’s central idea is optionality. Two pools of money can each pay for a kitchen remodel, but they do not behave the same way later. Cash carries no special tax treatment. Roth 401(k) room left unused in a given year cannot be recovered in a future year.
He framed the fallback this way: “If you use your $100,000 in after-tax cash and you continue to save in your Roth 401(k), and say 3 years from now you realize, wow, we don’t have as much cash as we needed in our cash reserves, you can always take the money from your Roth.”
He also described what Sue would give up by pausing: “Whereas if you stop saving in your 401(k) in order to preserve your cash, you lose that option on the money that could have been growing tax-free forever.”
Walking through the math
Consider two paths over the two years before Sue retires at 62.
Path A (Sue’s instinct): She stops contributing and sends her paychecks into cash, then pays for the projects from new savings. The $300,000 reserve stays largely intact. However, her Roth 401(k) stays at whatever balance she built before this year, and the contributions she skips never have the chance to grow tax-free.
Path B (Whitney’s call): She keeps maxing out the Roth 401(k) and pulls $100,000 from the $300,000 cash pile for the renovations. The cash cushion falls to $200,000, which is still substantial, and two more years of Roth contributions compound tax-free for the rest of her life.
For 2026, the standard 401(k) deferral limit is $24,500. Because Sue is 60, she can use the higher catch-up that applies to ages 60 to 63 if her plan offers it.
The IRS says the $11,250 catch-up for those 60 to 63 applies in place of the usual $8,000 catch-up, not on top of it, and it first took effect in 2025 under SECURE 2.0. Sue’s total limit for 2026 would therefore be $35,750 if her plan supports it. If the $200,000 cushion holds through retirement, the Roth balance is never touched and keeps growing untaxed. If cash runs short, Sue is already past age 59.5, so qualified Roth withdrawals come out tax-free once the 5-year requirement is met. In that sense the Roth account can serve as both a retirement fund and a backup reserve. Cash can only ever be cash.
The variable that changes the answer
The whole calculation depends on whether Sue can reach the Roth money without penalty when she needs it. For a 60-year-old, two tests matter. The first is age 59.5, which she has already passed. The second is the 5-year rule on the Roth 401(k) itself. Sue only recently began maximizing Roth contributions, which explains why her Roth balance is small compared with the rest of her portfolio. If that account is new this year, the clock matters.
A Roth 401(k) runs its own 5-year seasoning period, separate from a Roth IRA. Sue has two workable routes. She can roll the balance into a Roth IRA that she has held for more than five years, or she can wait until the 401(k) itself reaches the five-year mark. Once both conditions are met, qualified withdrawals are tax-free and penalty-free.
For a saver under 59.5, the math changes considerably. A Roth 401(k) that is needed for a roof repair two years after funding can mean a hardship withdrawal, a plan loan, or penalties. In that situation, cash is the more practical choice. For Sue, age has already opened that door.
How the 2026 Roth catch-up rule affects high earners
A SECURE 2.0 provision that took effect in 2026 requires workers age 50 and older whose prior-year FICA wages from the plan sponsor exceeded $150,000 to make their catch-up contributions as Roth contributions. Those workers cannot use the pre-tax option for catch-ups.
IRS Notice 2025-67, released November 13, 2025, raised the wage threshold from $145,000 to $150,000. The threshold is measured by Social Security wages in Box 3 of the W-2, not by total compensation. Treasury and the IRS issued final regulations on September 16, 2025. Plans are expected to follow a good-faith interpretation of the rule during 2026, and the final regulations formally apply starting in 2027.
If Sue’s 2025 FICA wages exceeded $150,000, her catch-up dollars must already go into the Roth account. In that case, Whitney’s recommendation matches what the tax code now requires. Even if her income fell below the threshold, the optionality argument would still apply. Roth contribution room is limited each year, and it matters most for someone two years from retirement who has built only a small Roth balance over a long career.
Looking ahead to 2027
The IRS had not announced the 2027 retirement plan limits as of late October 2026. Milliman projects the 401(k) employee limit will rise to $25,500 in 2027, with the age-50 catch-up increasing to $8,500 and the 60 to 63 super catch-up rising to $11,750. Those figures are projections until the IRS publishes its notice. The projected wage threshold for the Roth catch-up rule is $155,000 for 2027, according to the same projection. Because the IRS notice is the official source, savers planning for next year should confirm the final numbers before adjusting paycheck deferrals.
What to actually do with this
- List every pool of money you hold, sorted by tax treatment: pre-tax, Roth, taxable, and cash. Sue’s split of $2.1 million pre-tax, $1.3 million taxable, $80,000 Roth, and $300,000 cash shows the imbalance immediately. Her portfolio is light on Roth assets and heavy on cash, which is why directing cash toward home projects while protecting Roth contribution room makes sense.
- Confirm your Roth 401(k) start date and your current age. Past 59.5, with the 5-year clock running or already satisfied through a rollover into an older Roth IRA, the account can act as an emergency backstop. Below that age, the analysis changes significantly.
- Before cutting contributions to build cash, ask whether the cash you already have covers the goal. If it does, the contribution room is worth more than the liquidity you would rebuild by pausing contributions.
- Treat each year’s contribution limit as a use-it-or-lose-it allowance. Unused room expires on December 31 and does not carry forward. For 2026, the 401(k) limit is $24,500 in base contributions, plus $8,000 in standard catch-up for savers 50 to 59 and those 64 and older, or $11,250 in super catch-up for those 60 to 63. The IRA limit of $7,500 applies to traditional and Roth IRAs combined, and savers 50 and older can add a $1,100 catch-up for an $8,600 total. Roth IRA eligibility phases out at higher incomes.
Cash you already hold can be spent once and rebuilt over time. A Roth contribution year that is skipped cannot be reclaimed.
Editor’s note: The article now notes that the IRS had not yet published 2027 retirement plan limits as of late October 2026, with Milliman projecting a $25,500 401(k) deferral limit for next year. It also confirms that the $150,000 Roth catch-up wage threshold applies to 2025 wages under IRS Notice 2025-67, and that the final regulations formally apply starting in 2027.
Contact [email protected] for any questions or corrections.
I've been writing about stocks and personal finance for 20+ years. I believe all great companies are tech companies in the long run, and I invest accordingly.