They’re Planning to Sell the Development Rights on the Ranch for $600,000 and Still Run Cattle on Every Acre. The Only Thing That Changes Is That Nobody Can Ever Pave It
Selling a ranch's development rights can put six figures in a landowner's pocket while cattle keep grazing every acre, but the tax code, perpetual deed restrictions, and IRS scrutiny make the decision far more complicated than cashing a check.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
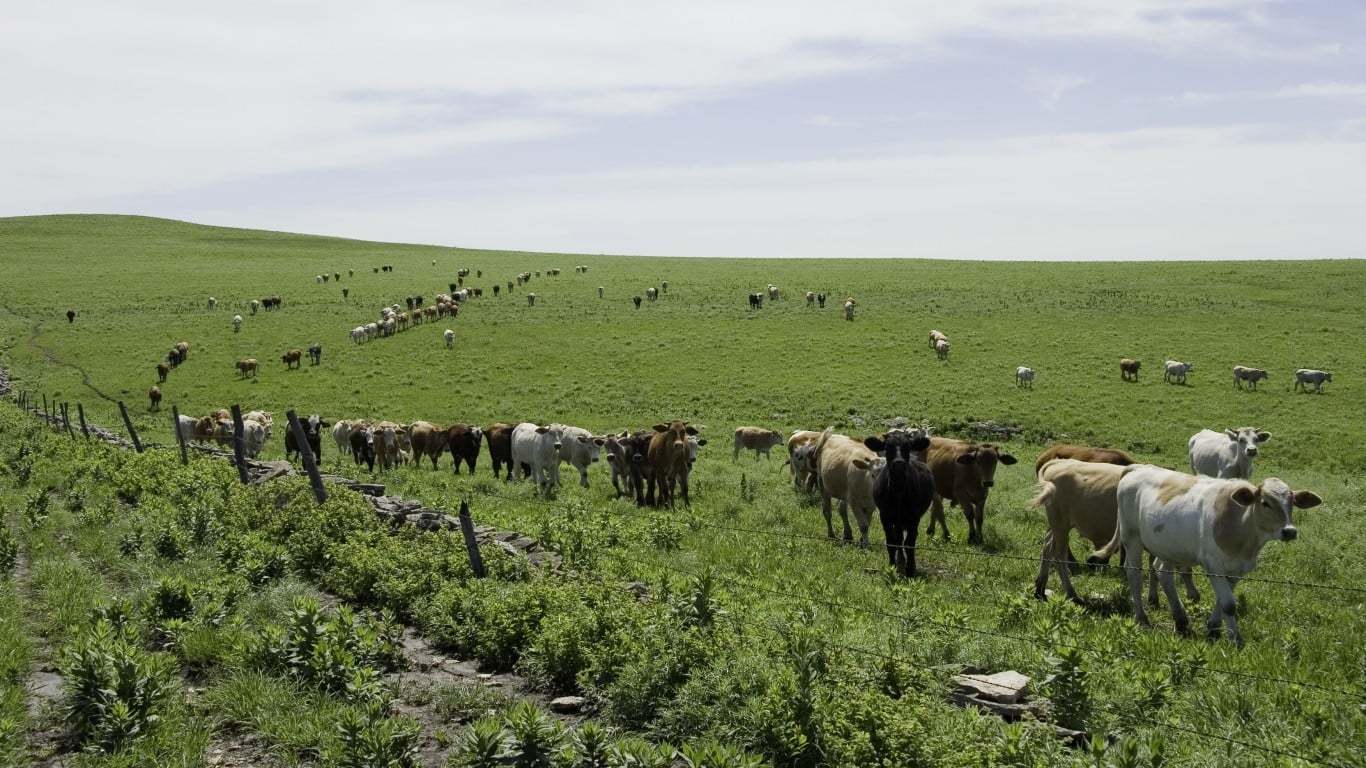
A working ranch near a growing town holds two separate assets: the grass and water that feed cattle, and the legal right to subdivide and build. Buying development rights, recorded as a conservation easement, lets a landowner sell that second asset to a land trust or public program for cash, such as a $600,000 offer. The owner keeps the title, the herd, and grazing on every acre. The ground can never be paved, and the tax code rewards the deal in several ways.
What Selling Development Rights Gives Up and What It Keeps
A conservation easement is a permanent deed restriction held by a qualified organization, usually a land trust or government agency, that removes the right to subdivide, build housing, or convert land to commercial use. Ranching and haying continue as before. The owner can still sell the ranch or leave it to heirs; every future owner inherits the restriction. The IRS treats the payment as proceeds from selling part of the property. The gain counts as a capital gain measured against the basis allocated to the development rights.
Federal Code Sections That Back It Up
Three federal tax provisions drive the economics of an easement sale. Internal Revenue Code §170(h) defines a qualified conservation contribution and allows a charitable deduction when an easement is donated or sold below appraised value. Section 170(b)(1)(E) sets deduction limits. Section 2031(c) excludes part of easement-restricted land from the taxable estate, capped at the lesser of $500,000 or 40% of the land’s net value.
Who Gets the 100% Deduction and Who Gets Left Out
Most donors can deduct the gift portion of an easement up to 50% of adjusted gross income (AGI) in a single year. A qualified farmer or rancher can deduct up to 100% of AGI. To qualify, the owner must earn more than 50% of total gross income for the year from farming. Any unused deduction carries forward for 15 years. Owners who lease out the ranch usually fall under the 50% cap. The 100% limit applies only when the easement requires the land to remain available for agriculture or livestock production.
How to Structure the Sale Before Signing Anything
- Choose a qualified holder. Land trusts, county open-space programs, and the USDA’s Agricultural Conservation Easement Program buy development rights.
- Order a qualified appraisal. The appraiser values the ranch before and after the restriction. If that value exceeds the purchase price, the difference becomes a §170(h) deduction, reported on IRS Form 8283.
- Allocate basis. A tax preparer assigns part of the land’s basis to the development rights. Proceeds above that share are taxed as long-term capital gain for land held longer than a year.
- Check state credits. Colorado issues a transferable state income tax credit worth up to 90% of the donated value of an easement (up to state statutory caps). Other states run their own tax credit programs with varying terms, which you can sell or transfer to offset state income tax liabilities.
- Reserve rights in writing. Spell out future homesites, barns, corrals, and water rights in the deed before closing.
Catches That Make This Deal Permanent and Audit-Prone
The easement restriction lasts in perpetuity. Buyers pay less for land they can never develop, so the ranch’s resale value drops toward its agricultural value. Heirs cannot reverse the decision. The IRS examines easement deductions closely. It labels certain deals as abusive tax avoidance transactions, mainly pooled arrangements where investors bought partnership stakes promising deductions far larger than their cash spending. The SECURE 2.0 Act, passed in late 2022, added §170(h)(7).
This provision denies the deduction for easements contributed through partnerships or S corporations when the deduction exceeds 2.5 times the owners’ modified basis. A family selling development rights on its own ranch falls outside that structure, but inflated appraisals still trigger audits. In Oconee Landing Property v. Commissioner (T.C. Memo. 2024-25), the Tax Court held that an easement cannot be worth more than the land beneath it.
Before accepting an offer, landowners should compare the cash price, the appraised easement value, and the reserved rights side by side. The biggest variables are the appraisal, farm income status for the 100% limit, and whether the state adds a credit on top of the federal deduction.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.