Let’s Be Real. Retirees Who Price Every Caribbean Island Will Keep Ending Up on the Same One
Every Caribbean retirement spreadsheet starts with a dozen islands and ends somewhere unexpected, and the reason almost always traces back to a single line item that most comparison guides never price correctly.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
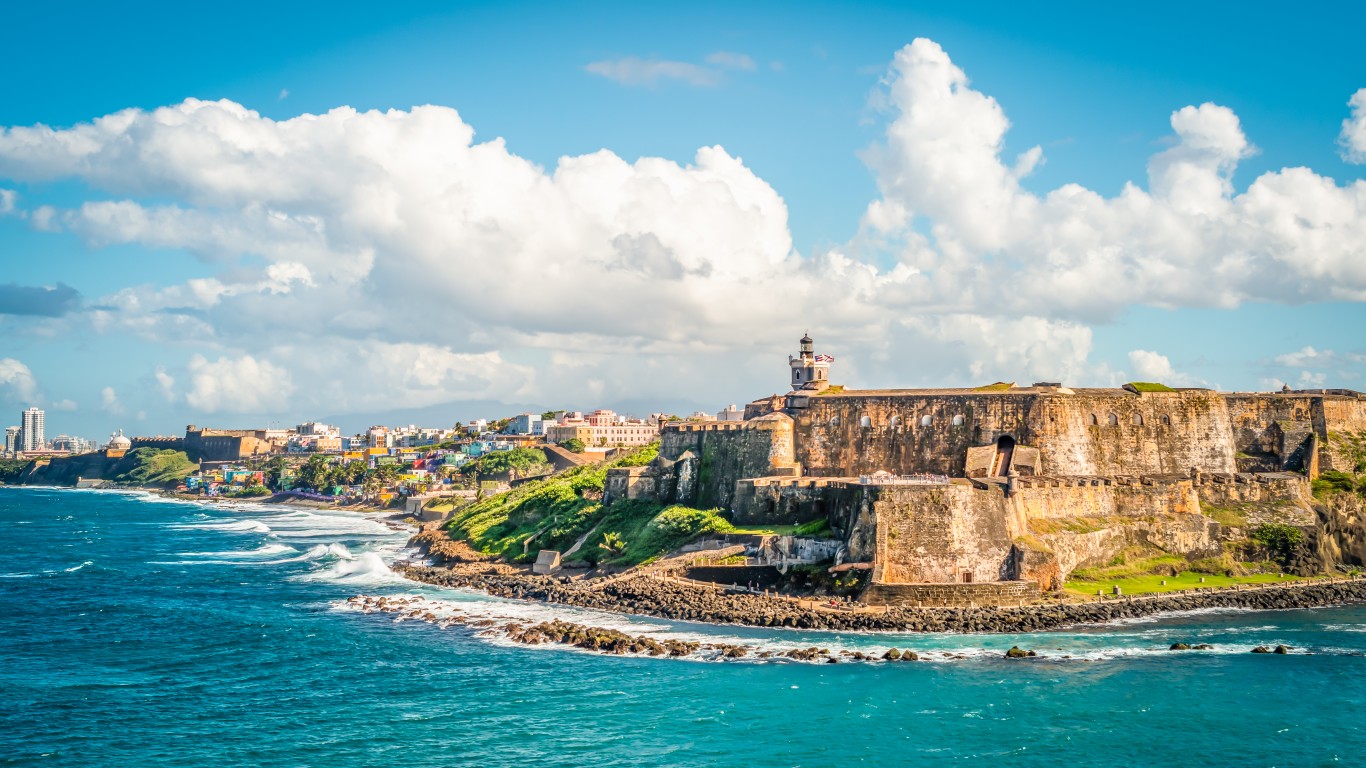
Anyone who has built a Caribbean retirement comparison in a spreadsheet will recognize the pattern. Aruba looks great until you reach the health insurance line, and Barbados hits the same wall. The Dominican Republic is cheap until a heart specialist comes into the picture. By the fourth island, the list has usually shrunk to Puerto Rico. This piece looks at why that keeps happening, and what it costs a retired couple to make Puerto Rico work.
Your Medicare Card Works in San Juan but Stops at Foreign Borders
Medicare generally doesn’t pay for care outside the United States. Exceptions are narrow, such as when you’re in the U.S., and the nearest hospital that can treat you is across the border. For Medicare purposes, the U.S. covers all 50 states, the District of Columbia, Puerto Rico, U.S. Virgin Islands, Guam, American Samoa, and the Northern Mariana Islands. Two of those are in the Caribbean; in Puerto Rico, original Medicare covers inpatient and outpatient services like in the 50 states, and Part D drug coverage is sold as stand-alone plans or through Medicare Advantage, the private-plan version of Medicare.
In Barbados, Aruba, or the Dominican Republic, you’d buy private international coverage or pay cash. In Puerto Rico, your existing coverage keeps working, including care for chronic conditions.
Most comparisons miss what happens to Part B, Medicare’s outpatient side, on a foreign island. Keep it, and you pay the standard $202.90 a month each for coverage you can only use on visits home. For a couple, that’s about $4,870 a year. Drop it, and the late enrollment penalty lasts for as long as you have Part B coverage once you return, growing the longer you waited. In Puerto Rico, the same premium buys coverage you can actually use.
Running the Numbers for a Couple in Puerto Rico
The average U.S. household spends about $78,535 a year. Then add the island’s electricity premium. A record rate of 33.86 cents per kWh just took effect, against a mainland residential average of 18.3 cents. At 800 kWh a month, the bill is about $271. That’s roughly $1,494 a year more than mainland rates, on top of the household average. Part B premiums for two must fit within that budget.
On the income side, the average retired-worker Social Security benefit is $2,087.52 a month. Together, they total about $50,100 a year, leaving a shortfall of roughly $29,900. At a 4% withdrawal rate, that requires about $748,000. At 3.5%, it’s about $855,000.
The 3.5% figure leaves more buffer, because hurricane insurance and battery backup aren’t priced into that budget (we made the full case for retiring the 4% rule in favor of an income-first approach in a free guide here). Inflation matters here too: CPI rose about 3.4% year over year, and the 2027 COLA is tracking at 3.3%. Either spouse can wait until 70 to claim, and the bigger checks reduce the gap for life.
What the Tax Brochures Leave Out
Under federal rules, a bona fide resident’s U.S. gross income doesn’t include income from sources within Puerto Rico. Social Security, 401(k) withdrawals, and mainland dividends don’t come from Puerto Rico, so they stay on your federal return.
Act 60’s resident investor decree is the incentive people hear about most. Act 38-2026, signed in March 2026, changed it. Applications filed by December 31, 2026, keep the 0% rate. Applications filed after that pay a flat 4% Puerto Rico rate on interest, dividends, and post-residency capital gains, and applicants must prove they weren’t residents for the six years before moving. The reform still needed approval from an oversight board in the last report. Because the decree covers only investment income, it does little for a retiree living on Social Security and retirement-plan withdrawals.
Where Keeping Medicare Stops Being Enough
Medicare only helps if there are doctors to see. An Associated Press report found the territory’s doctor count dropped from 14,000 to 9,000 over a decade, and Medicare Advantage payments to Puerto Rico are expected to decrease compared with what the rest of the country receives. The power grid is fragile too. A substation fire recently left more than 200,000 customers without power, nearly a decade after Hurricane Maria.
This plan fits best if you’re managing a chronic condition and need Medicare to keep working. It fits poorly if you need frequent trips to a major mainland medical center or can’t live with outages. The U.S. Virgin Islands also keep Medicare.
What It Takes to Land on This Island
For a couple relying on typical Social Security benefits, the target is about $855,000 invested, supporting a 3.5% withdrawal rate. Some retirees keep a few years of withdrawals in a Treasury ladder so a hurricane season or a bad market year doesn’t force a sale of stocks at a loss. Delaying Social Security lowers the target. A pension lowers it more.
Before pricing a single property, it helps to know what happens to health coverage on that island. On the foreign islands, the answer adds a second insurance bill. In Puerto Rico, your Medicare keeps working as long as specialists are available to see you.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.